If you’ve talked to me in the last week, you’ve probably heard me mention that rates are moving again — and not in the direction anyone renewing or buying wants to see.
This isn’t just noise from one lender repricing on its own. Canada’s 5-year government bond yield — the number that drives most fixed mortgage rates — jumped roughly 25 basis points in a single week. Major banks have raised their posted rates 10-20 basis points in response, and some lenders have moved 20 basis points or more as they pull back discretionary discounts.
What’s actually driving this?
The short version: renewed conflict between the U.S. and Iran has disrupted oil shipments through the Strait of Hormuz, and that kind of energy-market shock tends to ripple straight into bond yields — and from there, into the fixed rates lenders can offer.
It’s genuinely hard to predict where this goes next. Some analysts expect yields to keep grinding higher over the next while; the bond market is even pricing in the possibility of further Bank of Canada moves over the next 12 months. But this is a geopolitical story, not a purely economic one — a de-escalation could ease the pressure just as quickly as it appeared.
What this means if you’re renewing or buying soon
You don’t need to predict the market to protect yourself from it. A pre-approval locks in today’s rate for 90-120 days, with no obligation to use it if rates happen to come back down before you close. It’s simply an option — one that costs you nothing to hold and could save you real money if this upward trend continues.
If your renewal or closing is coming up in the next few months, now’s a good time to have that conversation rather than wait and see where things land.
I look forward to hearing from you in regard to your mortgage needs.
902-465-5533. I answer.
Patrick
p.s. Ready to see what you qualify for? Apply now
p.s. Prefer to talk it through first? Book a call
p.s. Licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI.
p.s. Want to run your own numbers first? Try MortgageClarity.ai
Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone.
Questions about locking in your rate before the next move? Call 902-465-5533 or apply now.
Tags: Mortgage Rates, Fixed Rate Mortgage, Bond Yields, Mortgage Renewal, Pre-Approval, Halifax Mortgage Broker, Nova Scotia Mortgage Broker
Should you switch mortgage lenders at renewal, or just take the rate your bank offers you? Twice this week, I told a client to stay exactly where they are.
Both were renewals. Both were with the same lender I’d placed them with myself, years ago. And both times, when I went shopping for a better deal, I ran into the same wall: the rate their own bank was offering them directly, just for renewing, beat anything I could get them through the broker channel. No fees either way. Just a better number, sitting right there in their inbox.
So I told them to take it.
Here’s the part that might surprise you: that’s not me being generous. That’s the whole point of having a broker in the first place.
Why this happens
Lenders price differently depending on the door you walk through. Sometimes the “retention” rate — the one they send you directly to keep you from shopping around — is genuinely sharper than what they’ll offer through a broker, because they’re not paying broker compensation on that deal. It doesn’t happen every time. But it happens often enough that anyone telling you “always switch, always negotiate, never just renew” hasn’t actually run the numbers on your file.
Why I still don’t mind
A rate quote without context is just a number. My job was never “get you the lowest number I can find” — it’s “get you the right outcome for your actual situation,” even when the right outcome is a phone call that ends with “stay put.” I’d rather earn the trust that gets referred to a friend than the commission that comes from steering someone somewhere they didn’t need to go.
What I’d tell you to actually check before you renew
Get the direct offer from your current lender in writing, not just verbally
Confirm it’s locked for the full term you want, not a teaser that reprices later
Ask what happens if you don’t take action by the renewal date — some lenders auto-renew you into a worse rate if you do nothing
Still worth a second opinion, even if you end up staying — the two minutes it takes to check costs you nothing, and sometimes the direct offer isn’t actually the best one
To be clear — both of these were straightforward renewals. No new funds, no debt consolidation, nothing that needed a full switch or new appraisal in the first place. If you’re pulling equity out, restructuring debt, or your current lender isn’t offering anything competitive, that’s a different conversation — and usually a very good reason to shop around.
If your renewal’s coming up, send it my way. Worst case, I tell you to do nothing and shake your hand on the way out.
I look forward to hearing from you in regard to your mortgage needs.
902-465-5533. I answer.
Patrick
p.s. Ready to see what you qualify for? Apply now
p.s. Prefer to talk it through first? Book a call
p.s. Licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI.
p.s. Grab the Craigburn mortgage app: Download here
Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone.
Questions about your renewal? Call 902-465-5533 or apply now.
https://craigburn.com/wp-content/uploads/2026/09/stayput-hero.jpg7841168Pat Sawlerhttps://craigburn.com/wp-content/uploads/2015/03/craigburn-logo2-e1426637601970.pngPat Sawler2026-09-21 13:15:562026-09-21 13:19:46The Best Mortgage Advice I Gave This Week Cost Me a Commission
Someone told me last week they’d found a renewal rate that seemed too good to pass up. A few days later, it was gone — not because they were too slow, but because something in their life quietly changed underneath it.
This happens more than people realize, and it’s worth understanding before you get attached to a number.
The Rate Isn’t Really About the Rate
A renewal offer from your current lender is usually priced for one very specific scenario: nothing changes. Same amount owing, same person (or people) on the mortgage, same amortization, same everything. The bank already knows you, already has your file, and isn’t re-underwriting anything — so they can afford to offer you a sharp number.
The second any one of those things shifts — you want to add a spouse to the mortgage, pull out some equity, extend your amortization, anything — you’re no longer getting a renewal. You’re applying for a brand new mortgage. And a brand new mortgage gets priced off a completely different sheet, with real underwriting behind it.
That’s not a penalty for changing your mind. It’s just a different product wearing the same name.
What Actually Triggers the Switch
The most common ones I see:
Adding someone to the mortgage — even if they’re already on title, adding them to the loan itself means they now have to qualify too
Taking equity out — for renovations, debt consolidation, anything — turns a straight renewal into a full refinance
Changing your amortization — stretching it out or shortening it up both take you out of “nothing changed” territory
Any one of these on its own is enough. If more than one applies, it doesn’t compound the damage — you’re already in full-application territory, so there’s no extra penalty for doing them together.
None of This Means Don’t Do It
I want to be clear about something: none of this means the life change isn’t worth it. Adding a spouse to a mortgage, or pulling equity for something that matters to you, can be exactly the right call. The point isn’t to talk you out of it — it’s to make sure you’re deciding with the real numbers in front of you, not the number that caught your eye before anything changed.
And sometimes there’s a cheaper way to get the outcome you actually want. If what you’re really after is peace of mind rather than a specific loan structure, there can be options — like mortgage protection insurance — that solve for the underlying worry without triggering a full new application at all.
The best move is always to ask before you assume. A five-minute conversation before you lock anything in can tell you exactly which bucket you land in, and what your real options look like from there.
I look forward to hearing from you in regard to your mortgage needs.
902-465-5533. I answer.
Patrick
p.s. Ready to start your application? Click here.
p.s. Prefer to talk first? Book a time with me here.
p.s. FSRA Principal Broker License #M23006699, Craigburn Capital, NS Brokerage 2025-3000179, NS Broker 2025-3000180.
p.s. Download the mortgage app here.
Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone.
Every private file I take on starts with some version of the same question: “Realistically, how fast can this actually close?”
Fair question. “Fast” gets thrown around a lot in this business, and it means different things depending on who’s saying it. So instead of a vague promise, here’s the actual math — real ranges, side by side.
The Bank Timeline
A conventional mortgage through a bank or A-lender, once your full application and documents are in, typically runs:
Underwriting and conditional approval: 5–10 business days
Appraisal (if required): adds 3–7 business days, sometimes more if the appraiser’s backlog is long
Final approval and document prep: another 5–7 business days
Total, start to close: usually 3–5 weeks, assuming nothing gets kicked back for more conditions
And that’s the good scenario — the one where your income is straightforward, the property is standard, and nothing needs a second look. Add a self-employed borrower, a rural property, or a file that needs to go back for clarification even once, and that timeline stretches fast.
The Private Timeline
Private financing isn’t fast because the underwriting is sloppy — it’s fast because the process is built around a different question. A bank asks “does this fit our program?” A private lender asks “does the security make sense?” That’s a shorter conversation.
Initial review and term sheet: often within 24–48 hours of a complete package
Appraisal: still required, but private appraisers tend to have shorter queues — 2–5 business days is common
Legal and funding: 5–10 business days once the lawyer has instructions
Total, start to close: 7–14 business days is realistic for a clean file. I’ve seen it move faster when everyone — borrower, lawyer, appraiser — is genuinely ready to move.
Why the Gap Is So Big
It’s not that private lenders cut corners. It’s that they’re solving a narrower problem. A bank is underwriting you — your income, your job history, your debt ratios, against a rigid program built for thousands of borrowers at once. A private lender is underwriting the property — is there enough equity here that the math works even in a worst-case scenario. Fewer variables, fewer conditions, fewer rounds of back-and-forth.
That’s also why private financing usually costs more. You’re not paying for less scrutiny — you’re paying for a process that isn’t waiting in line behind a thousand other files.
When the Speed Actually Matters
This isn’t really an either-or decision most of the time. It matters when:
You’re competing on an offer and a fast, certain close is a negotiating advantage
A renewal or default situation has a real deadline attached to it
If none of those apply, the bank route is usually still the better economics. Private financing earns its cost when time itself has a dollar value attached to it — and in those situations, the gap between 3–5 weeks and 7–14 days isn’t just a convenience, it’s the difference between the deal happening or not.
If you’re staring down a timeline that a bank can’t hit, let’s talk about what’s actually realistic for your situation — not a guess, a real number based on your file.
I look forward to hearing from you in regard to your mortgage needs.
902-465-5533. I answer.
Patrick
p.s. You can start an application anytime through our secure portal: https://craigburn-capital.mtg-app.com
p.s. Prefer to talk first? Book a time here: [scheduling link]
p.s. Licensed in Nova Scotia and Ontario — NS Brokerage 2025-3000179, NS Broker 2025-3000180, ON M23006699
p.s. Download the mortgage app: [app download link]
Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone.
Questions about your timeline? Call 902-465-5533 or start your application at craigburn-capital.mtg-app.com
https://craigburn.com/wp-content/uploads/2026/09/howfastisfast-hero.jpg7841168Pat Sawlerhttps://craigburn.com/wp-content/uploads/2015/03/craigburn-logo2-e1426637601970.pngPat Sawler2026-09-17 17:06:162026-09-17 17:07:02How Fast Is Fast?
“My tax assessment says my house is worth $410,000 — why is the bank only working with $365,000?” I get some version of this question almost every week, and it comes down to one thing: your property assessment and a lender’s appraisal are answering two completely different questions.
Your tax assessment exists to fairly split up the municipal tax bill across the province — not to tell you what your house would sell for today. It’s calculated by computer using sales data and general characteristics, nobody’s walked through your kitchen, and it’s already up to a year out of date by the time you read it (your 2026 notice reflects January 1, 2025 values). On top of that, Nova Scotia’s Capped Assessment Program means the number on your tax bill is often a third figure entirely, capped well below even that already-outdated market estimate.
A mortgage appraisal is a licensed, AIC-designated appraiser’s opinion of your property’s value, right now, based on an actual inspection and genuinely comparable recent sales — with real professional liability behind the number. That’s exactly why a lender will use it, and won’t use your tax assessment.
The gap between the two can easily run 20–40% in a fast-moving market. Ontario homeowners have it even more extreme: MPAC assessments are still legally frozen to a January 1, 2016 valuation date for 2026 — a full decade that isn’t reflected in the number at all.
The takeaway: keep your assessment notice for tax purposes and to catch errors (wrong square footage, a basement counted as finished that isn’t), but don’t use it to set a sale price, argue with an appraisal, or estimate your available equity. For that, the only number that matters is the one an appraiser puts their license behind.
Want the full breakdown — including who’s actually qualified to give you which number, and what to do if an appraisal comes back lower than expected? Read the full article on MortgageClarity.ai →
I look forward to hearing from you in regard to your mortgage needs.
902-465-5533. I answer.
Patrick
p.s— You can click on this link to start the process whenever you are ready. Schedule your meeting with me here.
p.s.s— I should tell you that I am licensed in Nova Scotia Brokerage (2025-3000179) Broker (2025-3000180), Ontario (M23006699).
p.s.s.s— You can download my new mortgage app here
Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone.
Ready to have a real conversation? Call 902-465-5533 or start your application here.
https://craigburn.com/wp-content/uploads/2026/08/assessed-vs-appraised-value-hero.jpg7841168Pat Sawlerhttps://craigburn.com/wp-content/uploads/2015/03/craigburn-logo2-e1426637601970.pngPat Sawler2026-08-31 12:07:002026-08-05 20:40:25Two Appraisals Walk Into a Bank… Only One Gets You a Mortgage
Investing in real estate, particularly apartment buildings, can be a lucrative venture if done correctly. However, not all properties are created equal, and determining whether a specific apartment building is a wise investment requires careful analysis. One of the most critical metrics used by real estate investors to evaluate the profitability of a property is the capitalization rate, or cap rate. In this blog post, we’ll break down what cap rate is, how to calculate it, and how to use it to make informed investment decisions.
What Is Cap Rate?
The capitalization rate, or cap rate, is a fundamental metric in real estate investing that measures the potential return on an investment property. It is expressed as a percentage and represents the relationship between a property’s net operating income (NOI) and its market value or purchase price. Essentially, the cap rate helps investors assess the profitability and risk of a property without factoring in financing methods like mortgages.
Cap rate is particularly useful for comparing multiple investment opportunities. A higher cap rate typically indicates a higher potential return but may also come with higher risk. Conversely, a lower cap rate suggests a lower return but often corresponds to a more stable and less risky investment.
How to Calculate Cap Rate
The formula for calculating cap rate is straightforward:
Cap Rate = (Net Operating Income / Property Value) × 100
Let’s break down the components of this formula:
Net Operating Income (NOI): NOI is the annual income generated by the property after subtracting all operating expenses but before accounting for mortgage payments, taxes, and depreciation. Operating expenses include property management fees, maintenance costs, insurance, utilities, and property taxes. NOI = Total Rental Income – Operating Expenses
Property Value: This is the current market value or purchase price of the property. If you’re evaluating a property listed for sale, the purchase price is typically used. If you’re analyzing an existing investment, the current market value can be used instead.
Example Calculation
Let’s say you’re considering purchasing an apartment building with the following details:
Total Rental Income: $500,000 per year
Operating Expenses: $200,000 per year
Purchase Price: $4,000,000
First, calculate the NOI: NOI = $500,000 – $200,000 = $300,000
Next, plug the numbers into the cap rate formula: Cap Rate = ($300,000 / $4,000,000) × 100 = 7.5%
In this example, the cap rate is 7.5%, which means the property is expected to generate a 7.5% return on investment based on its current income and price.
Where Does That Fit? Cap Rate Benchmarks by Property Type (2026)
Property Type
Typical Cap Rate Range
Notes
Multi-Family (major metros)
4.5% – 4.8%
Most compressed asset class — strong rental demand keeps rates tight
Industrial
5.7% – 6.3%
Cooled from the 2020–2022 e-commerce boom, still tight in major logistics corridors
Retail
5.9% – 6.6%
Stabilizing after years of “death of retail” headlines
Office
6.8% – 8.9%
Downtown Class AA–B — compressing gradually as leasing fundamentals improve
All-Property National Average
6.58%
Source: CBRE Q2 2026 Canadian Cap Rate Report
A quick honest note here: these figures reflect national and major-metro benchmarks — Toronto, Vancouver, and similar markets. Halifax and Atlantic Canada see far fewer commercial transactions, so local cap rates often sit outside these ranges entirely, usually wider. If you’re evaluating a property here, a national average is a starting reference point, not a verdict — talk to a local broker or appraiser (or me) for something grounded in real comparables.
How to Use Cap Rate to Evaluate an Apartment Building
Now that you know how to calculate cap rate, let’s discuss how to use it to determine if an apartment building is a wise investment.
1. Compare Cap Rates Across Properties
This is easiest to see side by side:
Property A
Property B
Rental Income
$500,000
$650,000
Operating Expenses
$200,000
$310,000
NOI
$300,000
$340,000
Purchase Price
$4,000,000
$4,000,000
Cap Rate
7.5%
8.5%
Property B looks like the better deal on paper — but a higher cap rate isn’t automatically the win. If Property B’s higher NOI comes from a riskier tenant mix, shorter leases, or deferred maintenance that’s about to catch up with you, that extra percentage point is compensation for real risk, not free money.
2. Assess Market Trends
Cap rates vary by location and market conditions. In high-demand areas with lower risk, such as prime urban locations, cap rates tend to be lower because investors are willing to accept lower returns for the stability and appreciation potential. In contrast, properties in less desirable areas may have higher cap rates to compensate for the increased risk. Understanding the average cap rate for your target market will help you determine whether a specific property is priced competitively.
3. Evaluate Risk and Return
A higher cap rate may seem attractive, but it often comes with higher risk. For example, a property with a 10% cap rate might be located in an area with declining demand or require significant repairs. On the other hand, a property with a 5% cap rate might be in a stable, high-growth area with lower risk. As an investor, you need to balance your desired return with your risk tolerance.
4. Determine if the Property Meets Your Investment Goals
Your ideal cap rate will depend on your investment strategy. If you’re looking for steady cash flow and long-term appreciation, a lower cap rate in a stable market might be suitable. If you’re focused on maximizing short-term returns and are willing to take on more risk, a higher cap rate property might be a better fit.
5. Use Cap Rate to Estimate Property Value
Cap rate can also be used to estimate the value of a property based on its income potential. If you know the NOI of a property and the average cap rate for similar properties in the area, you can calculate the property’s estimated value using the following formula: Property Value = NOI / Cap Rate
For example, if a property has an NOI of $200,000 and the average cap rate for similar properties is 6%, the estimated value would be: Property Value = $200,000 / 0.06 = $3,333,333
This calculation can help you determine if a property is overpriced or a good deal.
Limitations of Cap Rate
While cap rate is a valuable tool, it’s important to recognize its limitations:
It Doesn’t Account for Financing: Cap rate calculations don’t include mortgage payments or other financing costs, so they don’t reflect your actual cash flow.
It’s a Snapshot in Time: Cap rate is based on current income and expenses, which may change over time due to market conditions, rent increases, or unexpected expenses.
It Doesn’t Consider Appreciation: Cap rate focuses on income, not the potential for property value appreciation, which can be a significant source of return in high-growth markets.
Conclusion: Is the Apartment Building a Wise Investment?
Cap rate is a powerful tool for evaluating the potential return and risk of an apartment building investment. By calculating the cap rate and comparing it to similar properties in the market, you can gain valuable insights into whether a property is a wise investment. However, cap rate should not be the only factor you consider. Be sure to also evaluate the property’s location, condition, growth potential, and alignment with your investment goals.
If you’re new to real estate investing or unsure how to apply cap rate to your specific situation, working with an experienced real estate professional can make all the difference. As a seasoned broker with a deep understanding of market trends and investment strategies, I can help you analyze properties, calculate cap rates, and make informed decisions that align with your financial goals. Whether you’re looking for a high-cash-flow property or a long-term appreciation play, I’m here to guide you every step of the way.
Ready to take the next step in your real estate investment journey? Contact me today to discuss your goals and find the perfect apartment building for your portfolio. Together, we can turn your investment dreams into reality.
I look forward to hearing from you in regard to your mortgage needs.
Patrick
p.s- You can click on this link to start the process whenever you are ready. Schedule your meeting with me here.
Don’t miss out on this opportunity to secure the best financing terms for your next multi-unit development. Contact me today!
What is a good cap rate for commercial real estate?
It depends on the property type and market. Multi-family properties in major metros often see 4.5%–4.8%, industrial 5.7%–6.3%, retail 5.9%–6.6%, and downtown office 6.8%–8.9%. The 2026 national average across all property types sits around 6.58%, per CBRE’s Q2 2026 report — though Atlantic Canada properties often trade outside these ranges given fewer local transactions.
How do you calculate cap rate?
Divide a property’s net operating income (NOI) by its purchase price or current market value, then multiply by 100. For example, a property with $300,000 NOI and a $4,000,000 purchase price has a 7.5% cap rate.
What’s the difference between cap rate and ROI?
Cap rate measures a property’s return based purely on its income relative to its value, without factoring in financing. ROI (return on investment) typically accounts for how the property was financed, including mortgage payments, making it a more complete picture of your actual return once leverage is considered.
Do cap rates in Halifax differ from major markets like Toronto?
Often, yes. National cap rate benchmarks reflect major-metro transaction volume in markets like Toronto and Vancouver. Halifax and Atlantic Canada see far fewer commercial transactions, so local cap rates frequently sit outside these national ranges, usually wider.
Can you use cap rate to estimate a property’s value?
Yes — by rearranging the formula: Property Value = NOI ÷ Cap Rate. For example, a property generating $200,000 in NOI at a 6% area cap rate would be valued at roughly $3,333,333.
https://craigburn.com/wp-content/uploads/2025/03/OIP-1.jpg201302Pat Sawlerhttps://craigburn.com/wp-content/uploads/2015/03/craigburn-logo2-e1426637601970.pngPat Sawler2026-08-17 13:02:542026-08-17 13:02:56How to Calculate Cap Rate
What Waiting 10 Years to Buy Actually Costs You — The Real Numbers From Toronto to Halifax
July 22, 2026
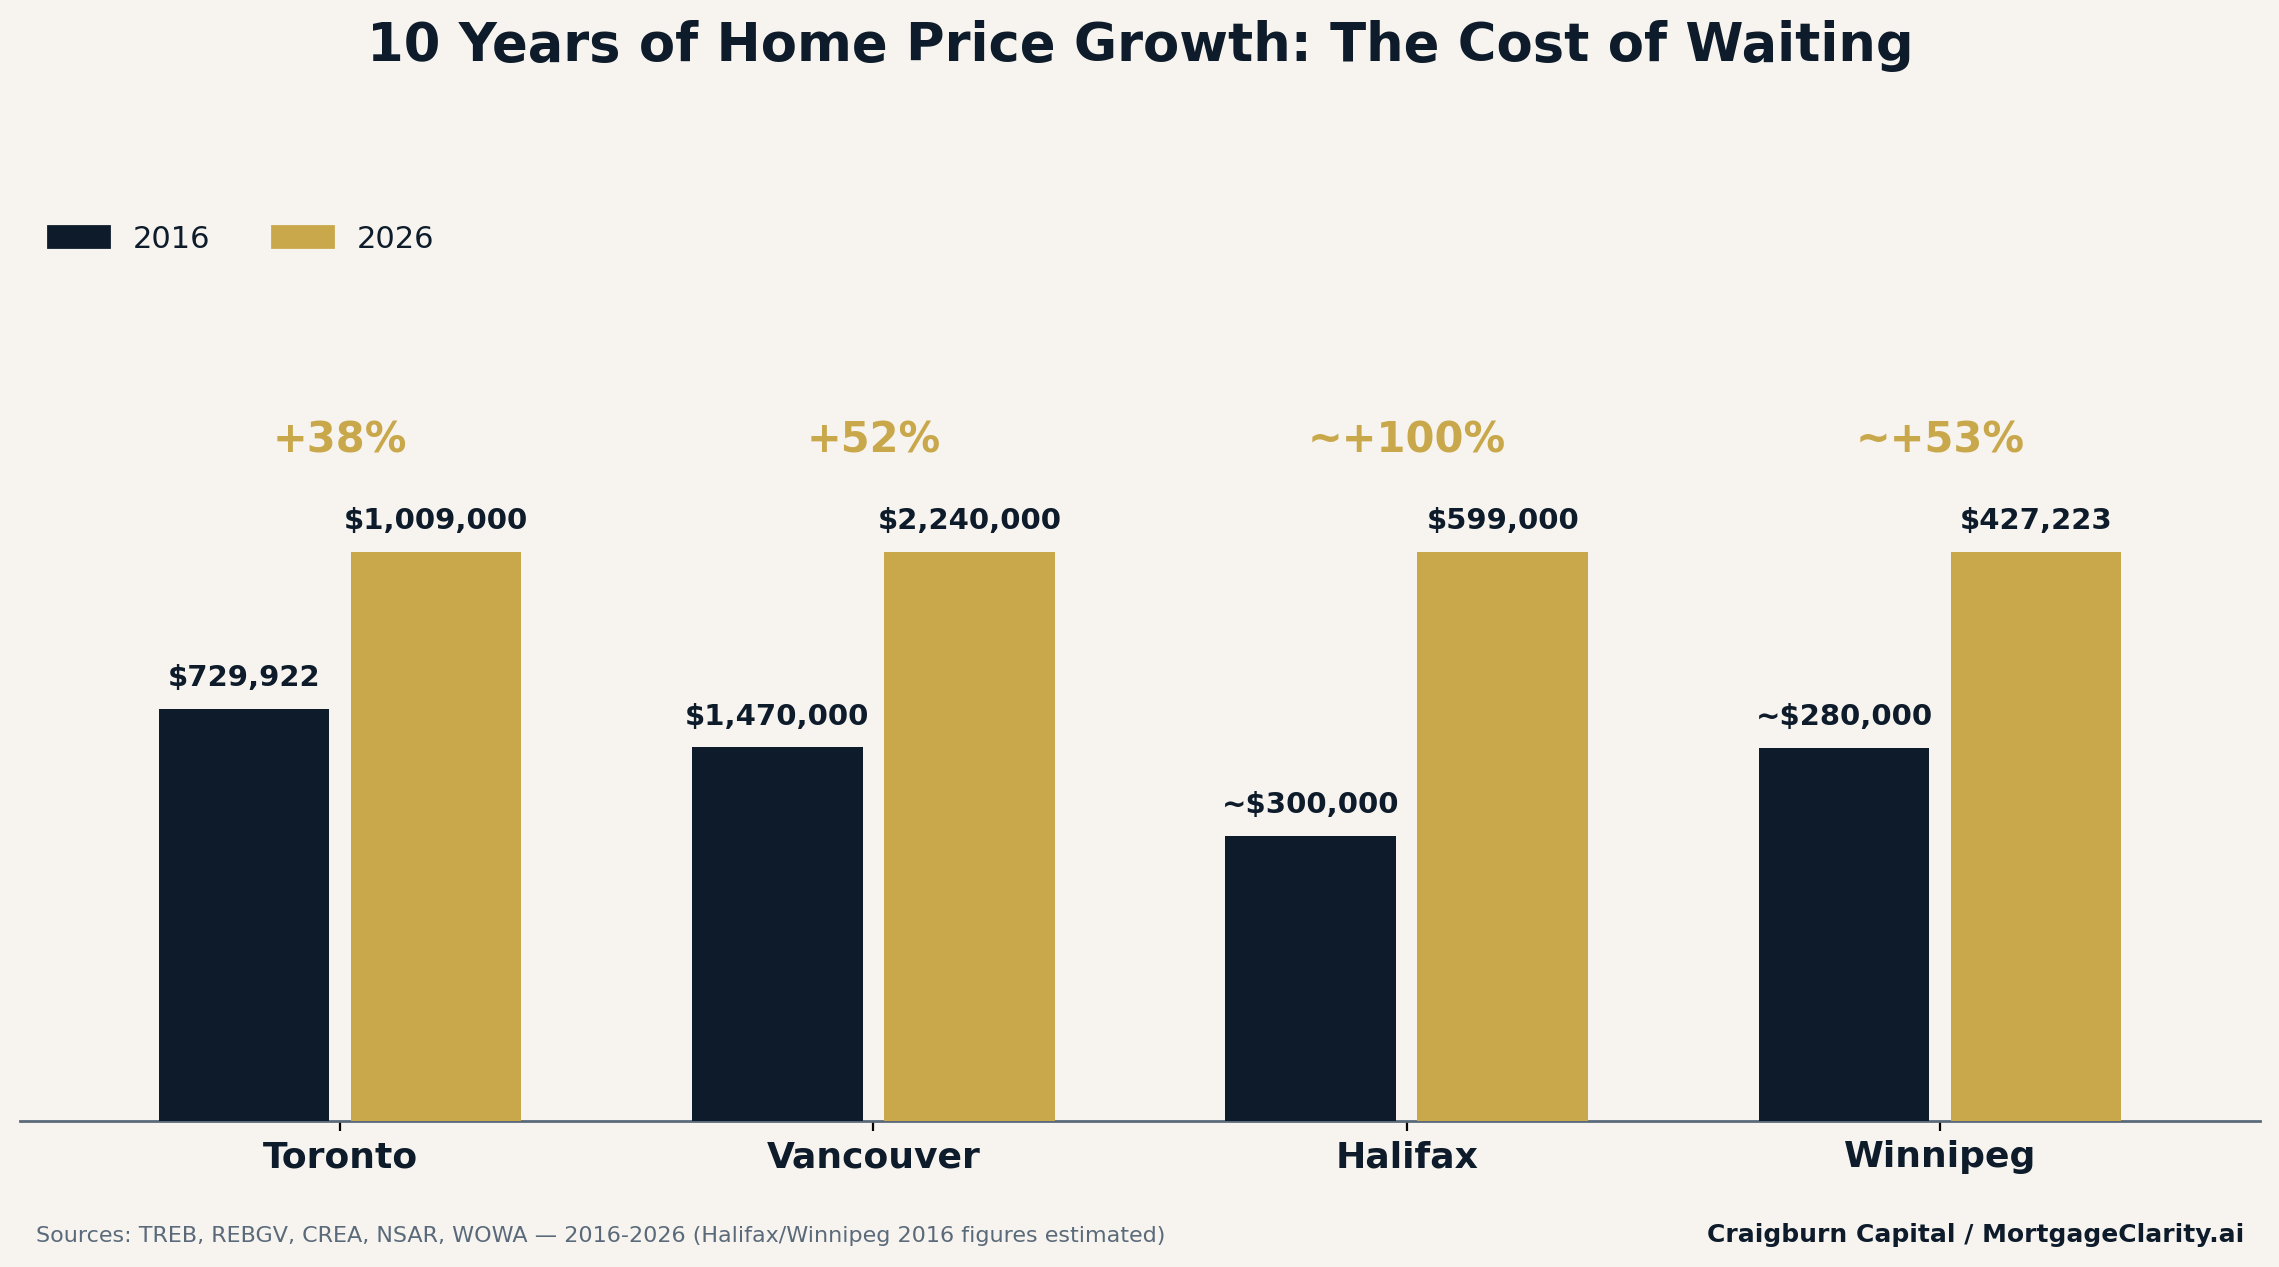
Quick answer: “I’ll buy once I’ve saved more” sounds responsible — but over the past decade, home prices in every major Canadian market grew faster than most people can realistically save. Halifax prices have roughly doubled since 2016. The person who bought a decade ago with a smaller down payment is often further ahead today than the person who spent that decade saving for a bigger one.
Quick note on where I’m coming from: I’m a mortgage broker, not a rental investment advisor. This isn’t about renting vs. owning — it’s about what actually happens when you wait to buy.
Here’s what home prices actually did over the last 10 years:
City
2016
2026
10-Yr Growth
Toronto
$729,922
$1,009,000
+38%
Vancouver (detached)
$1,470,000
$2,240,000
+52%
Halifax (est.)
~$300,000
$599,000
~+100%
Winnipeg (est.)
~$280,000
$427,223
~+53%
Sources: TREB/TRREB, REBGV, CREA/NSAR, WOWA, CREA/WRREB. Halifax/Winnipeg 2016 figures are estimated. Past appreciation doesn’t guarantee future performance.
Halifax roughly doubling in 10 years should get your attention if you’re local — that’s not a Toronto/Vancouver story, that’s ours.
The math that matters: Someone who bought in Halifax in 2016 with $40,000 down (about 13%) is sitting on a home now worth roughly double. Someone who spent that decade saving instead — even an extra $25,000 on top of their original $40,000 — now has $65,000 against a home that costs roughly double what it used to. That’s a smaller effective down payment than they started with, despite years of real saving.
This isn’t a “buy no matter what” post — there are good reasons to wait if you’re genuinely not ready. But “I’m waiting to save more” and “I’m chasing a number the market keeps moving on me” are two different things, and it’s worth knowing which one you’re actually doing.
https://craigburn.com/wp-content/uploads/2026/07/gzi0r.jpg8321248Pat Sawlerhttps://craigburn.com/wp-content/uploads/2015/03/craigburn-logo2-e1426637601970.pngPat Sawler2026-07-24 12:07:002026-07-22 14:56:43What waiting 10 years to Buy Actually Cost You
A private mortgage is a loan from a non-bank lender, usually secured against a property’s equity rather than a borrower’s income or credit history. People typically need one when a bank says no — credit issues, foreign or irregular income, self-employment without conventional documentation, or a property that’s hard to finance conventionally.
Here’s the part almost nobody explains clearly: even once you know you need to look outside a bank, where your property sits on a map can close doors that have nothing to do with your income or credit score at all.
Alt-B lenders exist specifically to say yes when a bank says no — but many only lend in populated, marketable centres: HRM core communities, Truro, Sydney, the Annapolis Valley. A genuinely rural Nova Scotia property can be excluded from that entire category, regardless of how strong the file otherwise looks.
So what works if you’re rural? This is where a private mortgage earns its reputation as the flexible option — most private lenders don’t carry the same geographic restrictions. But they come with a trade-off people are often uneasy about: they’re usually interest-only, so the balance doesn’t shrink on its own the way a bank mortgage would.
Here’s what’s worth knowing: that doesn’t have to mean pure interest for the whole term. Many private lenders will structure a mortgage to allow extra payments toward principal whenever you’re able to make them, with the remaining balance due at term’s end — a real way to chip away at what you owe, on your own timeline.
Read the full breakdown — including a side-by-side comparison of how bank, Alt-B, and private lending actually differ — on [MortgageClarity.ai].
Thinking through your options? I’d be glad to walk through what’s realistic for your specific property and situation.
I look forward to hearing from you in regard to your mortgage needs.
Patrick
p.s- You can click on this link to start the process whenever you are ready. Schedule your meeting with me here.
p.s.s- I should tell you that I am licensed in Nova Scotia Brokerage (2025-3000179) Broker (2025-3000180), Ontario(M23006699).
Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone.
Ready to have a real conversation? Call 902-612-2688 or start your application here
Can I get an Alt-B mortgage on a rural property in Nova Scotia?
Usually not. Most Alt-B lenders only serve populated, marketable centres — HRM core communities, Truro, Sydney, and the Annapolis Valley. A genuinely rural property is often excluded from that category entirely, regardless of how strong the rest of the file looks.
Are private mortgages always interest-only?
Typically, yes — but not always in practice. Many private lenders will structure a mortgage to allow extra payments toward the principal whenever you’re able to make them, with the remaining balance due at the end of the term. That gives you a real way to pay down what you owe, even without qualifying for a conventional amortizing product.
https://craigburn.com/wp-content/uploads/2026/07/Recalculating.webp180284Pat Sawlerhttps://craigburn.com/wp-content/uploads/2015/03/craigburn-logo2-e1426637601970.pngPat Sawler2026-07-13 12:07:002026-07-12 15:44:55Private Mortgages in Nova Scotia: Why Your Address Can Matter More Than Your Credit Score
You know that feeling when someone goes quiet on you — no bad news, just… silence? That’s basically what’s happening in the Nova Scotia housing market right now. Except it’s not people ghosting each other. It’s buyers ghosting sellers.
A lot of sellers are reading that silence as a crash. It’s not. Engel & Völkers just released their Q2 2026 numbers, and here’s the real story:
HRM: Median price $590,000 (down just 1.7%), but homes are sitting 32 days on average — up 14.3% from last year
South Shore: Median price $394,000 (actually up 2.3%), with days on market jumping 22.6% to 65 days
Annapolis Valley: Median price $420,000 — up 9.1%, the biggest gain of the three — even as sales volume dipped 11%
Notice what’s missing from all three: prices falling off a cliff. What’s actually happening is buyers have more time, more choice, and more room to negotiate than they’ve had in years.
If you’re hunting for your next home, this is good news. You’re not the only one feeling the pressure anymore — sellers are too. That means more room to think, more listings to compare, and more willingness on the seller’s side to talk price, closing date, and conditions.
The one thing that hasn’t changed: get your financing sorted before you fall in love with a place. A slower market gives you breathing room, but a pre-approval still means you can move fast and confidently the moment the right home shows up.
Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone.
Ready to have a real conversation? Call 902-612-2688 or start your application here
Source: Engel & Völkers Quarterly Market Statistics, April/May/June 2026.
https://craigburn.com/wp-content/uploads/2026/07/ghosting-illustration-v3.jpg800800Pat Sawlerhttps://craigburn.com/wp-content/uploads/2015/03/craigburn-logo2-e1426637601970.pngPat Sawler2026-07-10 12:06:002026-07-09 12:37:42The Market Didn’t Crash. It Just Started Ghosting Sellers.
Before the sun’s up, before the day has any opinions about how it should go, I meditate, walk my dog, work out, and study French. Same order, most mornings. Each one small enough that skipping feels pointless to bother.
I’ve been running for years, and I hear the same mistake from almost every beginner: they want to run. But most people who start by running quit within weeks — sore, frustrated, convinced they’re “just not built for it.” The problem is never that they can’t run. It’s that they skipped the boring prerequisite: time on your feet, building the aerobic base before adding intensity.
Erling Haaland is the extreme version of this playing out on TV right now — fastest player in World Cup history to 60 international goals, and it’s not because of one great game. It’s because he’s boringly disciplined about the parts nobody films.
Your mortgage works exactly the same way. People want the approval, the good rate, the big result — without the boring base-building underneath it: on-time payments, stacked month after month, that nobody notices until eighteen months in when the credit score and the approval odds have quietly transformed.
Read the full post — including the Myth vs. Fact breakdown — on MortgageClarity.ai
I look forward to hearing from you in regard to your mortgage needs.
Patrick
p.s- You can click on this link to start the process whenever you are ready. Schedule your meeting with me here.
p.s.s- I should tell you that I am licensed in Nova Scotia Brokerage (2025-3000179) Broker (2025-3000180),and Ontario(M23006699).
Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone.
Ready to have a real conversation? Call 902-612-2688 or start your application here
https://craigburn.com/wp-content/uploads/2026/07/beginner-runners-beginner-savers.jpg8401600Pat Sawlerhttps://craigburn.com/wp-content/uploads/2015/03/craigburn-logo2-e1426637601970.pngPat Sawler2026-07-08 12:05:362026-07-08 12:05:48Why Beginner Runners (and Beginner Savers) Make the Exact Same Mistake