Renewal Day Is the One Day Extra Payments Don’t Cost You a Penalty
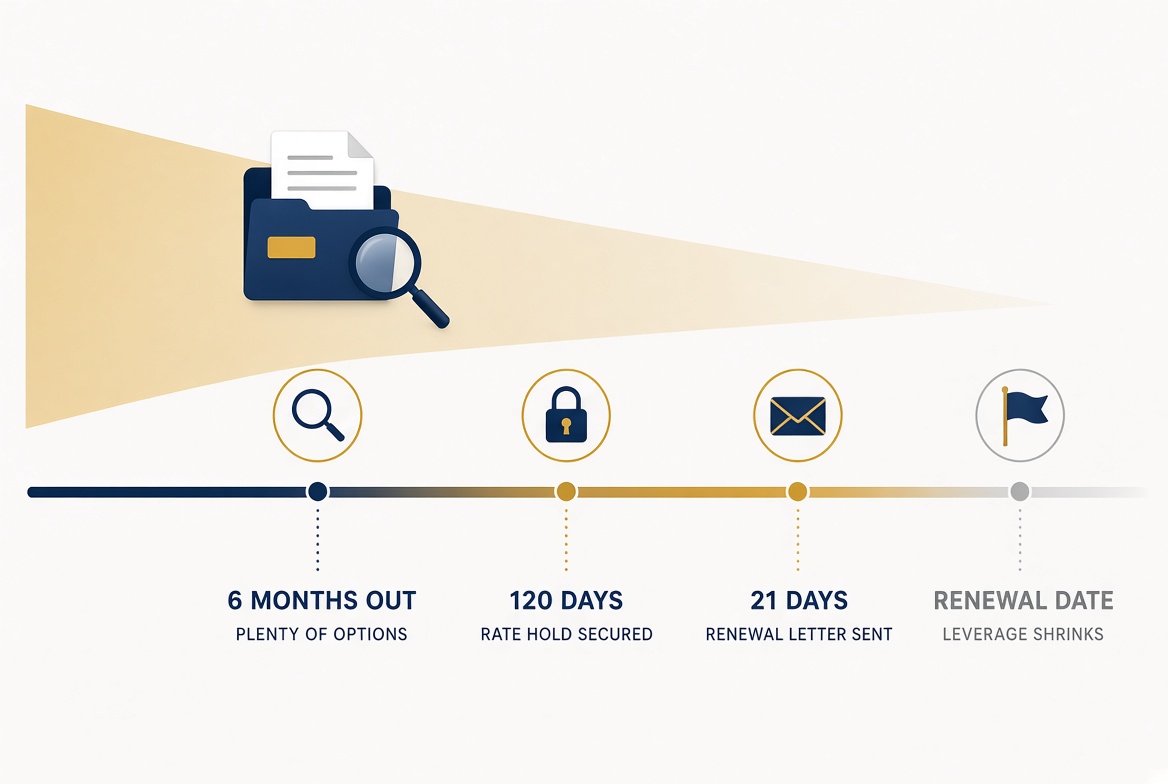
Can you pay down your mortgage at renewal without a penalty? Yes, in most cases. When your mortgage term ends, the cap on extra payments generally stops applying, so renewal is usually the one day you can pay down any amount without a prepayment penalty. Mid-term, you can only pay extra up to the limit in your contract. At maturity, that limit is generally gone.
Your contract has the final word, so confirm how your lender handles it before your renewal date. Here is how it works and what to ask.
Can you pay down your mortgage at renewal without a penalty?
Usually, yes. The Financial Consumer Agency of Canada explains that a prepayment penalty can apply when you pay down or pay off a mortgage before the end of your term, and that waiting until the end of the term is one way to avoid it. Most lenders treat the maturity date as the point where you can put extra money toward the balance without that penalty.
It is worth confirming with your lender, because the mechanics vary. Some let you make the payment on the maturity date itself, and others want it arranged when you sign the renewal.
Why is the end of the term different from the rest of the mortgage?
During the term, most closed mortgages come with prepayment privileges: a yearly allowance you can put toward the balance, usually a percentage of the original mortgage amount, such as lump sums or higher regular payments. Go over that allowance and you generally pay a penalty, often the greater of three months’ interest or the interest rate differential.
That penalty exists to make up for the interest the lender expected to earn through the rest of your term. At maturity there is no rest of the term, so there is nothing left to make up. That is why renewal is the moment the cap generally disappears.
How much difference can a lump sum at renewal make?
Here is a simple example. Say you are renewing with a $400,000 balance and you have $20,000 in savings you are comfortable putting toward it. You renew on $380,000 instead. At an illustrative 5% rate, that is roughly $1,000 less interest in the first year, and more over the term. If you keep your payment the same, the mortgage is paid off sooner too.
That is only an example, and your numbers will differ. You can run your own with the mortgage payment calculator. Rates have been moving, so it also helps to know where you stand before the letter arrives. I wrote about what the latest Bank of Canada move means for borrowers in this post on the rate hike.
What should you ask your lender before the renewal date?
- How much can I pay at maturity without a penalty? Get the answer in writing if you can.
- Do I pay on the maturity date, or when I sign the renewal? The timing can change how the lump sum is applied.
- Will my payment drop, or stay the same and shorten the amortization? Pick the one you want before you sign.
- Is there any fee for processing the payment? There usually is not, but ask.
Does a lump sum still work if you switch lenders at renewal?
Generally, yes. Switching lenders at maturity usually does not trigger a prepayment penalty either, and a paydown simply means the new mortgage is for a smaller balance. Either way, it is worth deciding the paydown before you compare offers, so every lender is pricing the same amount.
Should you use savings to pay down the mortgage?
That is a personal decision, and it is not right for everyone. A mortgage paydown is hard to undo, so many people keep an emergency fund first. If you carry higher-interest debt, such as a credit card balance, that usually costs more than your mortgage, and many people deal with it before they pay down the mortgage. I can show you what each option does to the numbers, and the choice stays yours.
Who compares the renewal options for me?
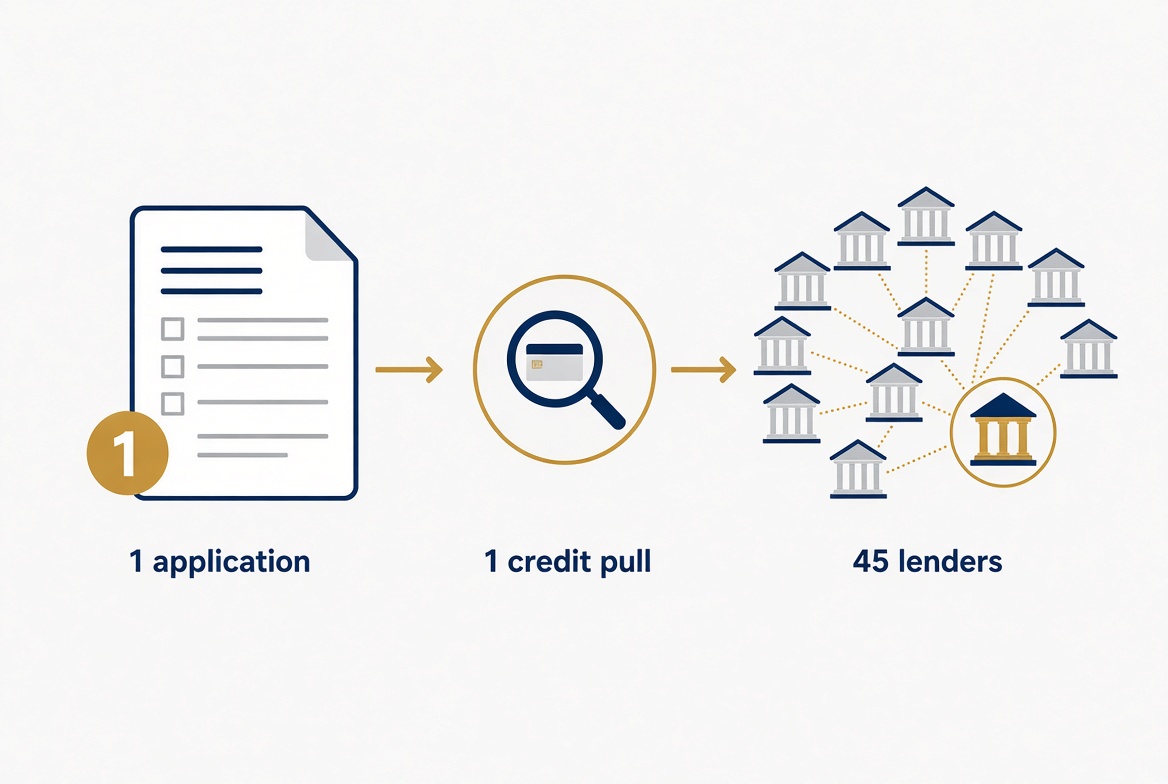
I do. You send me one application, and I look at your current lender’s renewal offer next to what 45 lenders would do on the same file, including how each one treats lump sums and prepayment privileges going forward. You get one clear comparison, so the paydown decision is made with real numbers.
Frequently Asked Questions
Can you pay down your mortgage at renewal without a penalty?
Usually yes. A prepayment penalty is meant to cover the interest a lender expected to earn over the rest of your term, and at maturity there is no rest of the term. Most lenders let you pay down any amount when the term ends, but confirm how yours handles it before the renewal date.
How much can I pay down at renewal?
In most cases there is no cap at maturity, so the limit is how much cash you want to put in. Mid-term, extra payments are usually capped by the prepayment privileges in your contract, and going over the cap triggers a penalty.
What is the penalty for paying extra during the term?
If you go over the prepayment limit in your contract, the penalty is usually the greater of three months’ interest or the interest rate differential. Your contract sets the exact limit and the penalty formula.
Will my payment go down if I pay down my mortgage at renewal?
It depends on the lender and the option you choose. Some lenders recalculate your payment on the lower balance, and others keep the payment the same so the mortgage is paid off sooner. Ask for the option you want before you sign the renewal.
This post is general information, not legal or financial advice. Prepayment terms, limits and penalties vary by lender and by contract, so confirm the details with your lender. All financing is subject to lender approval.
Renewal coming up? Send me your application and I will compare your options, including a paydown.
I look forward to hearing from you in regard to your mortgage needs.
902-465-5533. I answer.
Patrick
p.s. Ready to start? Apply here: https://craigburn-capital.mtg-app.com
p.s. Prefer to talk it through first? Book a time with me here: Schedule a call
p.s. FSRA Principal Broker License #M23006699, Craigburn Capital. NS Brokerage 2026-3000179, NS Broker 2026-3000180.
p.s. Get the Craigburn mortgage app: https://craigburn-capital.mtg-app.com
Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone. Service aussi disponible en français.
Call 902-465-5533 or start your application today.