
“Just Add Me to the Mortgage” Is Never Just Anything
It comes up constantly — a spouse, partner, or family member wants to be added to an existing mortgage, and it’s framed as a quick administrative fix. A form, a signature, done. That’s not how it works, and treating it that way can catch people off guard at the worst possible moment.
What people assume happens
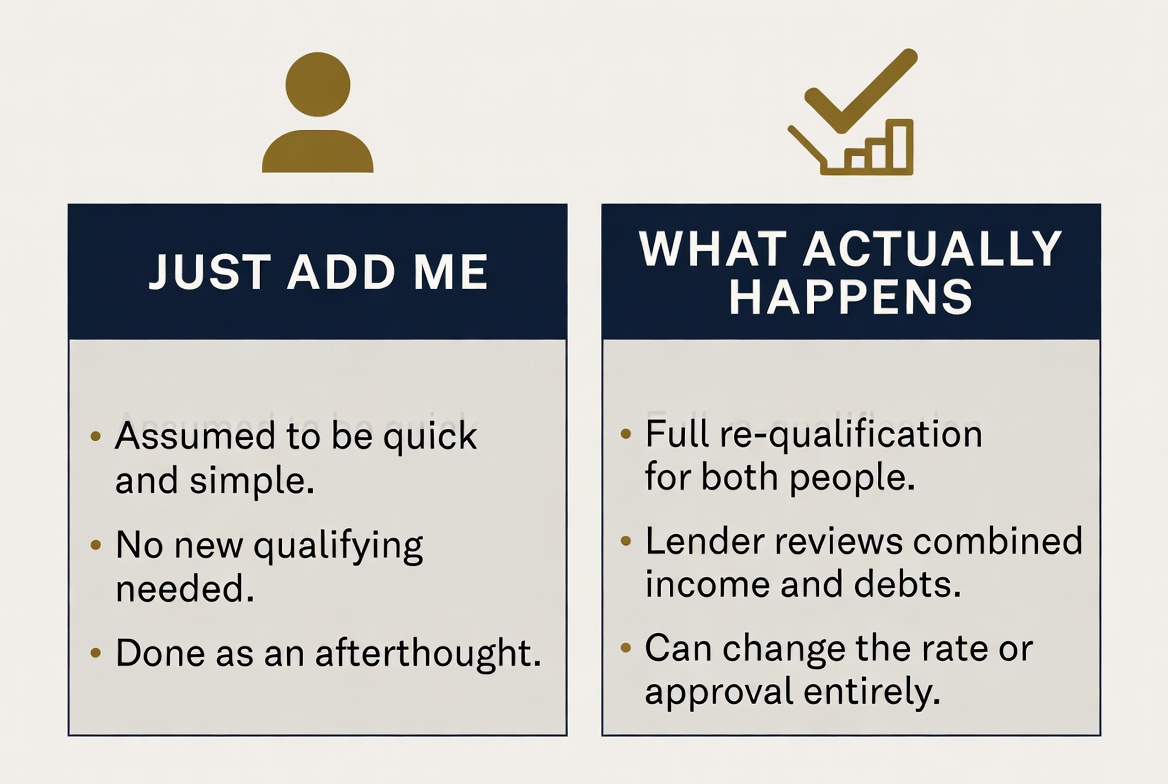
The common assumption is that adding someone to a mortgage is like adding a name to a lease or a bank account — a formality, no real underwriting involved, done as an afterthought once the decision’s already been made.
What actually happens
Adding someone to an existing mortgage isn’t a name change — it’s a new qualifying event. The lender doesn’t just add a signature; they re-underwrite the file with both people’s combined income, debts, and credit. That can change the mortgage in ways nobody expected going in.
Adding a name to a mortgage means adding a whole person’s financial picture to the file. The lender treats it as a new decision, not a formality.
Why this can change the outcome entirely
If the person being added has weaker credit, inconsistent income, or existing debt, the combined file can qualify for less than the original mortgage holder could on their own — or trigger a different rate altogether. In some cases, it can mean the mortgage no longer qualifies as-is, forcing a restructure nobody was expecting.
On the flip side, if the person being added strengthens the file — stronger income, better credit — it can actually open up better terms than what’s currently in place. The point isn’t that it’s always bad news; it’s that it’s never automatic, and assuming it is can lead to an unpleasant surprise.
What to actually do before you request it
Treat “adding someone to the mortgage” as its own application, not a footnote to an existing one. Both people’s full financial picture should go through the same conversation a fresh mortgage would — before you assume the outcome, not after you’re told what it actually is.
Adding someone to a mortgage isn’t as simple as it sounds. Call 902-465-5533 — I answer.