Tag Archive for: commercial mortgage broker Nova Scotia

Blanket mortgage for rental properties

A blanket mortgage rolls several rental properties into a single commercial loan — one rate, one renewal date, one lender relationship — instead of juggling three, five, or ten separate residential mortgages that all renew on different timelines.

I had a landlord call me in a bit of a panic a few months back. He owned four rental properties, each with its own mortgage, each with a different bank, each renewing on a different month of the year. Every renewal was its own fire drill — new paperwork, new rate negotiation, new stress, four times a year instead of once. He’d never heard there was a different way to do it.

How does a blanket mortgage actually work?

Instead of underwriting each property as its own deal, a lender looks at the portfolio as a whole — the combined rental income, the combined expenses, the combined equity — and finances it as one commercial file. You qualify as a package, not as four separate fights for four separate approvals.

Why would a landlord want one mortgage instead of several?

A few reasons come up most often:

  • One renewal date a year instead of four scattered through it
  • Often better overall terms when a lender sees the full portfolio and its blended risk, rather than underwriting each property in isolation
  • Less paperwork and less time re-proving income every time one property comes up for renewal
  • Easier to pull equity across the portfolio to fund the next purchase, instead of refinancing one property at a time
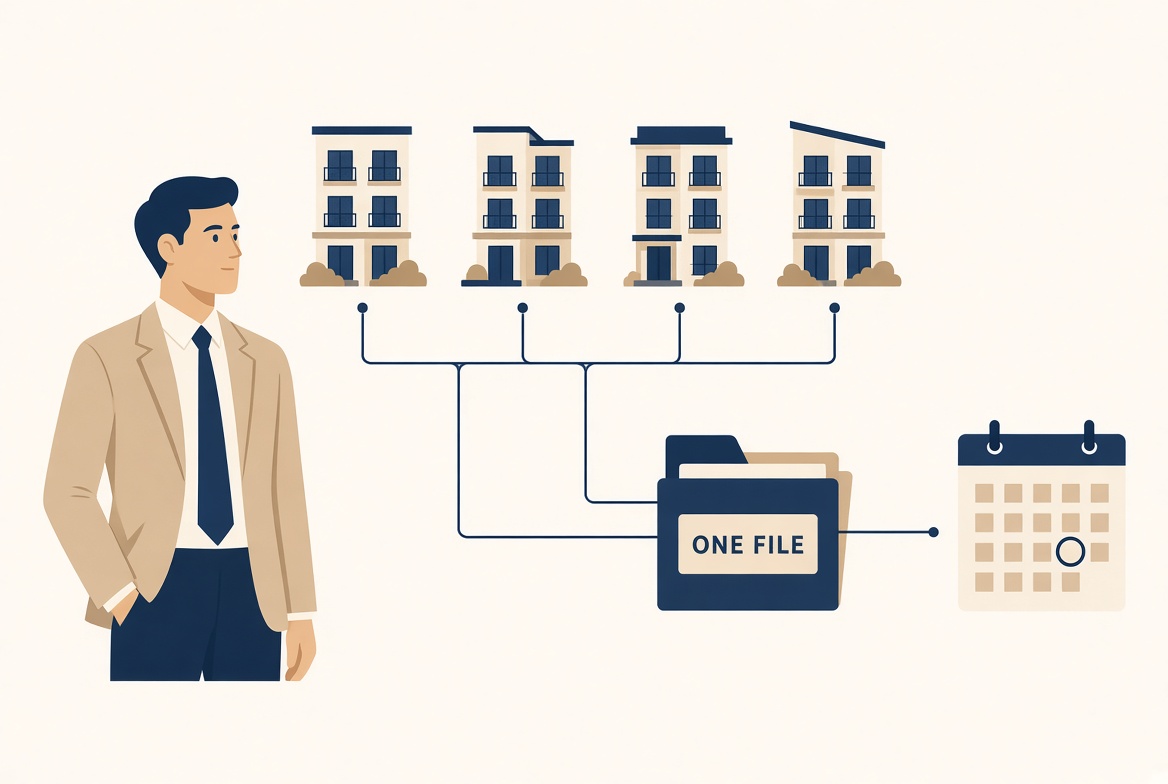
One commercial mortgage file replacing four separate rental property renewal dates

Is a blanket mortgage the same as a regular commercial mortgage?

Not exactly. A blanket mortgage is a structure — multiple properties under one loan — that can sit inside either a residential or commercial lending framework depending on the number of doors, the property types, and the lender. Every lender treats that threshold a little differently, which is exactly the kind of detail worth walking through before assuming you know which category you fall into.

What do lenders look at to qualify a blanket mortgage?

Mostly the properties themselves — the combined rental income against the combined expenses and debt, often called the debt service coverage ratio. Your personal financial picture still matters, but the properties largely qualify themselves rather than leaning entirely on your personal income the way a single residential mortgage would. CMHC has useful background on how rental and multi-unit financing is evaluated, if you want the longer technical version: cmhc-schl.gc.ca.

Frequently asked questions

What is a blanket mortgage?
A single mortgage that covers two or more properties under one loan, rather than a separate mortgage for each one.

How many rental properties do I need before a blanket mortgage makes sense?
There’s no fixed number. It depends on your properties, your lender options, and whether consolidating actually improves your rate or terms — two very different properties might not benefit the way four similar ones would.

Does a blanket mortgage cost more than separate mortgages?
Not necessarily. Closing and legal costs can come in lower since there’s one closing instead of several, though pricing varies by lender and situation.

Who this is actually for

If you own more than one rental property and you’re tired of renewing on four different clocks, that’s exactly the kind of file I like working on. I pull it together with my commercial lending partner, structure it as one request instead of several separate ones, and walk you through whether a blanket structure actually saves you money — or whether keeping your properties separate is the smarter move for your situation. Every portfolio is different, and that’s the first thing worth figuring out.

If you’re sitting on a handful of renewal dates scattered through the year and wondering if there’s a cleaner way, that’s exactly the conversation worth having. Start here: https://craigburn-capital.mtg-app.com. For the full rundown of how we handle single-file comparisons across lenders, see our earlier piece: Five Lenders, One Hit.
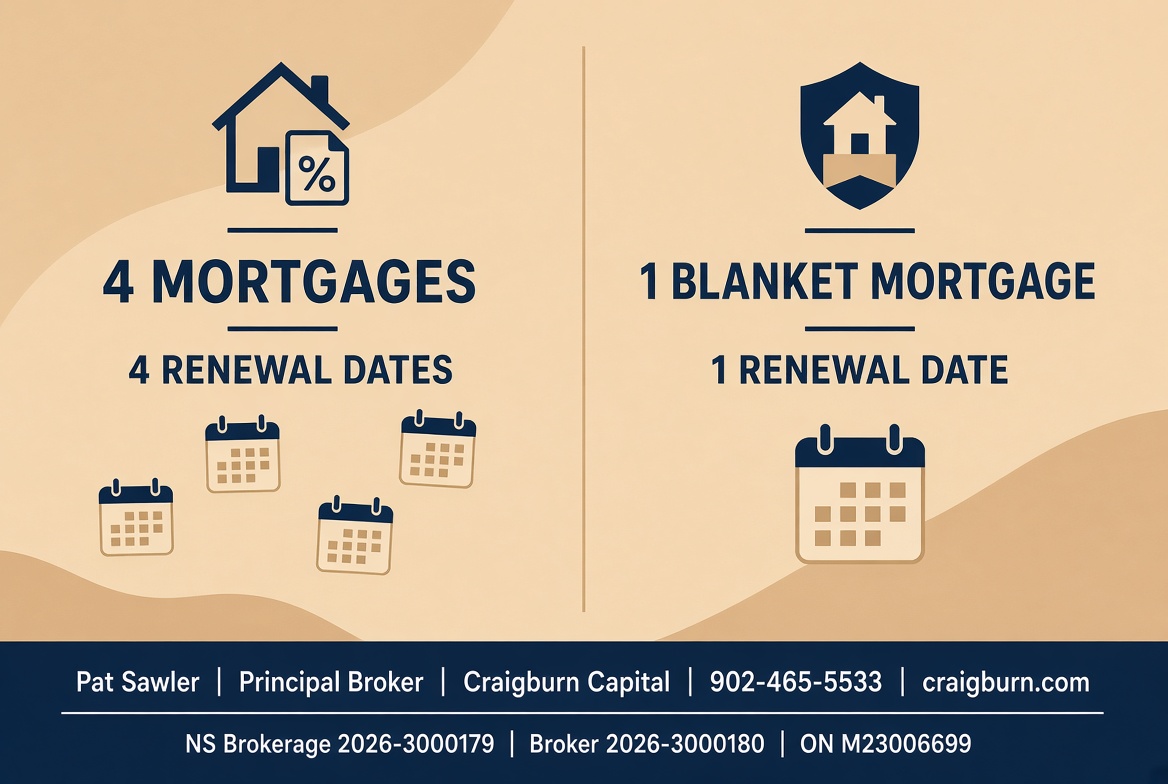
Comparison of four separate mortgage renewal dates versus one blanket mortgage renewal date

I look forward to hearing from you in regard to your mortgage needs.

902-465-5533. I answer.

Patrick

p.s. Start your application anytime: https://craigburn-capital.mtg-app.com
p.s. Prefer to talk first? Book a time here: https://patricksawler-craigburn.zohobookings.com/3983211000000025015
p.s. NS Brokerage 2026-3000179 | Broker 2026-3000180 | ON M23006699
p.s. Get the Craigburn mortgage app for updates on your file

Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone.

Own more than one rental property and tired of juggling renewal dates? Reach out — 902-465-5533, or start here: https://craigburn-capital.mtg-app.com

“No Tears in Commercial”

[GIF suggestion: the Wolf of Wall Street whiteboard scene, or a calm “just the numbers” moment — something that signals serious but approachable]

Let me tell you about a client of mine.

He’s on his fourth project.

Not his fourth mortgage. His fourth project — a multi-unit apartment building in Nova Scotia. Before that, another multi-unit building. Before that, a portfolio of commercial rental cottages. Before that, a building he sold to fund the next chapter.

Eighteen months of work together. Four deals. One financing advisor relationship that keeps building — literally.

And in eighteen months he has never once called me to ask about his rate.

That tells you everything you need to know about commercial financing.

What commercial clients actually care about.

In residential mortgages, I regularly hear from clients who want to discuss a difference of 0.10% on their rate. That’s one tenth of one percent. On a $500,000 mortgage over five years we’re talking about a few hundred dollars.

I don’t blame them. A home is the most emotional purchase most people will ever make. The rate feels like the one thing they can control in a process that otherwise feels wildly out of their hands.

Commercial is completely different.

When my developer client and I sit down to talk financing, the conversation always goes in this order:

First — Loan amount. Can we get enough money to actually complete the project? Everything else is secondary. A great rate on insufficient capital is a disaster.

Second — Amortization. How long can we stretch the repayment? The longer the amortization, the lower the monthly payment, the better the cash flow, the stronger the return on investment. A 45-year CMHC amortization versus a 30-year conventional can be the difference between a project that cash flows beautifully and one that barely breaks even.

Third — Rate. Yes, rate matters. But here’s the honest truth about commercial rates: I don’t know what your rate will be until we submit the file. Commercial rates are tied to bond markets that move every single day. What I can promise is that we’ll get you the best rate available when your file is ready — and I’ll tell you immediately if the market shifts in a way that changes your numbers.

That’s not residential thinking. That’s investment thinking.

What the analysis actually looks like.

Note: The following is a representative example based on a typical multi-unit residential project in Nova Scotia, presented for illustrative purposes.

When my commercial lending partner and I work on a file like this, we’re not filling out a mortgage application. We’re building an income analysis.

We look at gross rental income, vacancy allowances, and operating expenses line by line — management fees, realty taxes, utilities, insurance, repairs, wages, and reserves. We calculate Net Operating Income. We run capitalization rates. We model the deal two ways — conventional financing and CMHC — and show our client exactly what each scenario means for their loan amount, monthly payment, debt service coverage ratio, and equity position.

On a typical 16-unit project in Nova Scotia with average rents around $1,694 per unit, you’re looking at a Net Operating Income approaching $250,000 and an appraised value in the $4.5 to $5 million range. Two financing paths emerge — conventional at a higher rate with a 30-year amortization, or CMHC at a lower rate stretched to 45 years with a meaningfully higher loan amount and lower monthly payments.

Which one is better? Depends entirely on the client’s goals, timeline, and what they’re planning to do next. That’s the conversation we have. That’s the advisory relationship.

There are no tears in that conversation. Just numbers, options, and decisions.

Why commercial clients are different.

I want to be careful here because I love working with first-time buyers — guiding someone through their first home purchase is genuinely one of the most satisfying things I do.

But commercial clients come to the table differently. They’ve already separated emotion from investment. They’re asking about cap rates and debt service coverage ratios, not whether the kitchen feels right. They want to know if the numbers work, not if the building is pretty.

And when you’re the person who can answer those questions — who can model the deal, know the lenders, and understand the difference between a CMHC MLI Select application and a conventional submission — you stop being a broker and start being a partner.

My developer client isn’t calling me when he needs a mortgage. He’s calling me when he’s looking at a piece of land and wondering if the numbers could work.

That’s a completely different relationship. And honestly? It’s the one I like best.

Thinking about your first commercial deal?

If you own residential investment properties and you’re wondering whether commercial financing could work for your next project — let’s talk. The jump from residential investing to commercial isn’t as complex as it looks from the outside. It just requires a different kind of analysis and a broker who’s done it before.

I work on commercial files across Nova Scotia, Atlantic Canada, and Ontario. My commercial lending partner and I have seen a lot of deals — the ones that work and the ones that don’t. We’ll tell you honestly which category yours falls into.

Patrick ???? 902-465-5533 Craigburn.com

p.s. — My client’s first project was a leap of faith. His fourth is just math. That progression — from nervous first-time investor to confident developer — is exactly what the right financing advisor helps you build toward. Give me a call.