Tag Archive for: Alternative commercial financing

Generational Wealth through Real Estate

Building Generational Wealth Through Real Estate in Canada: A Step-by-Step Guide

Introduction

Generational wealth is about creating long-term financial security that benefits not just you but your children and grandchildren. One of the most proven ways to achieve this in Canada is through strategic investments in residential and commercial real estate.

As a mortgage broker with extensive experience in real estate financing, I’ve helped countless clients build portfolios that generate passive income, appreciate in value, and provide financial freedom. In this guide, I’ll walk you through the step-by-step process of building generational wealth with real estate—and explain why working with the right mortgage broker (like me!) can make all the difference.


Why Real Estate is the Best Vehicle for Generational Wealth

Before diving into the steps, let’s look at why real estate is such a powerful wealth-building tool:

  1. Appreciation Over Time – Historically, Canadian real estate has steadily increased in value, especially in high-demand markets like Toronto, Vancouver, and Montreal and increasingly in Atlantic Canada markets like Halifax and Dartmouth, which have seen significant appreciation over the past several years..
  2. Cash Flow from Rentals – Well-chosen properties generate monthly rental income, providing a steady passive revenue stream.
  3. Leverage – Banks will lend you money to buy real estate, allowing you to control a high-value asset with a relatively small down payment.
  4. Tax Advantages – Expenses like mortgage interest, maintenance, and property management can be deducted from rental income. Capital gains on primary residences are tax-free in Canada.
  5. Inflation Hedge – Real estate values and rents tend to rise with inflation, protecting your wealth.

Now, let’s break down exactly how to build wealth through real estate.


Step 1: Define Your Financial Goals

Before jumping into real estate investing, you need a clear plan. Ask yourself:

  • What is your long-term vision? (e.g., financial independence, leaving an inheritance, funding education for future generations)
  • How much risk are you comfortable with? (e.g., fix-and-flip vs. long-term rentals)
  • What’s your timeline? (5 years? 10 years? 30 years?)

Having clear goals will shape your investment strategy.


Step 2: Build a Strong Financial Foundation

Real estate investing requires good credit, savings, and financial discipline. Here’s how to prepare:

  • Improve Your Credit Score (Aim for 700+ to secure the best mortgage rates)
  • Save for Down Payments (Minimum 5% for owner-occupied, 20% for investment properties)
  • Reduce Debt (Lenders look at your debt-to-income ratio—keep it below 40%)
  • Get Pre-Approved (This shows sellers you’re serious and helps you move quickly)

As a mortgage broker, I can help you optimize your finances to qualify for the best loans.


Step 3: Start with Residential Real Estate

Most investors begin with residential properties (single-family homes, condos, duplexes). Here’s how:

Option 1: House Hacking (Live for Free While Building Equity)

  • Buy a duplex/triplex, live in one unit, and rent out the others.
  • The rental income can cover your mortgage, allowing you to live mortgage-free while building equity.

Option 2: Buy and Hold (Long-Term Rentals)

  • Purchase a property in a high-rental-demand area.
  • Use rental income to cover expenses and mortgage payments.
  • Over time, refinance to pull out equity and reinvest.

Option 3: Fix-and-Flip (Short-Term Profit)

  • Buy undervalued properties, renovate, and sell for a profit.
  • Requires more hands-on involvement but can generate quick cash for further investments.

Step 4: Scale with Multi-Unit and Commercial Properties

Once you’ve built equity in residential properties, you can expand into larger investments:

Multi-Unit Apartment Buildings

  • More units = more cash flow.
  • Financing is different from residential—I can help structure the right loan.

Commercial Real Estate (Retail, Office, Industrial)

  • Longer leases provide stable income.
  • Higher returns but require more due diligence.

Step 5: Leverage Refinancing & HELOCs to Grow Your Portfolio

Instead of selling properties, smart investors refinance to access equity and buy more real estate.

  • Cash-Out Refinance: Take out a new mortgage (at today’s higher property value) and use the cash to buy another property.
  • HELOC (Home Equity Line of Credit): Use your existing property’s equity as a revolving credit line for new investments.

I specialize in helping investors structure these loans efficiently.


Step 6: Protect Your Wealth with Proper Legal & Tax Strategies

  • Incorporate (Holdco vs. Opco): Protect assets and optimize taxes.
  • Use a Property Management Company: Scale without burnout.
  • Estate Planning: Ensure smooth wealth transfer to heirs (trusts, wills, joint ownership).

Why I’m the Ideal Mortgage Broker for Your Wealth-Building Journey

Here’s how I add value to your real estate investing strategy:

Access to Exclusive Lender Deals – I work with banks, credit unions, and private lenders to get you the best rates and terms.
Creative Financing Solutions – From cash-flow-based lending to commercial mortgages, I find loans traditional banks won’t offer.
Investor-Focused Advice – I don’t just process mortgages; I help you build a long-term wealth plan.
Speed & Efficiency – In competitive markets, quick financing wins deals—I get approvals fast.
Ongoing Portfolio Support – As your portfolio grows, I’ll help you optimize debt and scale strategically.


Final Thoughts: Start Now, Build Forever

Generational wealth doesn’t happen overnight, but with the right strategy, discipline, and financing, real estate can secure your family’s financial future for decades.

If you’re ready to take the first step (or the next one), let’s talk. As your mortgage broker, I’ll ensure you have the funding to acquire cash-flowing properties and grow your portfolio efficiently.

If commercial real estate is part of your wealth-building plan, two numbers matter before anything else: your loan-to-value and your cap rate. I’ve written about both — understanding commercial LTV and a free Cap Rate & Deal Analyzer— worth a look before your next deal.

I look forward to hearing from you in regard to your mortgage needs.

Patrick

p.s- You can click on this link to start the process whenever you are ready. Schedule your meeting with me here.

p.s.s- I should tell you that I am licensed in Nova Scotia Brokerage (2024-3000179) Broker (2024-3000180), Ontario(M18001555) & in British Columbia(BCFSA #504098).

p.s.s.s You can download my new mortgage app here

Don’t miss out on this opportunity to secure the best financing terms for your next multi-unit development. Contact me today!

With my experience and industry connections, I’ll ensure you get the most competitive terms to make your commercial property investment a success.

Roll the dice

Getting Approved Isn’t Luck. It’s a Checklist.

Most people treat commercial mortgage approval like a roll of the dice — you submit your application, hold your breath, and hope for the best. It isn’t luck. Every underwriter who reviews your file is working through the same short list of boxes, in roughly the same order, every single time. Know the checklist, and the outcome stops feeling random.

Here’s exactly what’s being checked — and how to make sure every box comes back green before you submit.

Box 1: Debt Service Coverage Ratio (DSCR)

The underwriter’s first question is simple: does the property’s income actually cover the mortgage payment? Most lenders want to see a DSCR of 1.25 or higher — meaning the property generates 25% more income than what’s needed to service the debt.

Here’s what that looks like in real numbers. Say you’re buying a 4-unit property in Halifax generating $48,000 in annual net operating income. Your proposed mortgage payment is $32,000 a year. That’s a DSCR of 1.50 — comfortably above the 1.25 threshold, and a deal most lenders would be glad to underwrite. Drop the rents to $38,000 against that same $32,000 payment, and your DSCR falls to 1.19 — under the line, and now the deal needs a bigger down payment, a lower purchase price, or it waits.

Before you submit: run your own DSCR calculation using realistic (not optimistic) rent projections. If it’s under 1.25, either the price needs to come down, the down payment needs to go up, or the deal needs to wait.

Box 2: Loan-to-Value (LTV) Ratio

The second box is how much you’re borrowing relative to what the property’s worth. Lenders typically want 75% or lower, though this varies by property type — multi-family with CMHC insurance can go up to 85%, while special-purpose properties may cap out at 50-65%.

Using the same 4-unit example: if the property appraises at $900,000 and you’re requesting a $650,000 loan, that’s a 72% LTV — inside the typical 75% ceiling. Push the loan to $700,000 on that same appraisal and you’re at 78%, which pushes you outside most conventional lenders’ comfort zone and into a smaller pool of options.

Before you submit: know your LTV cold, and know which bucket your property type falls into. Walking in with the wrong expectation here is one of the most common reasons deals stall.

Box 3: Financial Statements

Underwriters want to see the real financial picture — personal and business income statements, balance sheets, and two to three years of tax returns. This isn’t a formality; it’s how they verify everything else in your application actually holds up.

Before you submit: have these organized and current before you apply, not scrambled together after a lender asks. A clean, complete package the first time signals you’re a low-friction borrower.

Box 4: Property Viability

The underwriter isn’t just assessing you — they’re assessing the property. Is it in a location with real demand? Does it meet zoning and regulatory requirements? Would it hold its value if you needed to exit?

Before you submit: have comparable sales, a realistic rent roll, and confirmation the property is zoned for its intended use.

Box 5: Your Experience

If this is your first commercial property, that’s not disqualifying — but it is a checked box either way. Lenders factor in whether you (or a partner) have managed similar properties or businesses before.

Before you submit: if you’re a first-timer, consider bringing in a co-signer or property manager with a track record. It directly offsets this box.

Box 6: Down Payment Strength

Most commercial mortgages require 20-30% down. More than the minimum does real work for you — it lowers your LTV, often improves your rate, and reduces the debt load the lender is underwriting against.

Before you submit: know that every extra percentage point down is negotiating leverage, not just a bigger check.

Box 7: Your Total Portfolio Exposure

This one surprises a lot of first-time commercial buyers. Lenders don’t just look at the single property in front of them — they look at your total exposure across everything you already own. If you’re carrying three other mortgages, even performing ones, that changes how much additional risk a lender is willing to take on with you specifically.

Before you submit: have a clear summary of your existing portfolio ready — every property, every mortgage balance, every income stream tied to them. If you’re actively expanding, this is a box worth discussing with your broker before it becomes a surprise mid-application.

Your LTV and DSCR are two of the seven boxes above — but they’re also the two numbers worth understanding in more depth before you apply anywhere. I’ve broken down how commercial LTV actually works, and built a free Cap Rate & Deal Analyzer that runs your cap rate and DSCR side by side — worth running your numbers through before you submit.

When the Checklist Doesn’t Line Up

If one or two boxes aren’t where they need to be, that doesn’t mean the deal is dead — it means you go to a different door.

Credit unions often have more flexibility than the big banks on income verification and property type, while still operating under regulated, conventional terms.

Monoline lenders — mortgage-only institutions with no branches, working exclusively through brokers — sometimes offer more competitive rates and more flexible underwriting than traditional banks, precisely because mortgages are their entire business.

Private lenders evaluate the same boxes but weigh them differently — a DSCR or LTV that a bank rejects outright might be perfectly financeable through a private bridge loan, at a higher rate, as a short-term solution while you strengthen your position for conventional refinancing later.

This is where working with a broker changes the outcome — not because of luck, but because I know which lender’s checklist your file actually fits.

Frequently Asked Questions

What DSCR do I need for a commercial mortgage in Canada?
Most conventional lenders want a minimum DSCR of 1.25, meaning the property’s income covers the mortgage payment with 25% to spare. Some alternative and private lenders will consider deals closer to 1.0-1.15, typically at a higher rate.

What’s a good LTV for commercial financing?
75% or lower is the general benchmark for conventional lenders, though CMHC-insured multi-family properties can go up to 85%. Special-purpose properties (like self-storage or single-tenant industrial) are typically capped lower, around 50-65%.

Can I get approved for a commercial mortgage with no prior experience?
Yes — lack of experience isn’t disqualifying, but it is a factor lenders weigh. Bringing in an experienced co-signer or a property management partner can offset this and strengthen your application.

Why Work With Me

I don’t submit your file and hope. I go through this exact checklist with you before we ever approach a lender, so we’re not finding out about a weak box after a decline — we’re fixing it in advance, or steering to the lender whose criteria already fits your numbers.

If you’re preparing for a commercial purchase or refinance, let’s run your file against this checklist together before you apply anywhere.

Patrick

p.s- You can click on this link to start the process whenever you are ready. Schedule your meeting with me here.

p.s.s- I should tell you that I am licensed in Nova Scotia Brokerage (2025-3000179) Broker (2025-3000180), Ontario(M18001555).

p.s.s.s You can download my new mortgage app here

Retail vs Industrial Real Estate

Retail vs. Industrial: Where to Invest in Commercial Real Estate in 2026

Investing in commercial real estate continues to be a strong wealth-building strategy, but choosing the right sector is crucial for success. As we move through 2025, two dominant sectors—retail and industrial—present unique opportunities and challenges for investors. With evolving consumer behaviors, shifting market dynamics, and macroeconomic factors influencing demand, determining the best investment path requires careful analysis.

Retail Real Estate: A Sector in Transition

The retail sector has faced substantial transformation over the past decade, primarily driven by e-commerce growth and changing shopping habits. However, despite initial concerns about the “death of retail,” this sector remains resilient and continues to evolve in ways that create investment opportunities.

1. The Resurgence of Experiential and Service-Based Retail

While traditional brick-and-mortar stores have faced headwinds, experiential retail—such as entertainment centers, restaurants, fitness studios, and service-based businesses—has gained traction. Consumers are prioritizing experiences over products, making these spaces highly attractive for investors.

2. The Strength of Essential Retail

Grocery stores, pharmacies, medical offices, and discount retailers have remained stable performers. These tenants provide consistent foot traffic and long-term lease stability, making them a lower-risk investment option within the retail sector.

3. The Role of Mixed-Use Developments

Developers are incorporating retail spaces into mixed-use developments that combine residential, office, and entertainment components. Investing in retail units within well-planned mixed-use projects can provide high occupancy rates and increased property value over time.

4. Challenges in the Retail Sector

Retail investments are not without risks. The continued dominance of online shopping means some retail spaces, especially in secondary markets, may struggle with vacancies. Additionally, fluctuating consumer spending due to economic conditions can impact retailers’ profitability and their ability to pay rent.

Industrial Real Estate: The Powerhouse of Commercial Real Estate

The industrial sector has been one of the best-performing asset classes in recent years, fueled by e-commerce growth, supply chain demands, and technological advancements.

1. E-Commerce and Logistics Boom

Online shopping continues to drive demand for warehouse and distribution centers. With companies prioritizing last-mile delivery and optimizing supply chains, industrial properties in key transportation hubs remain a hot commodity for investors.

2. The Growth of Manufacturing and Production Facilities

Domestic manufacturing is experiencing a resurgence as companies seek to reduce reliance on overseas production. This has increased demand for industrial properties that can house production facilities, specialized manufacturing, and research and development centers.

3. The Rise of Multi-Tenant Industrial Properties

Smaller industrial spaces catering to multiple tenants, such as e-commerce startups, small manufacturers, and third-party logistics providers, are gaining popularity. These properties provide diversification and reduce risk by not relying on a single large tenant.

4. Challenges in the Industrial Sector

While industrial real estate remains strong, high acquisition costs and rising interest rates pose financing challenges. Additionally, zoning regulations and limited land availability in prime markets can restrict new developments, potentially driving up property prices and making entry more competitive for investors.

What the Numbers Actually Look Like

Here in Atlantic Canada, the gap between these two sectors shows up clearly in cap rates and vacancy. Well-located industrial properties — warehouse and distribution space near the Halifax port or along the 102/103 corridors — have been trading in the 6-7% cap rate range, with vacancy consistently under 3%. Essential retail (grocery-anchored plazas, pharmacy-anchored strips) sits closer to 7-8% cap rate, with vacancy in the 5-8% range depending on tenant mix. Experiential and service retail can swing wider in both directions depending on the specific tenant’s staying power.

The takeaway: industrial’s lower cap rate reflects lower perceived risk and higher demand — you’re paying more for the same dollar of income because the tenant base is considered more stable. Retail’s higher cap rate can mean a better initial yield, but it comes with more tenant-mix risk to underwrite carefully.

Retail vs. Industrial: Which One Is the Better Investment in 2026?

Both retail and industrial real estate have compelling investment potential, but the right choice depends on your investment goals, risk tolerance, and market conditions.

  • Retail may be a better choice if:
    • You are targeting high-traffic locations with strong experiential or service-based retail.
    • You are investing in essential retail tenants with long-term leases.
    • You want to be part of a mixed-use development where retail complements residential and office spaces.
  • Industrial may be the better choice if:
    • You want a high-demand asset class with strong long-term appreciation potential.
    • You prefer lower tenant turnover and stable rental income from logistics and manufacturing tenants.
    • You are willing to navigate zoning and development challenges for a high-reward investment.

How to Secure the Best Financing for Your Investment

Whether you choose retail or industrial real estate, securing the right financing is key to maximizing your returns. Market conditions, interest rates, and lender requirements can vary between sectors, making expert guidance essential.

Why I Am the Ideal Mortgage Broker to Assist You

Financing retail and industrial properties isn’t the same conversation — different lenders favor different sectors, and the underwriting priorities shift depending on tenant type, lease structure, and location. As an experienced commercial mortgage broker, I provide:

  • Sector-Specific Lender Relationships – I know which lenders are actively pursuing industrial deals right now, and which ones remain comfortable with retail despite the sector’s reputation.
  • Realistic Underwriting Guidance – Whether it’s a grocery-anchored plaza or a multi-tenant warehouse, I help you understand what a lender will actually approve before you make an offer.
  • Market Insight – I track cap rates and vacancy trends across both sectors in Atlantic Canada specifically, not just national averages.
  • Two Numbers Worth Knowing Before You Decide – Whichever sector you’re leaning toward, run your loan-to-value and cap rate first. I’ve broken down how commercial LTV actually works, and built a free Cap Rate & Deal Analyzer to help you compare deals side by side.

If you’re weighing retail against industrial for your next investment, let’s talk through the financing side before you commit to either.

I look forward to hearing from you in regard to your mortgage needs.

Patrick

p.s- You can click on this link to start the process whenever you are ready. Schedule your meeting with me here.

p.s.s- I should tell you that I am licensed in Nova Scotia Brokerage (2025-3000179) Broker (2025-3000180), Ontario(M18001555).

p.s.s.s You can download my new mortgage app here

Future of Office space in Canada

The Future of Office Spaces in Canada: Should You Invest?

The commercial real estate landscape in Canada has undergone a major shift in recent years, with office spaces being at the center of this transformation. The rise of remote and hybrid work models, fluctuating demand, and evolving tenant needs have left many investors questioning whether office space remains a viable investment. Despite the challenges, opportunities still exist for those who can adapt to market trends and leverage strategic financing solutions.

The Changing Office Space Landscape in Canada

1. The Hybrid Work Revolution

The pandemic accelerated the adoption of remote and hybrid work models, reducing the overall demand for traditional office spaces. Many companies have downsized their office footprints, opting for flexible workspace solutions that accommodate employee preferences. However, this doesn’t mean the office is obsolete. Instead, it is evolving.

2. The Rise of Flexible and Co-Working Spaces

With companies seeking more adaptable solutions, co-working spaces and flexible office leases have become increasingly popular. Investors looking to enter the office space market can benefit from this trend by investing in properties that can be reconfigured for shared workspaces or short-term leasing arrangements.

3. A Flight to Quality

While some office buildings face higher vacancy rates, Class A office spaces in prime locations continue to attract tenants. Companies are prioritizing high-quality office spaces with modern amenities, sustainable features, and health-conscious designs to entice employees back to the office. Investors focusing on premium office properties may find opportunities in this shift.

4. Suburban vs. Urban Office Demand

Downtown office markets have experienced fluctuating demand as some companies relocate to suburban areas where rents are lower and commuting is more convenient. Suburban office investments, particularly in growing economic hubs, could be a smart move for investors looking to capitalize on changing workforce preferences.

5. Government and Institutional Influence

Government policies and incentives, such as tax breaks and grants for green office buildings, are encouraging investments in sustainable office spaces. Additionally, some large institutions and corporate tenants are making long-term commitments to office leases, signaling stability in certain segments of the market.

Why Office Space Still Holds Investment Potential

Despite challenges, office spaces remain an essential part of the commercial real estate sector. Here’s why investing in office properties can still be a smart move:

1. Long-Term Lease Stability

Office leases tend to be longer-term compared to other commercial real estate sectors, providing investors with stable, predictable income streams. Businesses that require physical space, such as law firms, financial institutions, and tech hubs, continue to seek well-located office properties.

2. Adaptive Reuse Opportunities

Investors can repurpose underutilized office spaces into mixed-use developments, residential units, or hybrid office-retail spaces. Converting office buildings into residential apartments or student housing is becoming a viable investment strategy in cities with housing shortages.

3. Increasing Demand for ESG-Compliant Buildings

Environmental, social, and governance (ESG) factors are driving office space demand. Companies are seeking eco-friendly, energy-efficient buildings to meet corporate sustainability goals. Investing in green-certified office properties can attract high-quality tenants and improve asset value.

4. Lower Acquisition Costs in Certain Markets

Due to the uncertainty surrounding office demand, some office properties are currently available at discounted prices. Investors with a long-term perspective can capitalize on lower acquisition costs and reposition properties to meet future market needs.

5. The Need for Centralized Collaboration Hubs

Even with hybrid work models, businesses still require office spaces for collaboration, meetings, and maintaining company culture. Investing in well-designed, amenity-rich office buildings that cater to these needs can yield strong returns.

What This Looks Like Here in Halifax

The national trends above are playing out locally with real numbers behind them. As of Q2 2026, Halifax’s office vacancy sat at 9.0%, holding steady despite a slowdown in leasing activity — a genuinely tight market by Canadian standards, where a “balanced” market is typically considered around 10%. The flight-to-quality trend isn’t theoretical here either: Class A net asking rents have climbed to $20.04 per square foot, with landlords able to push pricing because limited high-quality supply meets sustained tenant demand.

The takeaway for investors: this isn’t a market flooded with empty towers looking for any tenant. It’s a market where good buildings in the right location are performing well, while older, lower-class stock is where the real repositioning opportunity — and risk — lives.

Key Considerations Before Investing in Office Space

1. Location Matters More Than Ever

Prime locations with strong tenant demand, good transit access, and vibrant surroundings remain resilient. Conducting thorough market research is essential to choosing the right office investment.

2. Flexibility is Key

Future-proof office investments must offer flexibility in design, lease terms, and usage. Buildings with open floor plans, tech-enabled workspaces, and adaptive layouts will have a competitive advantage.

3. Financing the Investment

Interest rates, loan terms, and lender requirements play a crucial role in office space investments. Securing the right financing strategy will determine profitability and long-term success.

Why I Am the Ideal Mortgage Broker to Assist You

Navigating the complexities of commercial office space financing requires expertise and access to the right lending solutions. As an experienced mortgage broker specializing in commercial real estate, I provide:

  • Access to a Wide Range of Lenders – I work with major banks, private lenders, and alternative financing sources to find the best loan options for your investment.
  • Customized Financing Strategies – Whether you’re purchasing, refinancing, or repositioning an office building, I tailor financing solutions to align with your goals.
  • Market Insights and Expert Guidance – With in-depth knowledge of the Canadian commercial real estate market, I help you identify profitable investment opportunities.
  • Streamlined Loan Approval Process – I simplify the mortgage application process, saving you time and ensuring a smooth experience.

If you’re considering investing in office spaces, I’m here to help you secure the right financing to maximize your returns. Contact me today to discuss your commercial mortgage needs and take advantage of the evolving office space market!

I look forward to hearing from you in regard to your mortgage needs.

Patrick

p.s- You can click on this link to start the process whenever you are ready. Schedule your meeting with me here.

p.s.s- I should tell you that I am licensed in Nova Scotia Brokerage (2025-3000179) Broker (2025-3000180), Ontario(M18001555).

p.s.s.s You can download my new mortgage app here

Whether you’re eyeing a Class A building or a repositioning opportunity in an older asset, the numbers above only tell half the story — your actual return depends on your financing structure. I’ve broken down how commercial LTV actually works, and built a free Cap Rate & Deal Analyzer to help you run the numbers on any office property you’re considering.

Dive into your next investment

Is Now the Right Time to Invest in Commercial Property? A Market Analysis

The commercial real estate market in Canada has been through significant changes in recent years, shaped by economic conditions, shifting work environments, and evolving investor sentiment. If you’re considering investing in commercial property, you’re likely wondering: is now the right time? The answer depends on a handful of factors — market trends, financing conditions, and long-term investment potential — not a single headline number.

Current Market Trends in Canadian Commercial Real Estate

Demand for Industrial and Multifamily Properties Remains Strong

While some sectors of commercial real estate are experiencing volatility, industrial properties and multifamily residential buildings continue to perform exceptionally well. E-commerce growth has fueled demand for warehouses and distribution centers, while housing shortages in major cities have kept multifamily investments attractive.

Split illustration showing strong demand in industrial warehouse and multifamily residential properties with upward trend arrows

Office Market Uncertainty Presents Opportunities

The rise of remote and hybrid work has reshaped office space demand. While traditional office spaces are experiencing some vacancies, many companies are reconfiguring their work environments rather than abandoning office space altogether. This shift presents opportunities for investors who can repurpose or reposition office buildings to meet modern workplace needs.

Illustrated office building at dusk with the text Office Market Uncertainty equals Opportunity for Repositioning

Retail Sector Adjustments

The retail sector is transforming, with large-scale retailers embracing omnichannel strategies. Investors who focus on high-traffic retail spaces or properties suited for experiential businesses — dining, entertainment, service-based tenants — may find profitable opportunities here.

Interest Rates and Their Impact on Investments

Interest rates remain a major factor in underwriting decisions. Recent years of rate movement increased borrowing costs and pushed investors toward more cautious deal structuring. As rates stabilize, the investors doing well aren’t the ones waiting for a “perfect” rate — they’re the ones structuring deals that work at today’s rate.

Why Investing in Commercial Property Still Makes Sense

Despite market fluctuations, commercial real estate remains one of the more reliable vehicles for long-term wealth building. Here’s why:

Inflation Hedge

Real estate historically serves as a hedge against inflation, since property values and rental income tend to rise alongside it. That makes commercial properties an attractive long-term hold even in an uncertain rate environment.

Passive Income and Appreciation

Investors benefit from stable rental income while also seeing property values appreciate over time. Well-chosen commercial properties in high-demand areas can generate meaningful returns on both fronts.

Financing Options That Still Work

Even with rates higher than a few years ago, lenders continue to offer competitive terms for well-structured commercial deals. The difference between an average financing outcome and a strong one usually comes down to how the deal is packaged and who’s presenting it — not just the rate on offer.

Opportunities in Distressed Assets

Market fluctuations often create distressed sales, where properties trade below market value. These situations can provide strong entry points for investors willing to do the underwriting work.

How to Make a Smart Investment Decision

Research Market Conditions

Understanding regional market trends is essential. Some areas are experiencing a commercial real estate boom, while others are still recovering. Do your homework, or work with someone who already has, to understand local supply and demand dynamics before you commit.

Secure the Right Financing

Your financing structure can make or break an investment. Working with an experienced mortgage broker helps you access the best available terms — whether through traditional lenders, private financing, or CMHC-backed programs — rather than settling for whatever the first lender you call happens to offer.

Evaluate Property Potential Properly

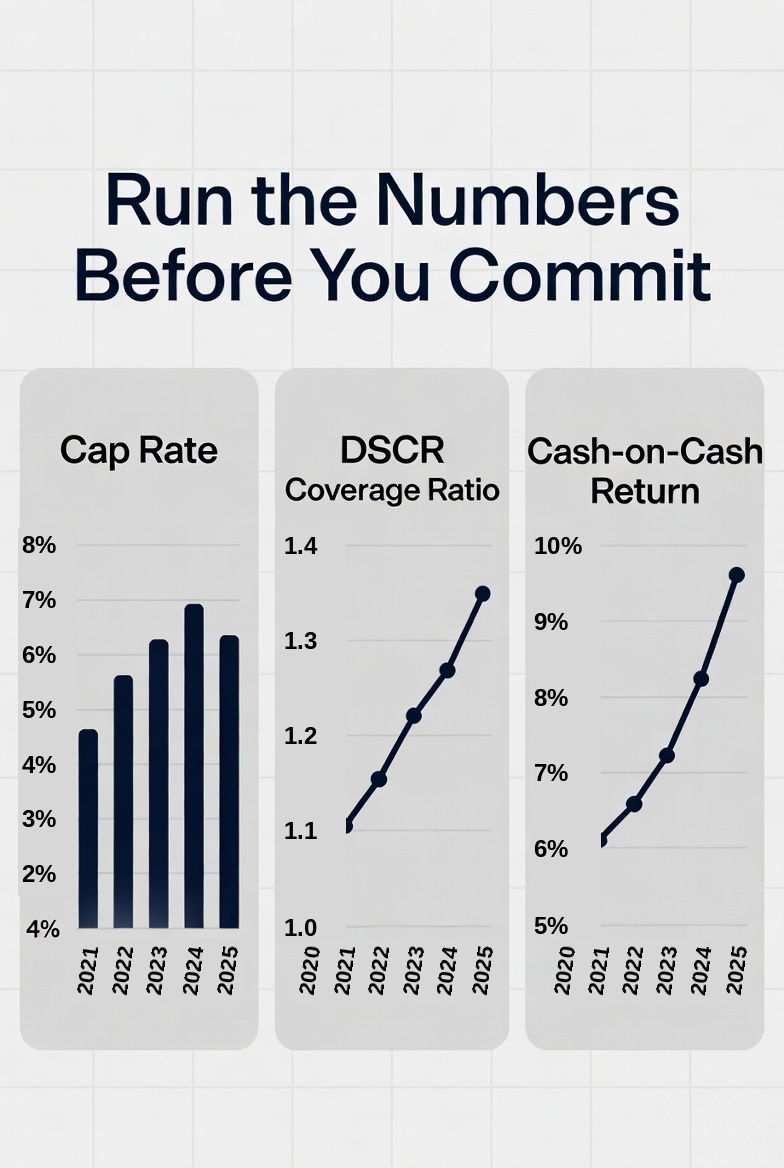
Not all commercial properties are created equal. Location, tenant quality, lease terms, and future growth potential all factor into whether a property is worth the investment. This is also where the numbers matter more than the story: a property can look great on paper and still be a mediocre deal once the real cash flow is worked out. I built a free Cap Rate & Deal Analyzer that shows you cap rate, DSCR, and cash-on-cash return side by side — so you can see what a deal actually pays you after financing, not just what it looks like before it.

Three charts showing cap rate, DSCR coverage ratio, and cash-on-cash return trends from 2021 to 2025

Plan for Market Fluctuations

Real estate is cyclical, so it’s worth planning for both short-term uncertainty and long-term growth. Diversifying across property types and maintaining a financial cushion helps you navigate changing conditions without being forced into a bad decision at the wrong time.

Where This Leaves You

None of this means timing doesn’t matter — it does. But “the right time” has less to do with waiting for perfect conditions and more to do with whether your specific deal, on its specific numbers, works today. Industrial and multifamily remain strong. Office and retail carry real opportunity for investors willing to look past the headlines. And financing, structured properly, is still very much available for the right deal.

If you’re weighing a commercial property investment and want a clear-eyed read on whether the numbers actually work, let’s talk about your specific deal — not a generic market outlook.

Let's talk about your specific deal, contact Patrick Sawler at 902-465-5533 or craigburn.com

Patrick Sawler | Principal Broker | Craigburn Capital | 902-465-5533 | craigburn.com

NS Brokerage 2025-3000179 | Broker 2025-3000180 | ON M23006699

Understanding Commercial LTV

Understanding Loan-to-Value (LTV) Ratios in Commercial Mortgage Lending

Loan-to-Value (LTV) ratios play a crucial role in commercial mortgage lending, influencing borrowing power, interest rates, and financing terms. Whether you’re an investor, developer, or business owner, understanding how LTV ratios impact your loan application can help you secure the best possible financing for your commercial project. In this blog post, we will explore the significance of LTV ratios, how they are calculated, their impact on lending decisions, and strategies to optimize your borrowing potential.

What Is Loan-to-Value (LTV) Ratio?

The Loan-to-Value (LTV) ratio is a key metric used by lenders to assess the risk associated with a commercial mortgage loan. It represents the percentage of a property’s appraised value or purchase price that is being financed by the lender. The formula for calculating LTV is:

LTV Ratio = (Loan Amount / Property Value) × 100

Here’s a real-world example closer to home. Say you’re looking at a 6-unit multi-family building in Dartmouth, appraised at $1,400,000. A lender offers you a loan of $980,000. Your LTV ratio would be:

LTV = ($980,000 / $1,400,000) × 100 = 70%

This means the lender is financing 70% of the property’s value, and you’d need to cover the remaining 30% — $420,000 — as your down payment.

How LTV Ratios Impact Commercial Mortgage Lending

Lenders use LTV ratios to determine the level of risk associated with a loan. The higher the LTV, the greater the risk for the lender, as a larger portion of the property’s value is financed. Here are some ways LTV ratios impact borrowing power and loan terms:

1. Loan Approval and Borrowing Power

Lenders have maximum LTV thresholds based on the type of property and risk profile. Typical LTV limits for commercial mortgages include:

  • Multi-Family Residential Properties: Up to 85% (with CMHC insurance)
  • Office and Retail Buildings: 65%-75%
  • Industrial Properties: 70%-75%
  • Special-Purpose Properties: 50%-65%

If your LTV ratio is too high, you may need to provide a larger down payment or seek alternative financing options.

2. Interest Rates and Financing Costs

Lower LTV ratios typically result in more favorable loan terms, including lower interest rates. Lenders view low-LTV loans as less risky, which can translate to cost savings over the life of the loan. Conversely, higher LTV loans often come with higher interest rates and stricter lending conditions.

3. Private vs. Traditional Lenders

While banks and institutional lenders impose strict LTV limits, private mortgage lenders may offer higher LTV ratios in exchange for higher interest rates. This can be a valuable option for borrowers who need additional leverage but may not qualify for traditional financing.

4. Impact on Loan Insurance and CMHC Financing

For multi-unit residential properties, the Canada Mortgage and Housing Corporation (CMHC) offers mortgage insurance that allows borrowers to access higher LTV ratios (up to 85%) with lower interest rates. CMHC-backed loans are an excellent option for investors looking to maximize leverage while securing favorable terms.

5. Refinancing and Equity Access

LTV ratios also determine how much equity you can access when refinancing a commercial property. If property values appreciate, you may qualify for additional financing by maintaining an acceptable LTV ratio. However, if property values decline, your LTV ratio may increase, making refinancing more challenging.

Strategies to Optimize Your LTV Ratio and Secure Better Financing

Understanding how LTV ratios work can help you take strategic steps to secure better loan terms. Here are some ways to improve your LTV ratio:

1. Increase Your Down Payment

The simplest way to reduce your LTV ratio is by making a larger down payment. This lowers the lender’s risk and improves your chances of securing a competitive interest rate.

2. Choose CMHC-Insured Financing for Multi-Unit Properties

If you’re investing in multi-family properties, CMHC-insured loans allow you to access higher LTV ratios with lower interest rates, improving cash flow and long-term profitability.

3. Improve Property Value

Enhancing the property’s value through renovations, tenant improvements, or lease restructuring can help lower your LTV ratio when refinancing or obtaining additional financing.

4. Consider Alternative Financing Options

If traditional lenders impose restrictive LTV limits, private lenders or bridge financing may offer flexible solutions to meet your investment goals.

5. Work with an Experienced Commercial Mortgage Broker

Navigating LTV requirements and financing options can be complex. Working with a commercial mortgage broker ensures you receive expert guidance and access to the best loan products tailored to your needs.

LTV Is Only Half the Picture

Knowing your LTV tells you how much you can borrow. It doesn’t tell you whether the deal is actually a good one — that’s what cap rate is for. I built a free tool that runs both cap rate and DSCR side by side, so you can see your borrowing power and your actual return in the same place.

Try the Cap Rate & Deal Analyzer →

Why Work With Me?

Securing commercial mortgage financing requires expertise, market knowledge, and strong lender relationships. As a seasoned commercial mortgage broker, I specialize in helping investors and business owners secure the best financing solutions for their projects. Whether you need funding for a multi-unit residential development, office space, or industrial property, I am here to guide you every step of the way.

Ready to take the next step in your real estate investment journey? Contact me today to discuss your goals and find the perfect apartment building for your portfolio. Together, we can turn your investment dreams into reality.

I look forward to hearing from you in regard to your mortgage needs.

Patrick

p.s- You can click on this link to start the process whenever you are ready. Schedule your meeting with me here.

p.s.s- I should tell you that I am licensed in Nova Scotia Brokerage (2024-3000179) Broker (2024-3000180), Ontario(M18001555) & in British Columbia(BCFSA #504098).

p.s.s.s You can download my new mortgage app here

Don’t miss out on this opportunity to secure the best financing terms for your next multi-unit development. Contact me today!

With my experience and industry connections, I’ll ensure you get the most competitive terms to make your commercial property investment a success.
Top 5 challenges in financing your commercial real estate project

Top 5 Challenges and How to Overcome Them

Securing financing for commercial real estate projects can be complex, with various obstacles that investors and developers must navigate. From stringent lending requirements to market fluctuations, understanding these challenges and how to overcome them can make a significant difference in securing the right funding. Here are the top five challenges in commercial real estate financing and strategies to tackle them.

1. Stringent Lending Requirements

The Challenge: Traditional lenders, such as banks and credit unions, impose strict lending criteria, requiring extensive documentation, strong credit history, and significant down payments. Borrowers with limited liquidity or unconventional projects may struggle to qualify.

How to Overcome It:

  • Work with a commercial mortgage broker who has relationships with multiple lenders and can present your application in the best light.
  • Consider alternative lenders, such as private or non-bank lenders, who may have more flexible terms.
  • Strengthen your financial position by reducing debt, improving credit scores, and demonstrating strong cash flow.

2. High Interest Rates and Financing Costs

The Challenge: Commercial real estate loans often come with higher interest rates and additional costs, such as appraisal fees, legal expenses, and lender fees, which can impact overall profitability.

How to Overcome It:

  • Shop around and negotiate with lenders to secure the most competitive rates and terms.
  • Explore CMHC-insured financing for multi-family properties to access lower rates and higher loan-to-value ratios.
  • Consider short-term bridge financing as an interim solution if long-term rates are currently high but expected to drop.

3. Market Volatility and Economic Uncertainty

The Challenge: Fluctuations in interest rates, inflation, and economic downturns can make lenders more cautious and impact the availability of commercial real estate loans.

How to Overcome It:

  • Diversify your financing sources to reduce reliance on a single lender.
  • Secure fixed-rate loans to protect against interest rate increases.
  • Conduct thorough market research and risk analysis before investing to ensure the project remains viable under different economic conditions.

4. Property Valuation and Loan-To-Value (LTV) Ratio Limitations

The Challenge: Lenders base loan amounts on the property’s appraised value, and if the valuation comes in lower than expected, it can reduce borrowing capacity and require a larger down payment.

How to Overcome It:

  • Ensure the property is well-maintained and has strong financials before appraisal.
  • Provide detailed financial statements, lease agreements, and market comparables to justify a higher valuation.
  • If the valuation is too low, consider negotiating seller financing or bringing in additional equity partners.

5. Lengthy Approval and Funding Processes

The Challenge: Commercial mortgage approvals can take weeks or even months due to detailed underwriting processes, property appraisals, and legal reviews, causing delays in closing deals.

How to Overcome It:

  • Prepare all necessary documents in advance, including financial statements, business plans, and property details.
  • Work with an experienced commercial mortgage broker to streamline the process and expedite approvals.
  • Consider alternative financing solutions, such as private lenders, who can provide quicker funding options when needed.

Why Work With Me?

Securing commercial mortgage financing requires expertise, market knowledge, and strong lender relationships. As a seasoned commercial mortgage broker, I specialize in helping investors and business owners secure the best financing solutions for their projects. Whether you need funding for a multi-unit residential development, office space, or industrial property, I am here to guide you every step of the way.

Ready to take the next step in your real estate investment journey? Contact me today to discuss your goals and find the perfect apartment building for your portfolio. Together, we can turn your investment dreams into reality.

I look forward to hearing from you in regard to your mortgage needs.

Patrick

p.s- You can click on this link to start the process whenever you are ready. Schedule your meeting with me here.

p.s.s- I should tell you that I am licensed in Nova Scotia Brokerage (2024-3000179) Broker (2024-3000180), Ontario(M18001555) & in British Columbia(BCFSA #504098).

p.s.s.s You can download my new mortgage app here

Don’t miss out on this opportunity to secure the best financing terms for your next multi-unit development. Contact me today!

With my experience and industry connections, I’ll ensure you get the most competitive terms to make your commercial property investment a success.