Tag Archive for: Closing costs

Confirmed live. Title: The Home Inspection Clause Buyers Waive to Win — And What It Actually Costs Them

In a competitive market, waiving the inspection clause can make an offer look stronger to a seller — no conditions, no delays, nothing standing in the way of closing. It can also mean absorbing whatever’s wrong with the house entirely on your own, with no way back out.

What the clause actually does

An inspection clause gives you a defined window, after your offer is accepted, to have a licensed inspector go through the property. If something serious turns up — foundation issues, knob-and-tube wiring, a failing roof — the clause gives you the right to negotiate a price reduction, ask the seller to fix it, or walk away from the deal entirely with your deposit protected.

Waive it, and none of that exists. You’re committed the moment your offer is accepted, sight unseen on anything beyond what you could tell by walking through it yourself.

A waived inspection clause doesn’t make the problems in a house disappear. It just decides, in advance, that they’re entirely your problem to solve.

Why buyers do it anyway

In a hot market with multiple competing offers, a clean offer with no conditions genuinely does look more attractive to a seller than one with an inspection contingency attached. Buyers waive it because they believe it’s the difference between winning the house and losing it to someone else.

Sometimes that’s true. But it’s a real trade, not a free move — you’re giving something up to make your offer more competitive, and it’s worth being honest with yourself about what that something actually is.
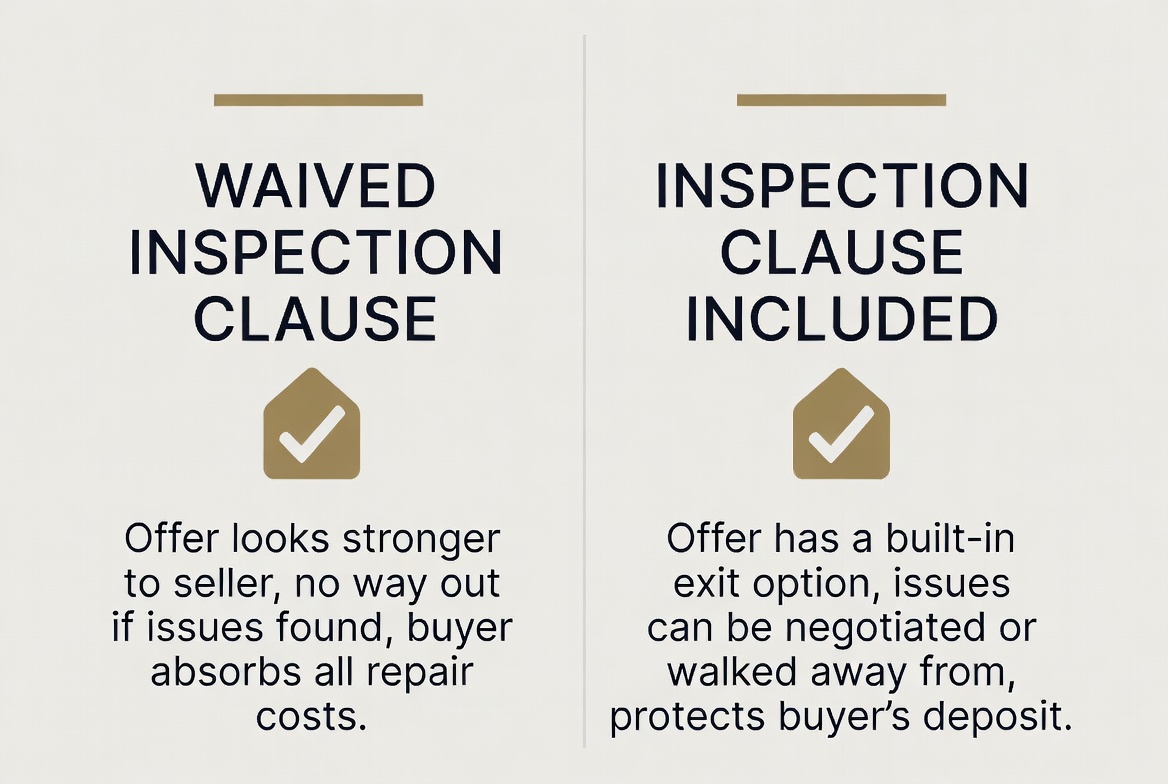
Comparison graphic showing Waived Inspection Clause meaning offer looks stronger to seller but no way out if issues found and buyer absorbs all repair costs, versus Inspection Clause Included meaning offer has a built-in exit option, issues can be negotiated or walked away from, and protects buyer's deposit

What it can actually cost you

Foundation repairs, knob-and-tube rewiring, oil tank remediation, roof replacement — these aren’t small numbers, and they don’t show up on a walkthrough. Buyers who waive the clause and then discover a serious issue after closing have no recourse; the cost lands entirely on them, often within the first year of ownership.

Is there a middle ground?

Sometimes. A pre-offer inspection — done before you submit, on your own schedule, outside the pressure of a bidding war — can let you make an informed decision about whether to waive the clause on that specific property, rather than waiving it blind on every offer as a blanket strategy.

Bottom line

Waiving the clause can be the right call in the right circumstances — but it should be a deliberate decision about a specific property, not a reflexive move to look competitive. Know what you’re actually giving up before you give it up.

Don’t waive your protection to win a bidding war. Call 902-465-5533 — I answer.
Don't waive your protection to win a bidding war. Patrick Sawler, Principal Broker, Craigburn Capital, craigburn.com. NS Brokerage 2025-3000179, Broker 2025-3000180, ON M23006699

The Land Transfer Tax Rebate Nobody Tells First-Time Buyers About

Here’s a gap that catches a lot of first-time buyers off guard, especially if they’ve done some general research online: land transfer tax rebates exist — but not everywhere, and not the same way. Where you’re buying determines whether you get real money back at closing, or nothing at all.

The rebate that actually exists — and where

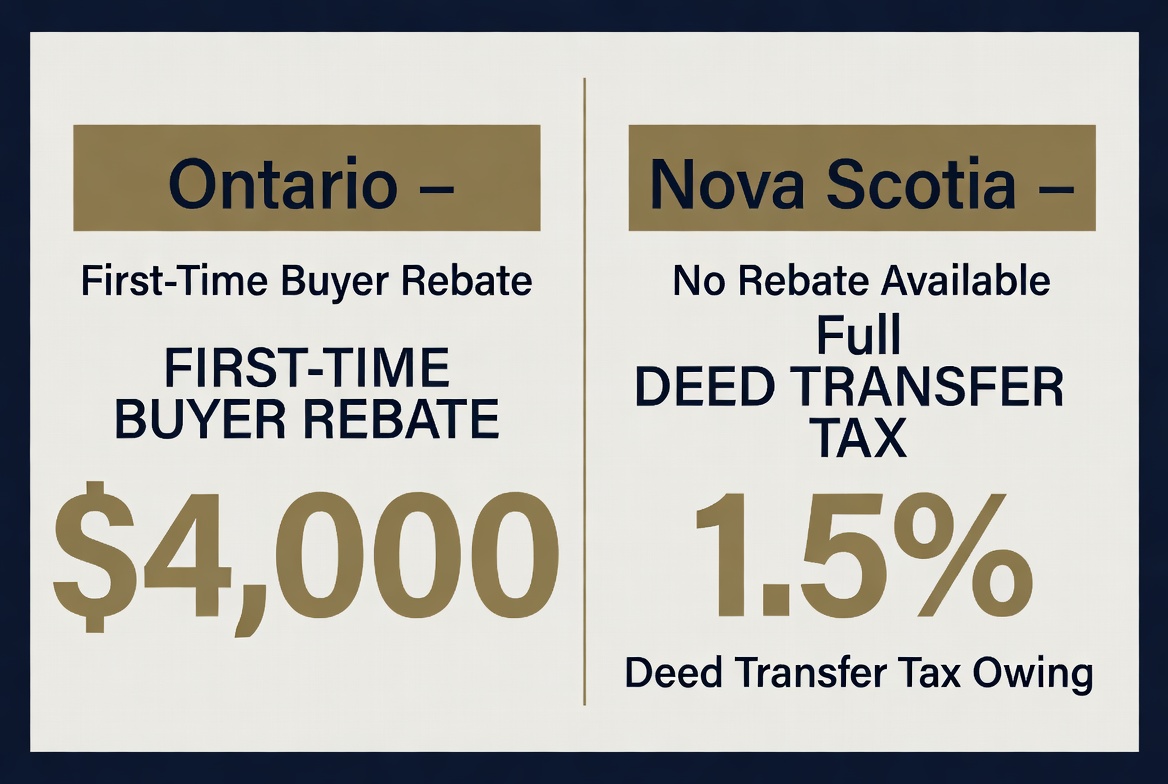
Ontario has a genuine Land Transfer Tax Rebate for first-time home buyers, worth up to $4,000. For a typical first-time purchase, that can wipe out the land transfer tax owing almost entirely on homes up to roughly $368,000, and meaningfully reduce it above that. It’s a real credit applied directly at closing — not a tax deduction you claim later.

A lot of the “land transfer tax rebate” content online is written for an Ontario or national audience. If you’re buying in Nova Scotia, most of it simply doesn’t apply to you.

What Nova Scotia buyers actually get

Nova Scotia has no equivalent provincial first-time buyer rebate on its deed transfer tax. The deed transfer tax itself is set municipally — in Halifax Regional Municipality, it’s 1.5% of the purchase price, paid in full regardless of whether it’s your first home or your fifth. There’s no rebate program that offsets it for first-time buyers the way Ontario’s does.

Comparison graphic showing Ontario First-Time Buyer Rebate up to $4,000 next to Nova Scotia No Rebate Available, full 1.5 percent deed transfer tax owing

Why this matters for your closing budget

If you’ve read general advice suggesting you’ll get some of your land transfer tax back as a first-time buyer, and you’re purchasing in Nova Scotia, that assumption can leave a real gap in your closing cost budget. On a $500,000 Halifax purchase, that’s $7,500 in deed transfer tax with nothing coming back — money that needs to be accounted for up front, not assumed away.

What to do instead of assuming

Don’t rely on generic online guidance for a cost this specific to location. Before you budget for closing day, confirm the actual deed transfer tax rate for your specific municipality, and whether any rebate genuinely applies to your province — not just the province the article you read was written for.

Know your real closing costs before you budget. Call 902-465-5533 — I answer.

Know your real closing costs before you budget. Patrick Sawler, Principal Broker, Craigburn Capital, craigburn.com. NS Brokerage 2025-3000179, Broker 2025-3000180, ON M23006699