Tag Archive for: First time buyers

What a Bruised Credit Score Actually Costs You on a Mortgage

A “bruised” credit score — something in the 600 to 650 range — doesn’t shut the door on getting a mortgage. But it does change the math, sometimes by tens of thousands of dollars over the life of the loan, and most people never see the actual number, just a vague sense that their rate will be “a bit higher.”

What actually changes at a lower score

Lenders price risk. A lower credit score signals more risk, and that shows up as a higher rate offered, and fewer lenders willing to approve the file at all. Some traditional lenders simply won’t go below certain thresholds, which narrows your options before you even get to the rate conversation.

The gap between a strong score and a bruised one isn’t a rounding error. Applied across a 25-year amortization, it’s real money — often tens of thousands of dollars in additional interest.

Why the CMHC part gets misunderstood

A common assumption is that a score below 680 or so disqualifies you from CMHC-insured financing entirely. That’s not accurate — CMHC has approved insured mortgages well below that threshold, including scores in the 600s, depending on the rest of the file. The real constraint usually isn’t a hard credit cutoff — it’s the combination of score, income stability, and debt load that a lender is weighing together.
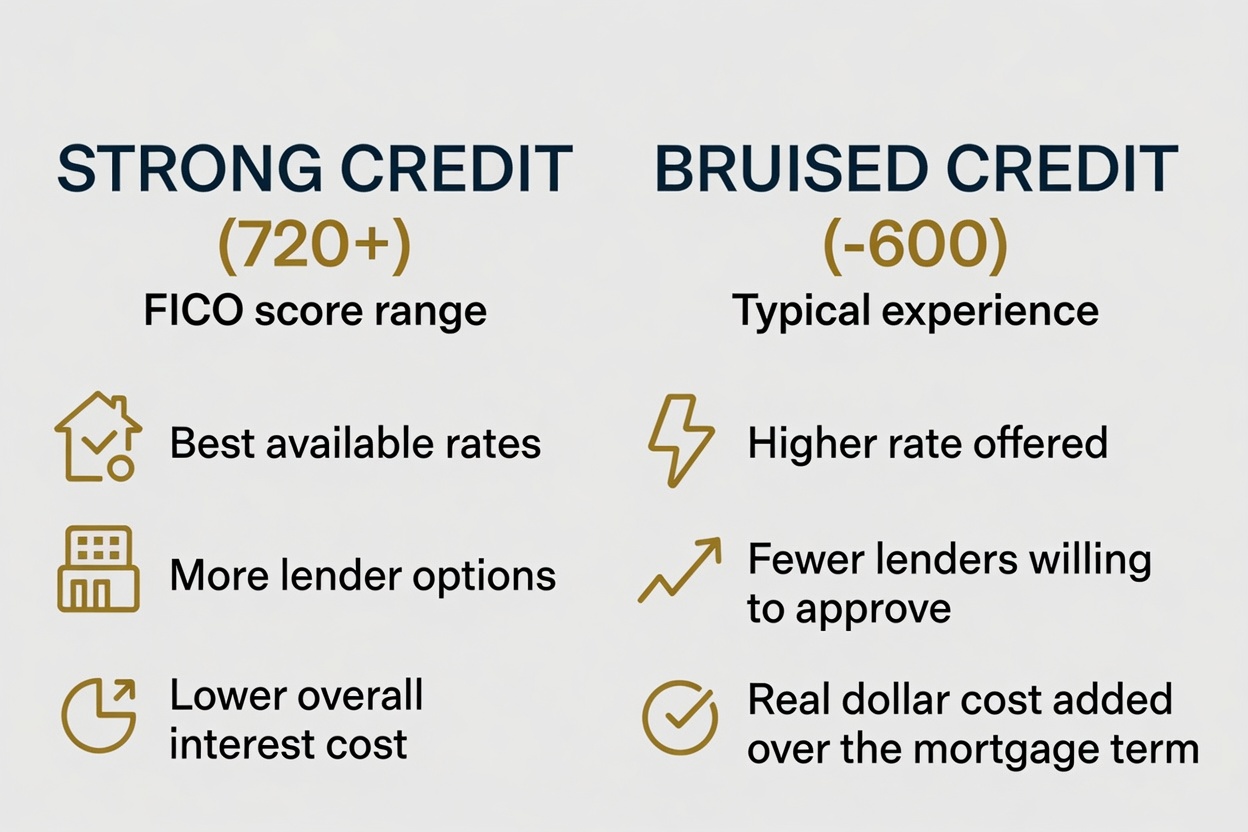
Comparison graphic showing Strong Credit 720 plus FICO score range with best available rates, more lender options, lower overall interest cost, versus Bruised Credit under 600 typical experience with higher rate offered, fewer lenders willing to approve, real dollar cost added over the mortgage term

What you can actually do about it

  • Know your real number before you shop. A pre-approval conversation should include an honest look at your credit, not just an assumed range.
  • Understand which lenders actually work with your score. Not every lender has the same appetite — a broker who knows the lender landscape can steer you toward the ones that fit, rather than the ones that reject you outright.
  • Consider whether a short delay is worth it. Sometimes a few months of deliberate credit repair meaningfully changes the rate you’re offered — worth knowing before you commit to today’s number.

Bottom line: a bruised score is a real factor, not a life sentence. The mistake is assuming the worst without actually finding out where you stand and what it changes — that’s a conversation worth having before you start house hunting, not after an offer falls through.

Your credit score is a number, not a verdict. Call 902-465-5533 — I answer.
Your credit score is a number, not a verdict. Patrick Sawler, Principal Broker, Craigburn Capital, craigburn.com. NS Brokerage 2025-3000179, Broker 2025-3000180, ON M23006699

Confirmed live. Title: The Home Inspection Clause Buyers Waive to Win — And What It Actually Costs Them

In a competitive market, waiving the inspection clause can make an offer look stronger to a seller — no conditions, no delays, nothing standing in the way of closing. It can also mean absorbing whatever’s wrong with the house entirely on your own, with no way back out.

What the clause actually does

An inspection clause gives you a defined window, after your offer is accepted, to have a licensed inspector go through the property. If something serious turns up — foundation issues, knob-and-tube wiring, a failing roof — the clause gives you the right to negotiate a price reduction, ask the seller to fix it, or walk away from the deal entirely with your deposit protected.

Waive it, and none of that exists. You’re committed the moment your offer is accepted, sight unseen on anything beyond what you could tell by walking through it yourself.

A waived inspection clause doesn’t make the problems in a house disappear. It just decides, in advance, that they’re entirely your problem to solve.

Why buyers do it anyway

In a hot market with multiple competing offers, a clean offer with no conditions genuinely does look more attractive to a seller than one with an inspection contingency attached. Buyers waive it because they believe it’s the difference between winning the house and losing it to someone else.

Sometimes that’s true. But it’s a real trade, not a free move — you’re giving something up to make your offer more competitive, and it’s worth being honest with yourself about what that something actually is.

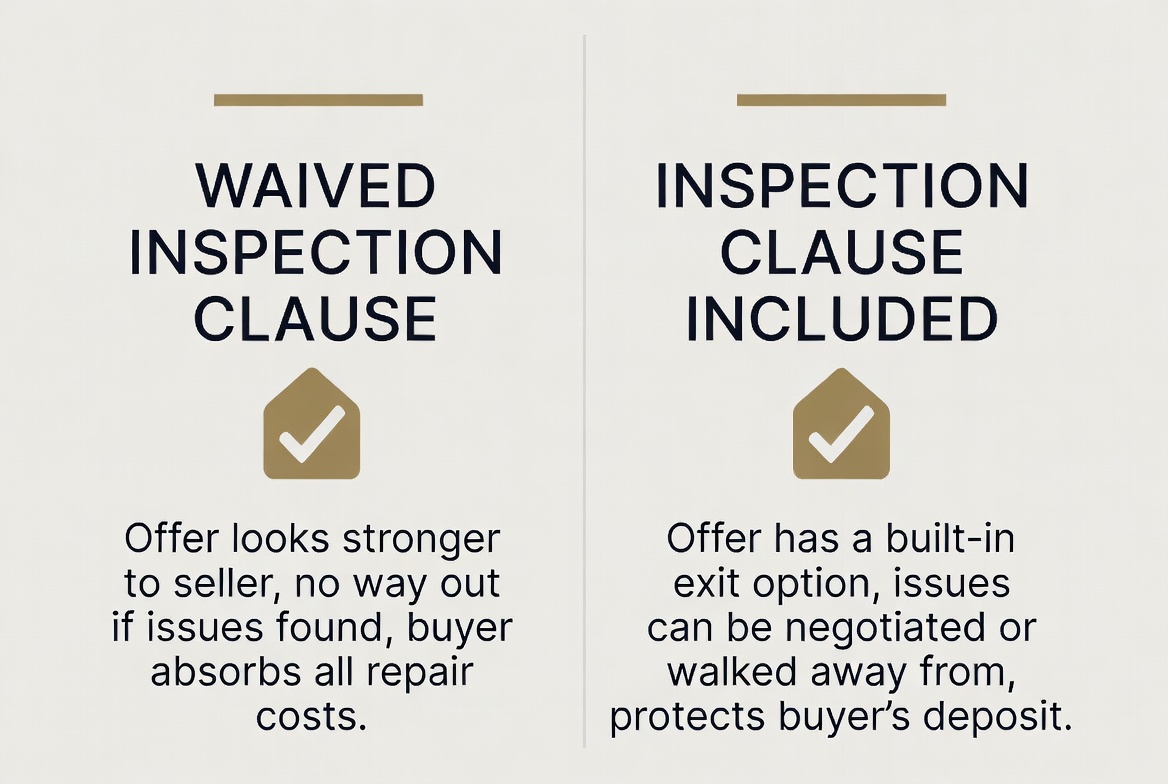
Comparison graphic showing Waived Inspection Clause meaning offer looks stronger to seller but no way out if issues found and buyer absorbs all repair costs, versus Inspection Clause Included meaning offer has a built-in exit option, issues can be negotiated or walked away from, and protects buyer's deposit

What it can actually cost you

Foundation repairs, knob-and-tube rewiring, oil tank remediation, roof replacement — these aren’t small numbers, and they don’t show up on a walkthrough. Buyers who waive the clause and then discover a serious issue after closing have no recourse; the cost lands entirely on them, often within the first year of ownership.

Is there a middle ground?

Sometimes. A pre-offer inspection — done before you submit, on your own schedule, outside the pressure of a bidding war — can let you make an informed decision about whether to waive the clause on that specific property, rather than waiving it blind on every offer as a blanket strategy.

Bottom line

Waiving the clause can be the right call in the right circumstances — but it should be a deliberate decision about a specific property, not a reflexive move to look competitive. Know what you’re actually giving up before you give it up.

Don’t waive your protection to win a bidding war. Call 902-465-5533 — I answer.

Don't waive your protection to win a bidding war. Patrick Sawler, Principal Broker, Craigburn Capital, craigburn.com. NS Brokerage 2025-3000179, Broker 2025-3000180, ON M23006699

Self-Employed? Your Tax Return Might Be Working Against You!

Every write-off you claim to lower your tax bill also lowers the income a lender sees when you apply for a mortgage. The same strategy that saves you money every April can shrink your borrowing power every other month of the year.

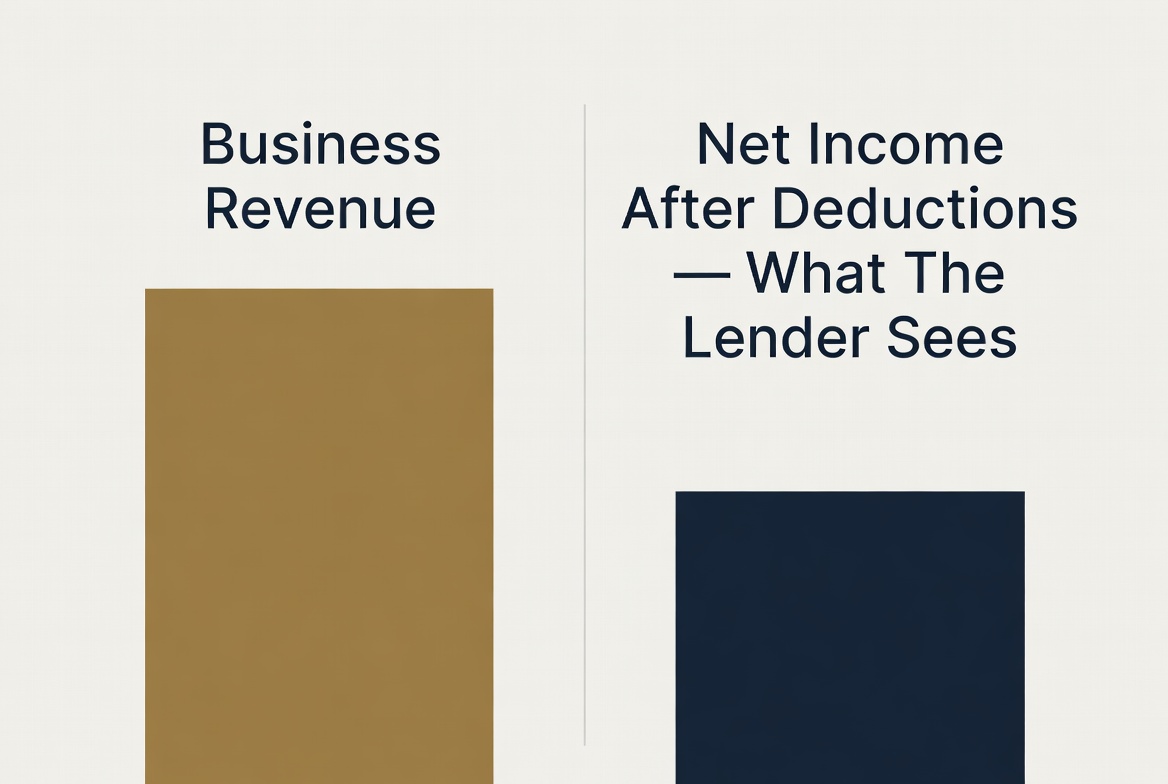
Lenders don’t look at your revenue — they look at your net income, after every deduction your accountant found. Bring in $120,000 but write off $50,000? A lender sees $70,000. That’s the number your mortgage gets sized against.

The lower your reported income, the lower your tax bill — and the lower your mortgage approval. You can’t fully optimize for both at once.

What lenders actually look at

Most want two years of Notice of Assessment and full T1 Generals, then average your net income across both. If your income’s grown fast and you write off aggressively, that average can look surprisingly low next to what you actually take home.

Comparison graphic showing Business Revenue at a high number on one side, and Net Income After Deductions at a much lower number on the other side, labeled What The Lender Sees

What you can do about it

  • Plan two years ahead, not two months. Talk to your accountant about the trade-off between minimizing tax now and maximizing qualifying income later.
  • Look at stated-income or alternative lending programs built for self-employed borrowers.
  • Consider private lending — often weighs equity and overall picture over a rigid two-year average.

Bottom line: there’s no single right answer — it’s a genuine trade-off. The mistake is not knowing it exists until you’re mid-application. Have the conversation with your accountant and your broker before you need the mortgage, not after.

Self-employed and thinking about buying? Let’s talk before tax season. Call 902-465-5533 — I answer.

Self-employed and planning to buy? Let's talk before tax season. Patrick Sawler, Principal Broker, Craigburn Capital, craigburn.com. NS Brokerage 2025-3000179, Broker 2025-3000180, ON M23006699