Tag Archive for: Private Mortgage Nova Scotia

The Closing Date That Almost Fell Through (And What Actually Saved It)

The Closing Date That Almost Fell Through (And What Actually Saved It)

When you need a quick closing mortgage, the fix isn’t a faster bank. Banks don’t move faster under pressure — they move slower, because more moving parts means more that can hold things up. When timing is the priority, private financing works because it skips layers of institutional underwriting a bank has to go through no matter how good your file is. That’s not a shortcut. It’s a different process, built for a different problem.

Here’s what that actually looks like.

A buyer comes to me two weeks before closing. Their bank financing fell through — maybe an appraisal came in low, maybe underwriting flagged something last-minute, maybe their file just got stuck in a queue. Whatever the reason, the outcome is the same: a firm closing date, no financing, and a seller who isn’t going to wait.

A bank can’t move on that timeline. Not because their people aren’t good — because the process itself has steps that take time by design: multiple underwriting reviews, committee approvals, conditions that stack up one after another. None of that is a flaw. It’s just not built for two weeks.

Private financing is built differently. The lending decision comes down to fewer, clearer things: the equity in the property, and a workable exit strategy. When those two things check out, the file can move in days instead of weeks — not because anyone’s cutting corners, but because there are simply fewer steps to move through.
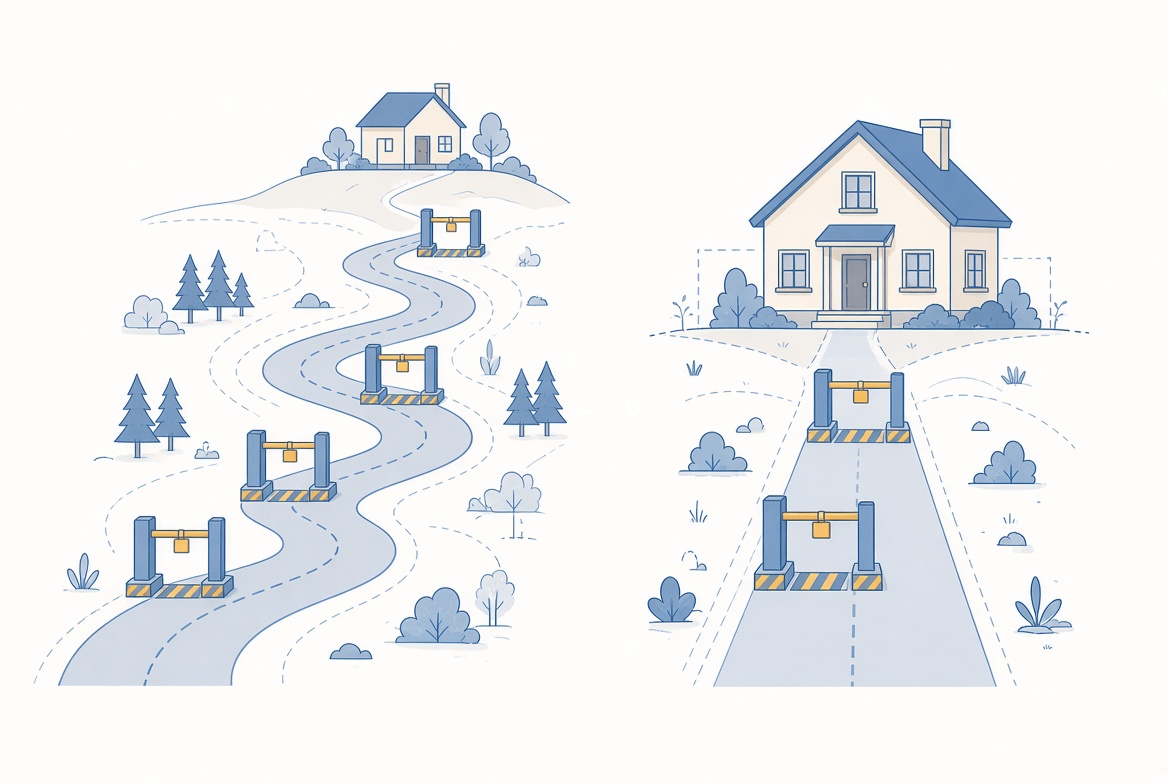
Two paths to the same house — one long and winding through several gates, one short and direct through fewer gates

That’s the piece people miss. Fast isn’t risky here. Fast is what happens when the process is simpler by design, not rushed under pressure.

What actually saved that closing:

  • A clear equity position — enough room in the property value that the lender’s risk was straightforward to assess
  • A real exit strategy — a plan to refinance with a conventional lender once the immediate issue was resolved, not just “we’ll figure it out later”
  • A file put together properly from day one — appraisal, application, and payout details all lining up cleanly, so there was nothing to go back and question

When those three things are in place, private financing isn’t a last resort. It’s just the right tool for a timing problem, the same way a bank mortgage is the right tool when timing isn’t the constraint.

If a deal is on the clock and the usual path isn’t going to make it, that’s exactly the kind of file I want to see.
A hand holding an hourglass, sand nearly settled

When an immediate closing is your most important priority, reach out — the sooner, the more room we have to work with.

I look forward to hearing from you in regard to your mortgage needs.
902-465-5533. I answer.
Patrick

p.s- You can click on this link to start the process whenever you are ready. Schedule your meeting with me here.
p.s.s- I should tell you that I am licensed in Nova Scotia Brokerage (2025-3000179) Broker (2025-3000180), Ontario (M23006699).
p.s.s.s- You can download my new mortgage app here

Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone.

Ready to have a real conversation? Call 902-465-5533 or start your application here.

Private Mortgages in Nova Scotia: Why Your Address Can Matter More Than Your Credit Score

A private mortgage is a loan from a non-bank lender, usually secured against a property’s equity rather than a borrower’s income or credit history. People typically need one when a bank says no — credit issues, foreign or irregular income, self-employment without conventional documentation, or a property that’s hard to finance conventionally.

Here’s the part almost nobody explains clearly: even once you know you need to look outside a bank, where your property sits on a map can close doors that have nothing to do with your income or credit score at all.

Alt-B lenders exist specifically to say yes when a bank says no — but many only lend in populated, marketable centres: HRM core communities, Truro, Sydney, the Annapolis Valley. A genuinely rural Nova Scotia property can be excluded from that entire category, regardless of how strong the file otherwise looks.

So what works if you’re rural? This is where a private mortgage earns its reputation as the flexible option — most private lenders don’t carry the same geographic restrictions. But they come with a trade-off people are often uneasy about: they’re usually interest-only, so the balance doesn’t shrink on its own the way a bank mortgage would.

Here’s what’s worth knowing: that doesn’t have to mean pure interest for the whole term. Many private lenders will structure a mortgage to allow extra payments toward principal whenever you’re able to make them, with the remaining balance due at term’s end — a real way to chip away at what you owe, on your own timeline.

Read the full breakdown — including a side-by-side comparison of how bank, Alt-B, and private lending actually differ — on [MortgageClarity.ai].

Thinking through your options? I’d be glad to walk through what’s realistic for your specific property and situation.

I look forward to hearing from you in regard to your mortgage needs.

Patrick

p.s- You can click on this link to start the process whenever you are ready. Schedule your meeting with me here.

p.s.s- I should tell you that I am licensed in Nova Scotia Brokerage (2025-3000179) Broker (2025-3000180), Ontario(M23006699).

p.s.s.s You can download my new mortgage app here

Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone.

Ready to have a real conversation? Call 902-612-2688 or start your application here

Can I get an Alt-B mortgage on a rural property in Nova Scotia?

Usually not. Most Alt-B lenders only serve populated, marketable centres — HRM core communities, Truro, Sydney, and the Annapolis Valley. A genuinely rural property is often excluded from that category entirely, regardless of how strong the rest of the file looks.

Are private mortgages always interest-only?

Typically, yes — but not always in practice. Many private lenders will structure a mortgage to allow extra payments toward the principal whenever you’re able to make them, with the remaining balance due at the end of the term. That gives you a real way to pay down what you owe, even without qualifying for a conventional amortizing product.