
Your Mortgage Renewal Is a Coin Flip Right Now

I’ve had two renewal conversations this month that could not have gone more differently.
One client called me nervous, bracing for bad news. Her payment is dropping. Another client walked in relaxed, assuming his renewal would be routine. His payment is about to jump by almost 40%.
Neither of them saw it coming, in either direction. Mortgage renewals in 2026 aren’t a slow, predictable slide in one direction — it’s a split. Homeowners renewing right now are landing on two very different sides of a coin flip, and most have no idea which side they’re on until the letter shows up.
Why the split is happening
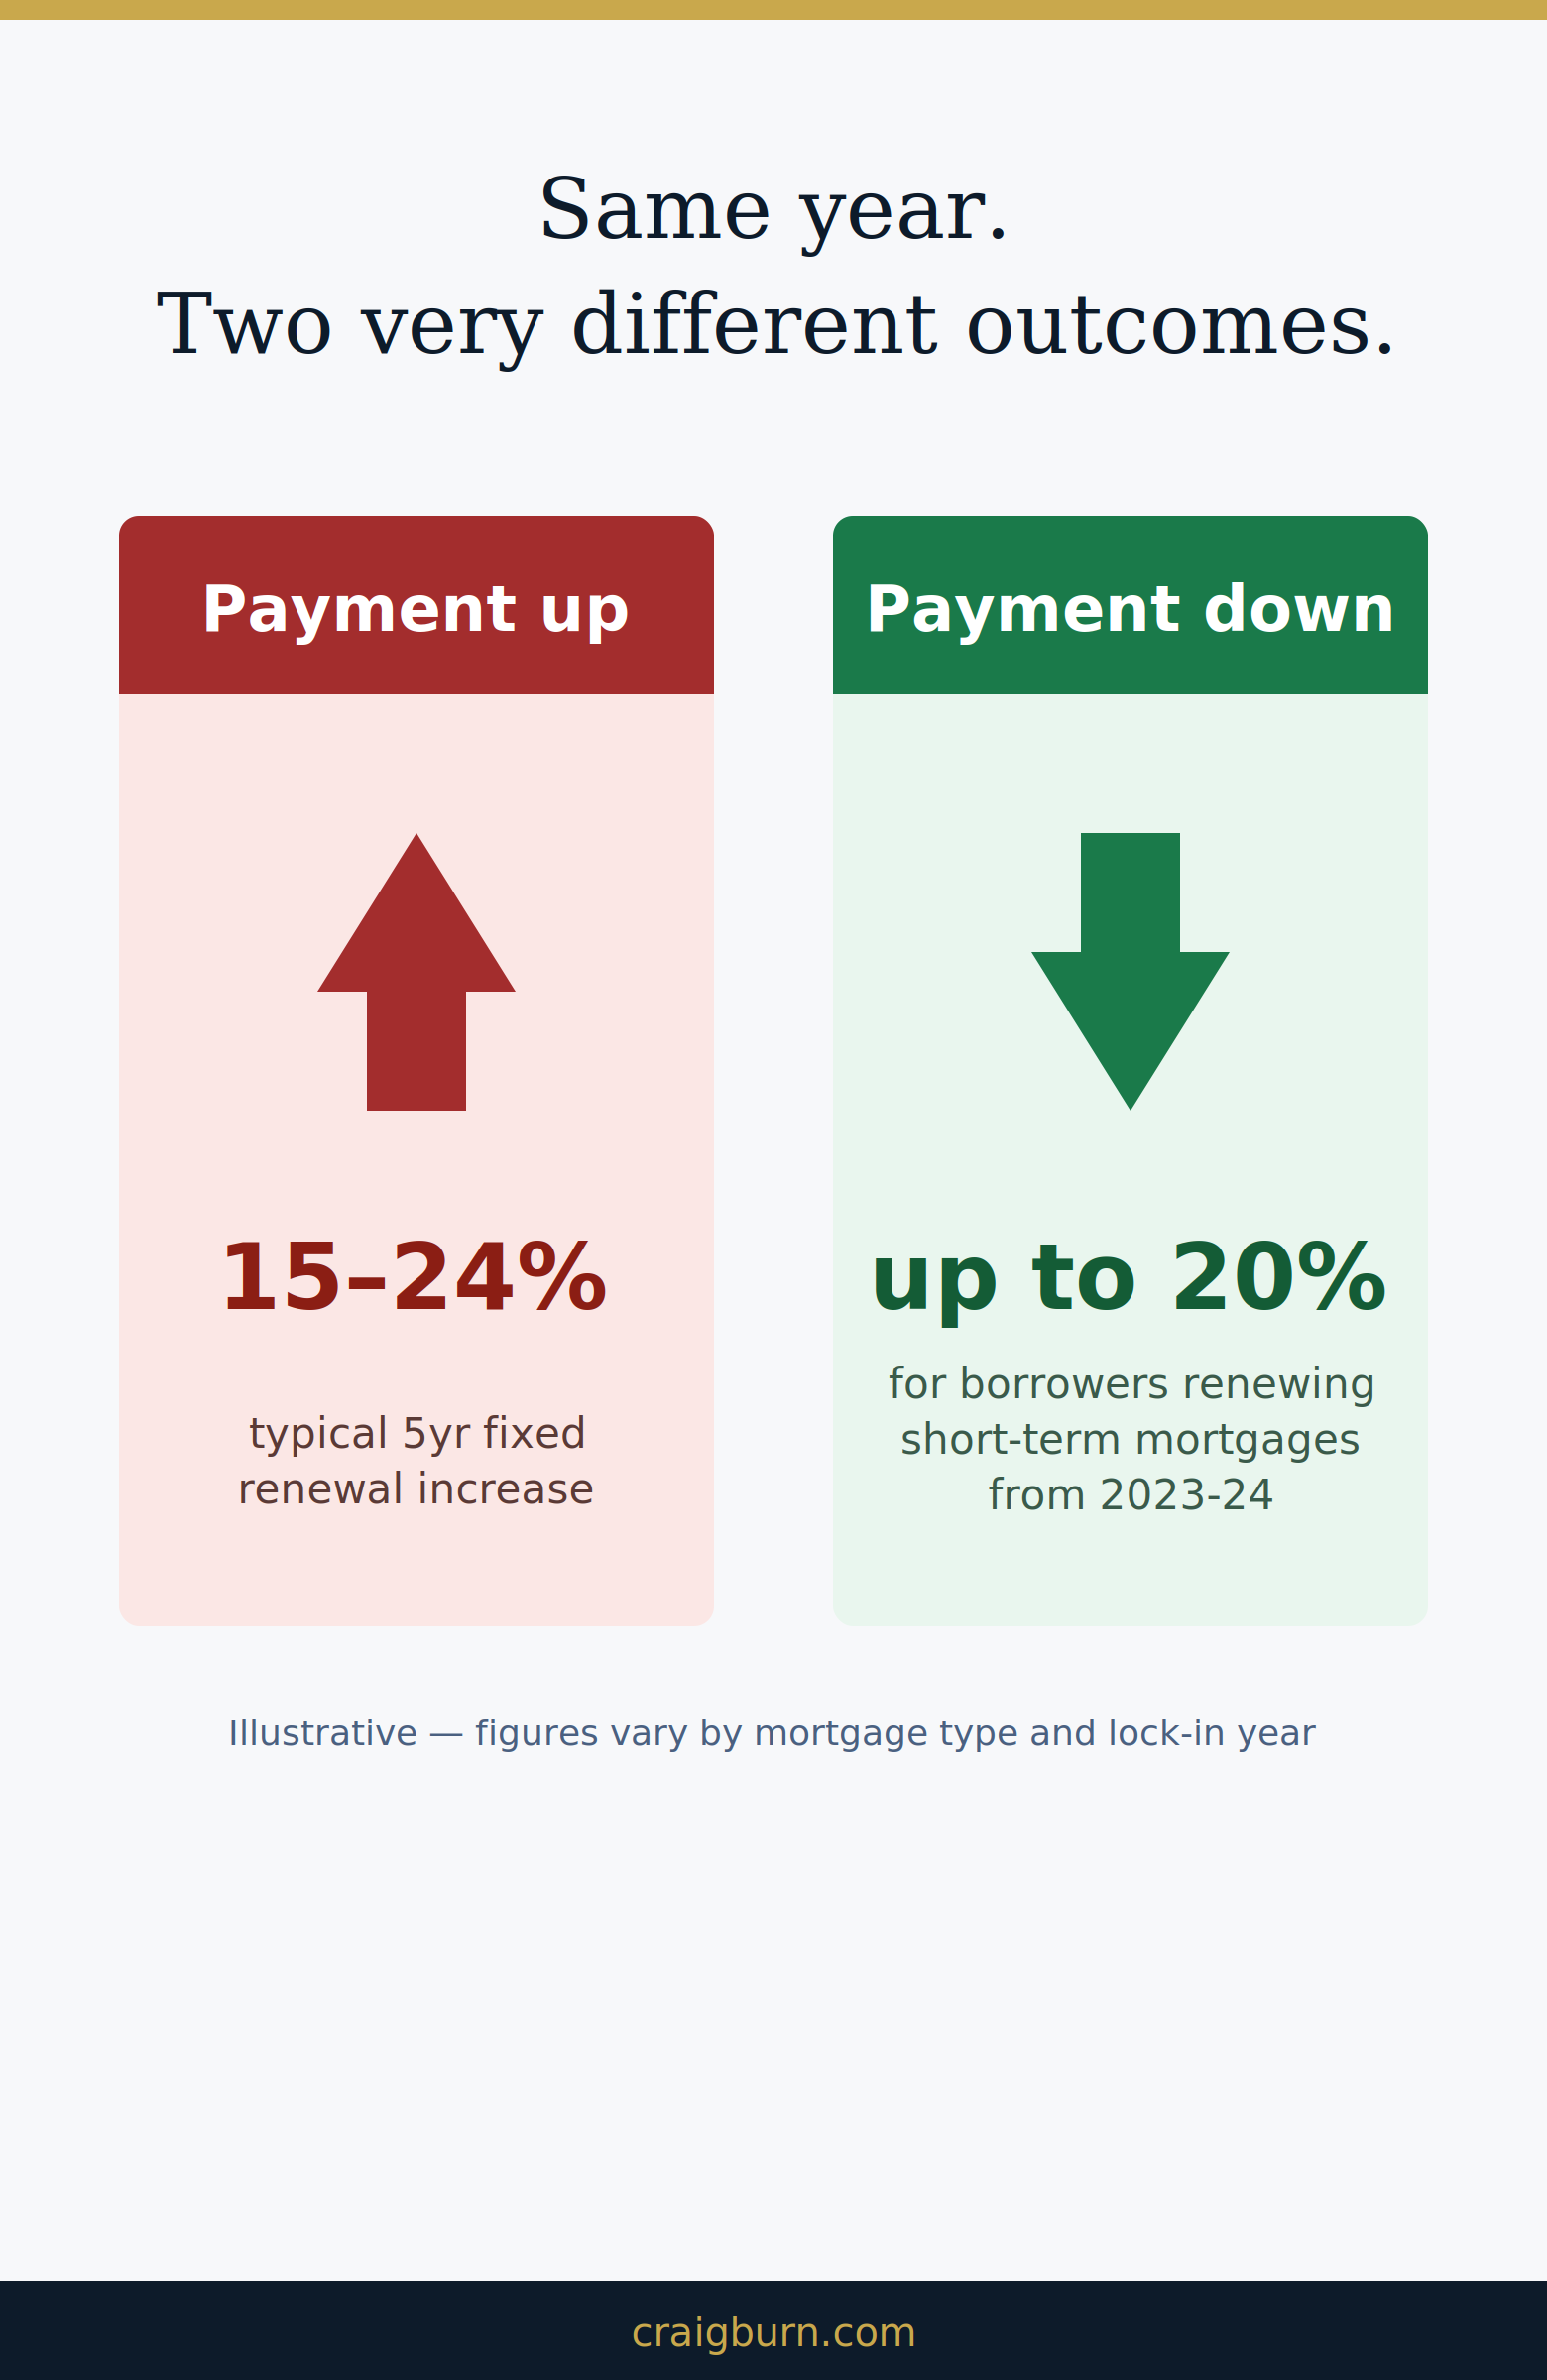
If you locked into a 5-year fixed rate back when rates were near rock-bottom, you’re likely renewing into something noticeably higher — some borrowers are seeing increases in the 15–24% range, and in pricier markets that can hit 40%.
But if you took a shorter-term mortgage during the 2023–24 rate-hike cycle and you’re rolling over now, you could actually see your payment drop.
Same year. Same Bank of Canada. Two completely different outcomes, depending on what you signed and when.
Before you sign anything, check this
- What you actually signed — fixed or variable, and what term.
- Your renewal date against your rate — 2020–2022 lock-ins under 3% are the group facing the sharper resets.
- Don’t sign the bank’s letter on reflex — it’s their offer, not the market, and rarely their best rate.
Whichever side of the coin you’re on, your lender won’t shop the market for you. A five-minute call before you sign can save real money either way — a better rate, or an incentive that offsets your closing costs.
Want the full breakdown, including how to read your renewal letter line by line? Read the complete article on MortgageClarity.ai.