Four Easy Payments. One Hard Conversation With Your Underwriter.
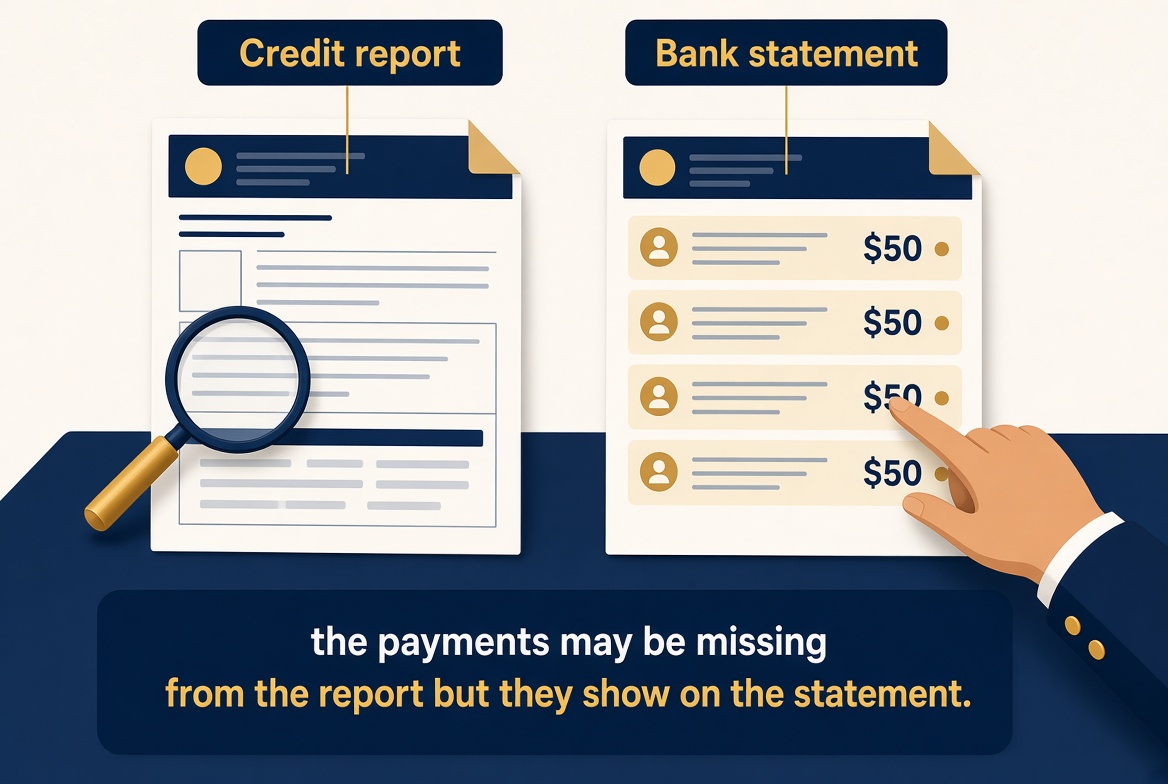
Does buy now pay later affect mortgage approval in Canada? It can, and not always the way people expect. One small plan paid on time is rarely the problem. A stack of them is. Some plans show up on your credit report, and all of them show up on your bank statements, so a lender who reads your file can see them either way.
Black Friday lands on November 27, and somewhere this week a checkout screen is going to offer you four easy payments of $50. It feels like nothing. For a lender, four easy payments can turn into one hard conversation, so here is how it works.
Does buy now pay later show up on a Canadian credit report?
Sometimes. Reporting is voluntary and it varies by provider. Equifax Canada has said its reports have started to include data from some of these providers, and TransUnion Canada has been working toward the same. When The Canadian Press asked in 2025, Klarna said it does not share data with Canadian credit agencies and Afterpay said it provides none, while Affirm said it aimed to bring its U.S. reporting to Canada. MoneySense has the details.
That picture keeps changing, so do not assume your plan is invisible. Industry commentary in September 2026 described reporting as a work in progress: missed payments are more likely to show up than on-time ones, often once an account goes to collections, and some data can sit on a file without touching the score.
How does buy now pay later affect mortgage approval in Canada?
A lender is not grading you on one purchase. It is reading a pattern. Say you split a $200 purchase into four payments of $50, two weeks apart. Fine. Now say you have four of those running at once, which is easy to do over a holiday season. That is $200 leaving your account every two weeks, about $430 a month. Replace each plan as it finishes and it never stops.
Add a missed payment and it gets worse. The Financial Consumer Agency of Canada warns that late payments can bring fees, and on some plans interest on the full purchase amount from the day you bought it. Your bank can also charge a fee when a payment bounces.
On paper, a plan that is not on your credit report may not be in your debt ratios. In practice, a lender who reads your statements can still weigh it, and a pattern of stacked plans tells a story about your cash flow.
What does a lender see if it is not on my credit report?
Your bank statements. When a file includes them, the withdrawals to Klarna, Afterpay, Affirm and similar providers look like exactly what they are: regular obligations. Many files involve statements, such as a down payment history, self-employed income or a private mortgage.
Lenders also commonly check your credit again shortly before closing, so a new plan opened between approval and closing can surface at the worst possible time.
What should you do before you apply for a mortgage?
- Finish what you have. Pay off open plans before you apply, not during.
- Hold off on new ones. Skip the pay-in-four button for the months before you apply, and until your mortgage funds.
- Keep your statements clean. No bounced payments and no missed instalments.
- Tell me about every plan, including the ones you think do not count. It is far better for me to hear it from you than for an underwriter to find it.
If a missed payment has already landed in collections, it is not always the end of the road. Some files are too bruised for a bank, and a private mortgage can bridge the gap as long as you know the whole bill. I explain that in the rate on a private mortgage is only half the bill and in how much equity you need for a private mortgage.
How can a mortgage broker help with buy now pay later?
I read your file the way an underwriter will, before the underwriter does. One application, one credit pull, then I compare 45 lenders and place it where the reading is friendliest. That includes the part nobody puts on a form. If you have plans running, we sort out the timing, clear what makes sense, and then apply. And if the honest answer is to wait three months, I will tell you that.
Frequently Asked Questions
Does Afterpay or Klarna affect your credit score in Canada?
It depends on the provider, and it keeps changing. When The Canadian Press asked in 2025, Klarna said it does not share data with Canadian credit agencies and Afterpay said it provides none. Equifax Canada has said it has started to include data from some providers. Check the terms of your own plan, and remember that a lender can still see the payments on your bank statements.
Should you stop using buy now pay later before applying for a mortgage?
It is a good idea to pay off the plans you have and to avoid opening new ones in the months before you apply, and until your mortgage funds. One plan paid off on time is rarely a problem, but lenders commonly check your credit and your statements again before closing.
Can you get a mortgage if you have missed buy now pay later payments?
Often, yes, but it depends on the whole file. A missed payment that goes to collections can appear on your credit report and make approval harder with a bank. A broker can look at lenders that weigh the full picture, and in some cases private financing can bridge the gap while you rebuild.
Do you have to tell your mortgage broker about buy now pay later?
Yes. Tell your broker about every plan, even the ones you have paid off. Many do not show on a credit report, but they can show on your bank statements, and it is far better for your broker to know first than for an underwriter to find out.
This post is general information, not financial advice. Lender policies, credit reporting practices and approvals vary, and all financing is subject to lender approval.
Buying or renewing and want to know what fits you? Send me your application and I will lay out your options.
I look forward to hearing from you in regard to your mortgage needs.
902-465-5533. I answer.
Patrick
p.s. Ready to start? Apply here: https://craigburn-capital.mtg-app.com
p.s. Prefer to talk it through first? Book a time with me here: Schedule a call
p.s. FSRA Principal Broker License #M23006699, Craigburn Capital. NS Brokerage 2026-3000179, NS Broker 2026-3000180.
p.s. Get the Craigburn mortgage app: https://craigburn-capital.mtg-app.com
Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone. Service aussi disponible en français.
Call 902-465-5533 or start your application today.