No. A property assessment is not the same as market value, and it is not what a lender uses to size your mortgage. In Nova Scotia, PVSC estimates market value as of a past date, and then the Capped Assessment Program can hold your tax bill below even that number. If you are buying, selling or refinancing, treat the assessment as a rough reference, not a price.
Is my property assessment the same as market value in Nova Scotia?
Not quite. Under the Nova Scotia Assessment Act, PVSC assesses property at market value, meaning the price it would be expected to sell for on a given date in a competitive, open market. The key words are “a given date.” According to PVSC, the 2026 assessment reflects market value as of January 1, 2025, with property characteristics recorded as of December 1, 2025. It is a mass appraisal across hundreds of thousands of properties, not an appraiser walking through your home.
A real sale happens on today’s date, with today’s competing offers and your actual condition and upgrades. That is why a home can sell well above or below its assessment.
Why can my taxable assessment be lower than my assessed value?
Because of the Capped Assessment Program (CAP). Each year your capped assessment is the previous capped amount plus the Nova Scotia CPI rate, and your taxable assessment is the lower of the assessed value and the capped value. For 2026 the CAP rate is 2.6%.
To qualify, a property generally needs to be at least 50% owned by a Nova Scotia resident, be residential with fewer than four units, be owner-occupied if it is a condominium, and have been owned for at least a year (or have stayed in the family).
What happens to the cap when a home is sold?
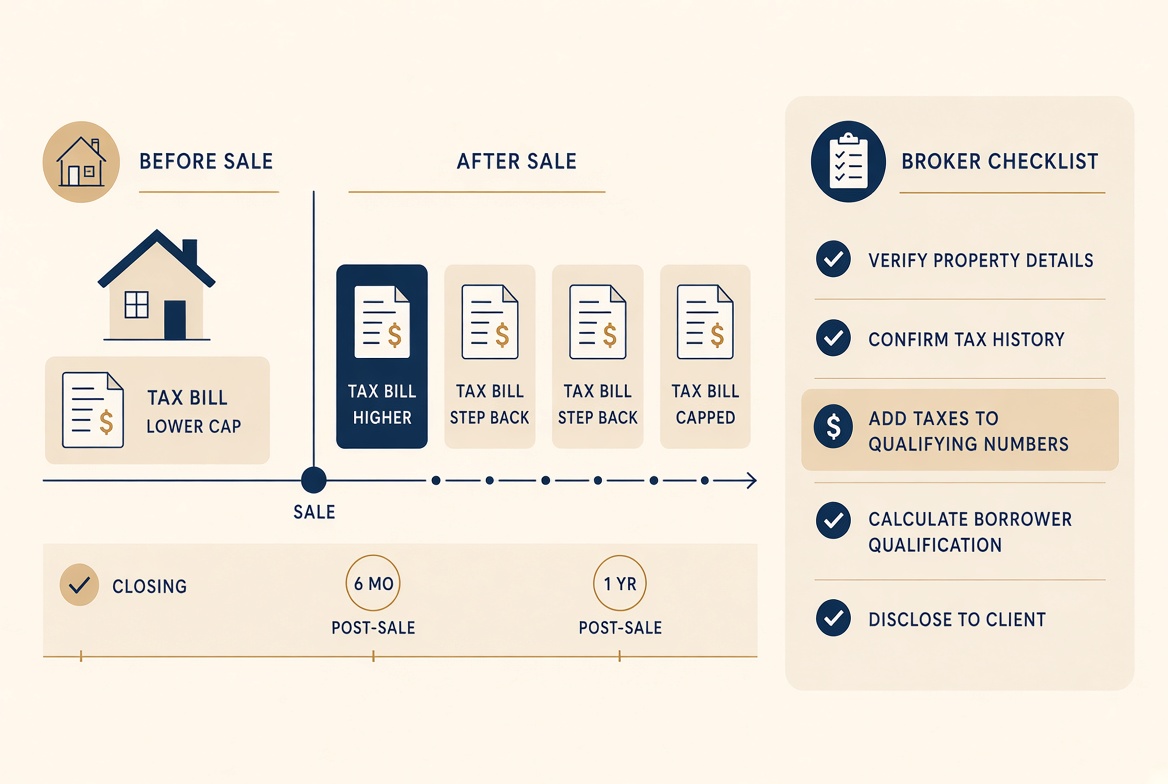
The cap is removed for the year after a non-family sale. If the new owner is eligible, the cap calculation restarts the following year. That means the new owner’s assessment can be higher than the seller’s was, and the property tax bill the buyer saw on the listing may not be the bill they actually receive. PVSC’s own example: a non-family purchase in June 2023 means no cap in January 2024, with the cap applying again in January 2025 if the other criteria are met.
Budget for that gap before you finalize your numbers, because property tax is part of how lenders calculate what you can afford.
Do lenders use the assessment to decide how much I can borrow?
Typically lenders rely on the purchase price or their own appraisal to set the value, not the tax assessment. The assessment mainly matters through the property tax amount, which is part of your monthly obligations. A high assessment does not raise your borrowing power, and a low one does not cap it.
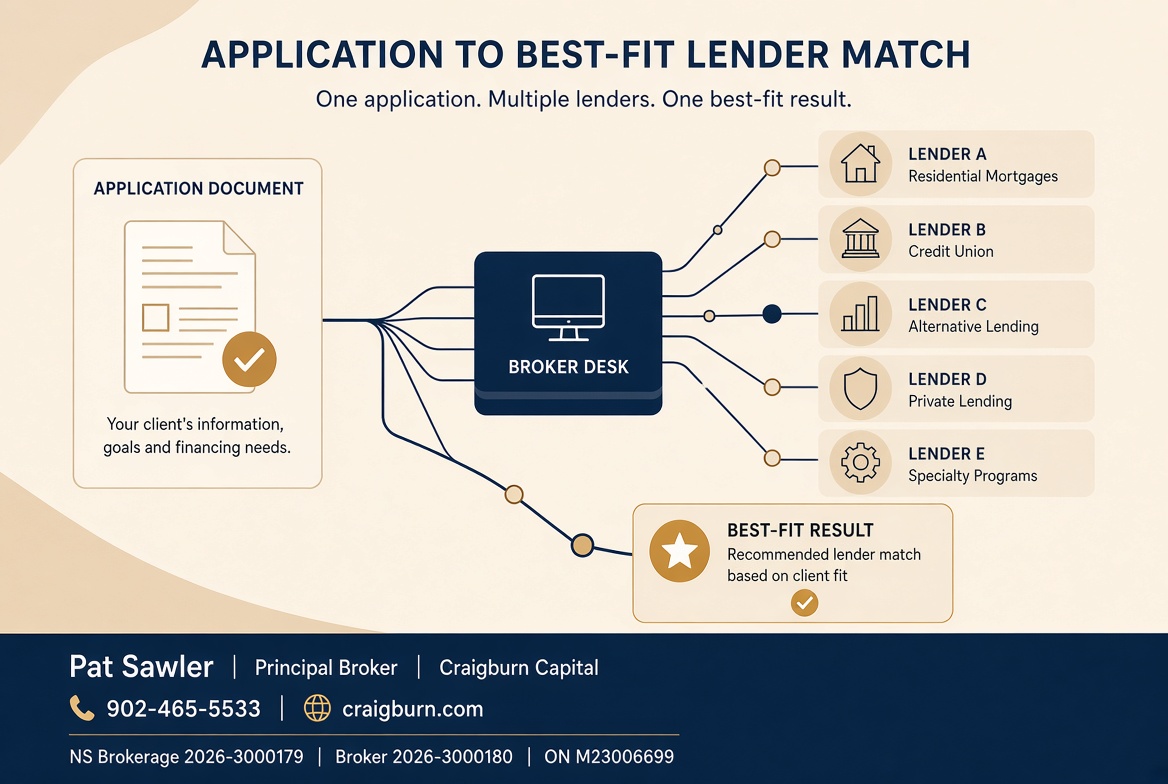
Here is where Craigburn does the work. We take one application, one credit pull and one file, and compare it across 45 lenders so the right product fits the real numbers: price, expected taxes and your down payment. You do not have to chase each lender’s rules yourself.
Is Ontario different?
Yes, and it is the opposite problem. In Ontario, MPAC assessments are still based on a January 1, 2016 valuation date. The 2026 assessment continues to use the fully phased-in 2016 value unless the property has changed. An Ontario assessment can therefore sit far from today’s market value, which is another reason not to read it as a price.
What should I do before I buy, sell or refinance?
Check your assessment notice and see whether the cap applies to you.
If you are buying, ask what the taxes will be after a sale resets the cap, not just what the seller pays now.
Use an appraisal or recent comparable sales, not the assessment, to judge price.
Send us the property details and we will run the taxes into the qualifying numbers before you make an offer.
It is PVSC’s estimate of market value as of a past date (January 1, 2025 for the 2026 assessment), not a current price or an appraisal.
What is the Capped Assessment Program in Nova Scotia?
It limits how much the taxable assessment of an eligible property can rise each year, using the Nova Scotia CPI rate. For 2026 the rate is 2.6%.
Does the cap carry over when I buy a home?
Not after a non-family sale. The cap is removed for the following year, and then restarts the year after if the new owner is eligible, so your taxes may be higher than the seller’s.
Do mortgage lenders use my property assessment?
Typically they use the purchase price or an appraisal to value the property. The assessment matters mainly through the property tax amount counted in your monthly obligations.
Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone. Service aussi disponible en français.
A private mortgage in Canada costs two things: interest and fees, and you have to add them together to see the real price. The rate on the term sheet is only the interest. The lender fee and broker fee, usually a percentage of the loan and taken at closing, can be as large as a full year of interest.
Most people only compare the rate. That is how a loan that looks like 12% turns out to cost a lot more than 12% in the first year.
How much does a private mortgage cost in Canada?
It depends on the lender, the property and the file, so there is no single number. What stays the same is the structure. You pay interest, which is commonly charged monthly and is often interest-only, plus a one-time lender fee, a one-time broker fee and the usual legal and appraisal costs. To see the real cost, add the interest and the fees for the period you will hold the loan.
As a rough guide, rates on private mortgages typically run from about 9% to 14%, and the lender fee can range from 2% to 10% of the loan, with a broker fee on top. Where a file lands in those ranges depends on the property, the equity and the borrower’s situation.
Lender fee. Often called an arrangement or commitment fee, usually a percentage of the loan.
Broker fee. Also usually a percentage of the loan, and paid at closing.
Legal fees. The borrower normally pays for the lawyer who registers the mortgage.
Appraisal and other costs. A private lender will want a current valuation, and may charge small administration fees.
A renewal fee. Some lenders charge another fee if the term is extended. Ask about it before you sign, not at the end of the term.
On some progressive-draw files, such as a build or renovation, the fees are calculated on the full loan amount and paid from the first advance, while interest is charged only on the money that has actually been advanced. That can make the fees feel large at the start, because they arrive all at once while the interest builds up slowly.
What does that look like in real dollars?
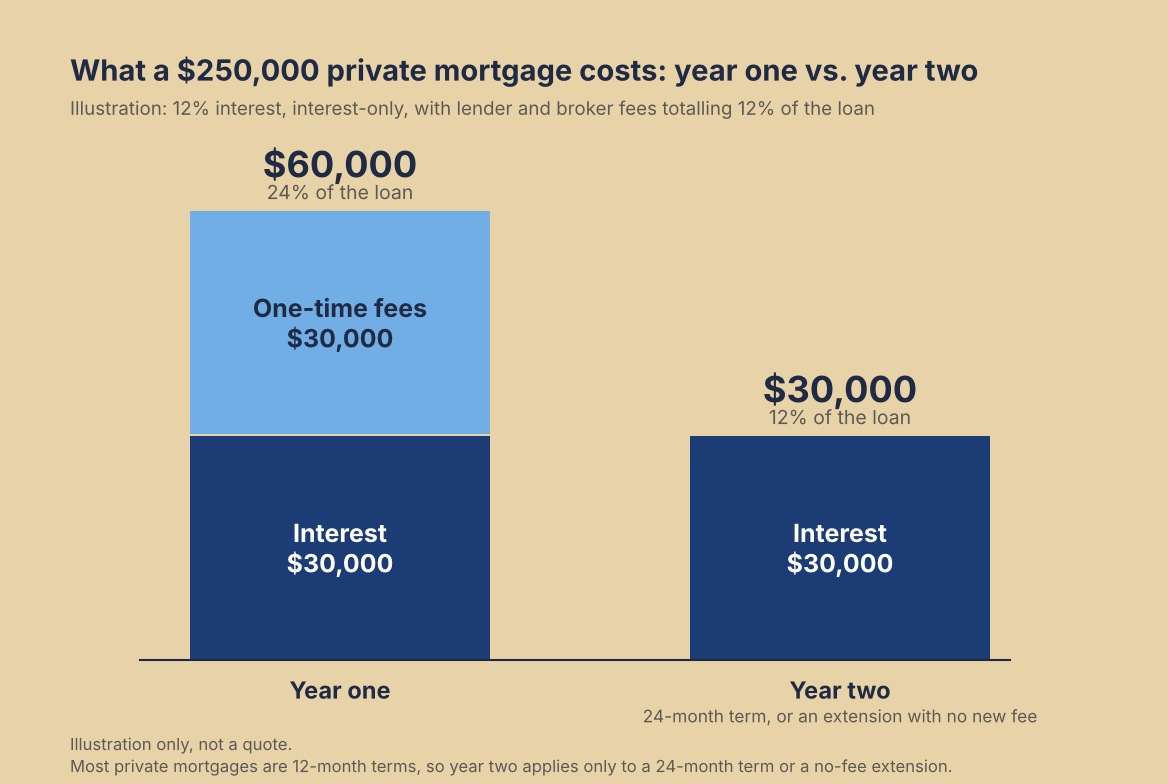
Here is an illustration, not a quote. These numbers are an example only, and your actual rate, fees and terms will depend on the lender, the property and your file. Say you borrow $250,000 on a one-year interest-only private mortgage at 12%, and the lender and broker fees together come to 12% of the loan.
Fees: $30,000, taken from the proceeds at closing, so you receive about $220,000 before legal and other costs.
Interest: $30,000 over twelve months, or $2,500 a month.
First-year total: $60,000, which is 24% of the loan, or about 27% of the cash you actually received.
So 12% interest plus 12% in fees works out to about 24% of the loan in the first year. For a full year on those terms, that is roughly right. The real question is whether the loan does enough for you to be worth it.
Want to try your own numbers? The private lending calculator estimates the fees, the monthly interest-only payment and what you would receive at closing. It is an estimate only, not a commitment to lend.
Why does the first year cost so much more than the second?
Because the fees are a one-time charge, and the interest keeps running. Most private mortgages are written for 12-month terms, so the first-year numbers above are the ones that matter for most borrowers. The second year only exists if the term is 24 months, or if the lender extends the loan with no new fee. In that case it would cost about $30,000 in interest, or 12% of the loan.
Treat that second-year number as the best case, not a promise. Many lenders charge a renewal fee when a term is extended, so ask about it before you sign. A private mortgage is priced for a short stay, and the fees are the price of the speed and flexibility.
The other side of that is leaving early. On a closed term, paying out before the end can still leave you owing the interest through the maturity date, so a fast exit does not always save money. Ask about this in writing before you sign.
When does the higher cost make sense?
When the reason you need the money is temporary and the exit is clear. A credit issue you are repairing, income that will be documented by the end of the term, a property that needs work before a regular lender will take it, or a deadline a bank cannot meet. In those cases the extra cost buys you time or access you would not otherwise have.
If a bank or credit union can do the same job, take the bank. I will tell you that plainly, even when it means I do not do the deal.
Who works out the real cost for me?
I do. You send me one application, and I take your file to the private lenders I work with. You can read how my private lending service works on its own page. For each offer I put the full first-year cost on one page: the interest, every fee, what a renewal would cost, and what it would cost to exit early. You compare real totals side by side, not rates on a term sheet.
You are not chasing quotes from lenders and trying to work out which fee applies to what. That part is my job.
Frequently Asked Questions
How much does a private mortgage cost in Canada?
It varies by lender, property and file. Rates typically run from about 9% to 14%, and the lender fee can range from 2% to 10% of the loan, plus a broker fee and legal and appraisal costs. Add the interest and the fees together for the length of time you will hold the loan to see the real cost.
Are private mortgage fees paid up front?
Often they are taken from the loan proceeds at closing, which means you receive less than the loan amount. Ask for a clear breakdown of what you will actually receive before you commit.
Can I negotiate the interest rate or fees on a private mortgage?
Sometimes. Private lenders price based on the property, the equity and the risk, so a stronger file with more equity can sometimes get better terms. Having more than one lender look at the file helps.
Can I pay off a private mortgage early?
Often yes, but the terms differ by lender. On a closed term you may still owe the interest through the end of the term. Ask for the early payout terms in writing before you sign.
The figures in this post are for illustration only and are not a quote or an offer of financing. Rates, fees and terms vary by lender and file, and all private financing is subject to lender approval.
Need private financing and want the real cost before you decide? Send me your application and I will lay it out.
I look forward to hearing from you in regard to your mortgage needs.
902-465-5533. I answer.
Patrick
Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone. Service aussi disponible en français.
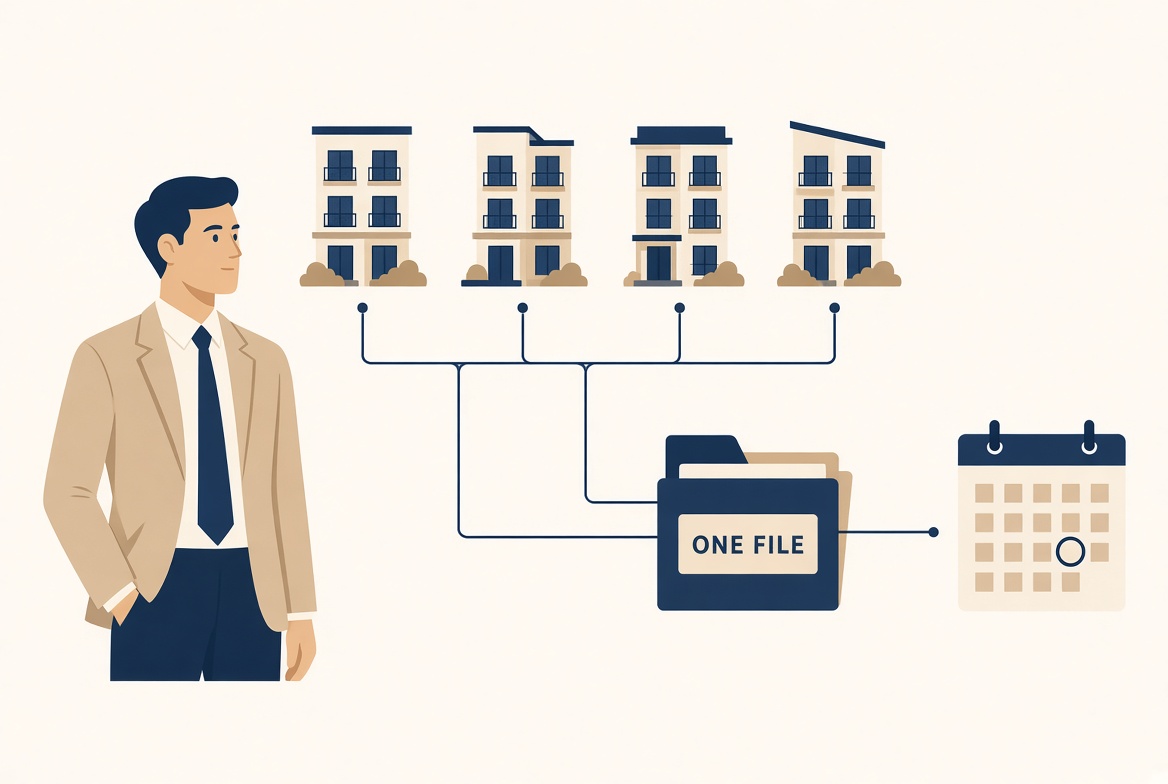
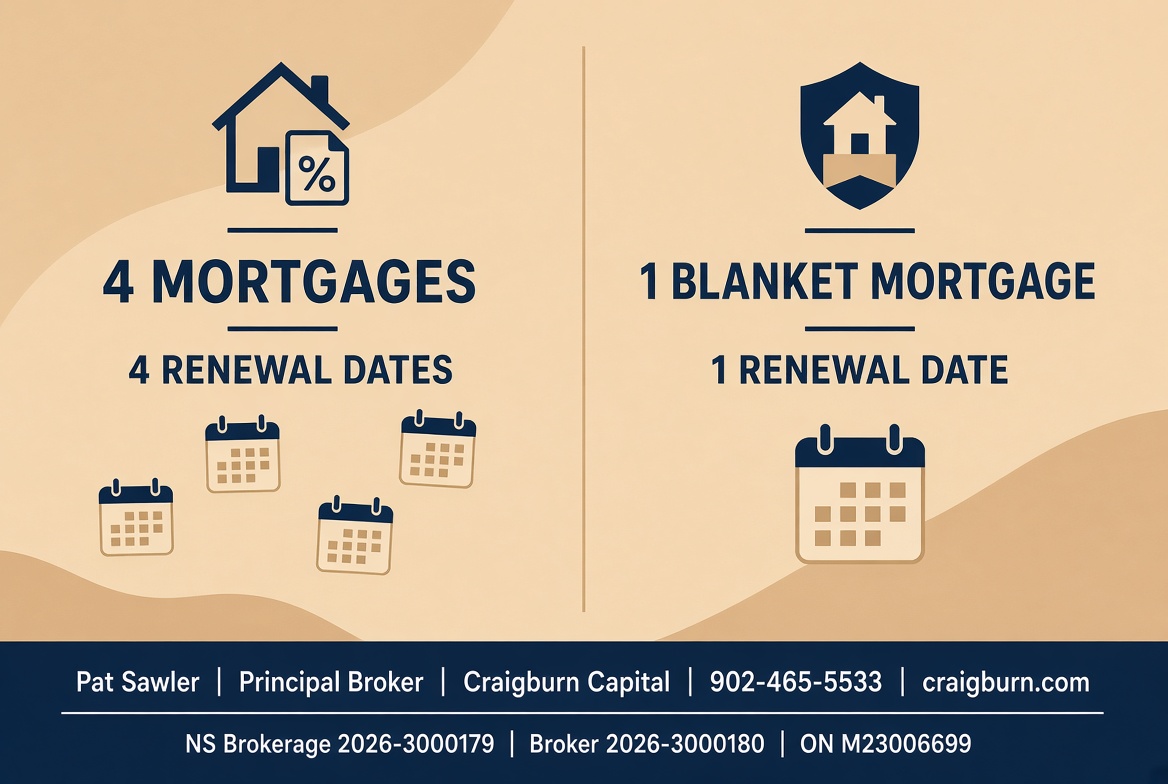
A blanket mortgage rolls several rental properties into a single commercial loan — one rate, one renewal date, one lender relationship — instead of juggling three, five, or ten separate residential mortgages that all renew on different timelines.
I had a landlord call me in a bit of a panic a few months back. He owned four rental properties, each with its own mortgage, each with a different bank, each renewing on a different month of the year. Every renewal was its own fire drill — new paperwork, new rate negotiation, new stress, four times a year instead of once. He’d never heard there was a different way to do it.
How does a blanket mortgage actually work?
Instead of underwriting each property as its own deal, a lender looks at the portfolio as a whole — the combined rental income, the combined expenses, the combined equity — and finances it as one commercial file. You qualify as a package, not as four separate fights for four separate approvals.
Why would a landlord want one mortgage instead of several?
A few reasons come up most often:
One renewal date a year instead of four scattered through it
Often better overall terms when a lender sees the full portfolio and its blended risk, rather than underwriting each property in isolation
Less paperwork and less time re-proving income every time one property comes up for renewal
Easier to pull equity across the portfolio to fund the next purchase, instead of refinancing one property at a time
Is a blanket mortgage the same as a regular commercial mortgage?
Not exactly. A blanket mortgage is a structure — multiple properties under one loan — that can sit inside either a residential or commercial lending framework depending on the number of doors, the property types, and the lender. Every lender treats that threshold a little differently, which is exactly the kind of detail worth walking through before assuming you know which category you fall into.
What do lenders look at to qualify a blanket mortgage?
Mostly the properties themselves — the combined rental income against the combined expenses and debt, often called the debt service coverage ratio. Your personal financial picture still matters, but the properties largely qualify themselves rather than leaning entirely on your personal income the way a single residential mortgage would. CMHC has useful background on how rental and multi-unit financing is evaluated, if you want the longer technical version: cmhc-schl.gc.ca.
Frequently asked questions
What is a blanket mortgage?
A single mortgage that covers two or more properties under one loan, rather than a separate mortgage for each one.
How many rental properties do I need before a blanket mortgage makes sense?
There’s no fixed number. It depends on your properties, your lender options, and whether consolidating actually improves your rate or terms — two very different properties might not benefit the way four similar ones would.
Does a blanket mortgage cost more than separate mortgages?
Not necessarily. Closing and legal costs can come in lower since there’s one closing instead of several, though pricing varies by lender and situation.
Who this is actually for
If you own more than one rental property and you’re tired of renewing on four different clocks, that’s exactly the kind of file I like working on. I pull it together with my commercial lending partner, structure it as one request instead of several separate ones, and walk you through whether a blanket structure actually saves you money — or whether keeping your properties separate is the smarter move for your situation. Every portfolio is different, and that’s the first thing worth figuring out.
If you’re sitting on a handful of renewal dates scattered through the year and wondering if there’s a cleaner way, that’s exactly the conversation worth having. Start here: https://craigburn-capital.mtg-app.com. For the full rundown of how we handle single-file comparisons across lenders, see our earlier piece: Five Lenders, One Hit.
I look forward to hearing from you in regard to your mortgage needs.
Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone.
Own more than one rental property and tired of juggling renewal dates? Reach out — 902-465-5533, or start here: https://craigburn-capital.mtg-app.com
I had a client last month who’d been sitting on a pre-approval for three weeks, too nervous to get a second opinion. “I don’t want to wreck my credit shopping around,” she told me. She’d read it somewhere — every lender you talk to is another ding on your score, so pick one and hope for the best.
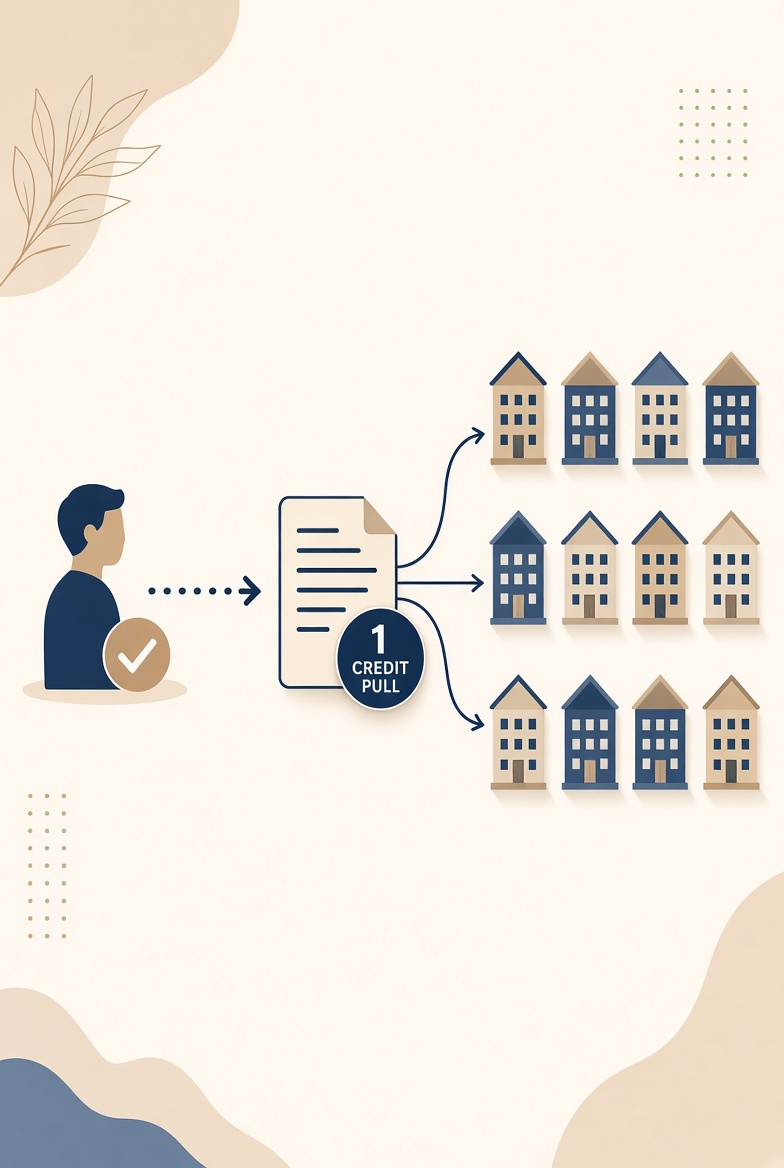
Here’s what I told her: you don’t have to shop around yourself at all. That’s my job. One application, one credit pull, and I take it to 45 lenders and hundreds of products on your behalf. You get the full market compared without lifting a finger past the first form — and without the five-separate-hits worry in the first place, because there’s only ever one pull.
That said, the myth itself is worth clearing up too — because plenty of people do still shop a few lenders themselves before ever calling a broker, and the fear that’s stopping them isn’t based on how credit scoring actually works.
Why this actually works, not just feels better
Credit scoring models are designed to tell the difference between two very different patterns: someone opening five different types of credit in a month (a red flag — car loan, two credit cards, a line of credit, all at once), and someone getting multiple quotes for the exact same thing — a mortgage — inside a short window. The first one looks like financial stress. The second one looks like someone doing their homework, and the bureaus bundle those inquiries into a single event rather than stacking hits for each one.
Which is exactly why going through a broker is the cleaner version of the same idea. When I submit your file, I’m not generating five separate applications with five separate pulls — it’s one pull, shopped across my full lender list. You get the comparison shopping benefit without even needing the bundling rule to save you, because the multiplication never happens in the first place.
Where people get this wrong
They assume comparing the market means doing it themselves. Calling five banks, filling out five applications, and keeping track of five sets of terms is real work — and it’s not actually necessary. One application to me covers the same ground.
They mix inquiry types. If you are shopping on your own, a mortgage pre-approval, a car loan, and a new credit card all inside the same month isn’t the same thing as comparing five mortgage lenders — that genuinely does read differently to a scoring model, because now it looks like you’re taking on credit from multiple directions, not comparing one kind of offer.
They stretch it out too long. The bundling only works inside a tight window. Get one quote in July and another in October, and you’ve lost the benefit — those get treated as two separate events, months apart, instead of one shopping pass.
Who this is actually for
Anyone who’s been quietly carrying one lender’s quote around for weeks, afraid to get a second opinion, or anyone who assumed “shopping around” meant hours on the phone with five different banks. It doesn’t have to. I do it with one application, one credit pull, and access to 45 lenders and hundreds of products — so you get the comparison without doing the legwork, and without wondering whether checking was worth the risk, because there isn’t one.
If you’re sitting on a quote right now and wondering whether it’s actually the best one out there, that’s exactly the conversation worth having. Start here: https://craigburn-capital.mtg-app.com
I look forward to hearing from you in regard to your mortgage needs.
Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone.
Are mortgage rates going up in Canada? Yes, the pressure is upward right now. The Bank of Canada raised its policy rate to 2.50% on October 28, 2026, its first hike in more than three years, and lenders’ fixed rates have been shaped by higher bond yields as well.
If you are renewing or buying in the next few months, you do not need to predict the market to protect yourself from it. Here is what is happening, why, and what to do about it. The figures below are current as of mid-November 2026, and I update this post as things change.
What did the Bank of Canada just do?
On October 28, the Bank raised its benchmark rate by a quarter of a percentage point, to 2.50%. According to the Bank of Canada’s announcement, the move follows a long hold after a series of cuts. I wrote about the decision and what it means for borrowers in this post on the rate hike.
Why are rates going up?
The short version is energy prices and inflation. Higher global oil prices from the war in the Middle East have kept cost pressures building, and inflation rose to 3.1% in September, driven largely by gas prices. The Bank expects inflation to reach about 3.5% by the end of 2026 before easing back toward 2% by mid-2028. Its goal with the hike is to keep energy costs from spreading into the price of everything else.
Bond yields matter too. Canada’s five-year government bond yield is the number that drives most fixed mortgage rates, and the Bank of Canada’s latest survey of market participants raised its median forecast for that yield by 35 basis points, to about 3.50%. More than half of those surveyed see risks to rates skewed higher, and none see them skewed lower.
Will the Bank of Canada raise rates again?
Nobody knows, and forecasters disagree. The Bank’s next decision is on December 9. Some economists expect another hike in December or January, while others expect a pause in December and a peak around 2.75% later. It is also a geopolitical story as much as an economic one, so a change in energy markets could ease the pressure as quickly as it built.
How does this affect your mortgage?
It depends on which mortgage you have:
Variable rate: your rate follows the lender’s prime rate, which moves with the Bank of Canada. After a hike, your payment or the interest portion of it can go up.
Fixed rate, mid-term: nothing changes until your term ends. Your rate is locked for the term you chose.
Fixed rate, renewing soon: this is where it bites. Your renewal rate is set by bond yields at the time, so the offer in your renewal letter can be higher than what you have now.
Buying soon: the rate you qualify at and the rate you are offered both move with this environment.
What should you do if you are renewing or buying soon?
A pre-approval is the simplest way to protect yourself. Many lenders hold a pre-approved rate for around 90 to 120 days, and you are not obligated to use it. If rates fall before you close, you can usually take the lower rate, so it is an option that costs you very little and could save you real money if this trend continues.
If your renewal is coming up, start early. Your lender’s letter is one offer, not the market. I compare it against what 45 lenders would do on the same file, and if you have extra savings, I can show you how a paydown at maturity changes the numbers. I explain that in can you pay down your mortgage at renewal without a penalty. You can also run your own numbers with the mortgage payment calculator, and see what I offer on my residential mortgages page.
Frequently Asked Questions
Are mortgage rates going up in Canada?
Pressure is upward right now. The Bank of Canada raised its policy rate by 0.25% to 2.50% on October 28, 2026, its first increase in more than three years. Variable rates follow that move directly, and fixed rates follow bond yields, which markets expect to stay elevated. Where rates go next is not certain.
Will the Bank of Canada raise rates again?
Economists disagree. The next decision is December 9. Some forecasters expect another hike in December or January, while others expect a pause in December and a peak of 2.75% later. Nobody can say for sure, which is why a plan matters more than a prediction.
Should I get a mortgage pre-approval now?
If you are renewing or buying in the next few months, it is worth considering. Many lenders hold a pre-approved rate for around 90 to 120 days, and you are not obligated to use it. If rates fall before you close, you can usually take the lower rate instead, so the option costs you little.
How does a rate hike affect my variable-rate and fixed-rate mortgage?
A variable-rate mortgage moves with the lender’s prime rate, which follows the Bank of Canada’s policy rate, so your payment or the interest portion of it can rise after a hike. A fixed rate stays the same for your current term, but the rate you are offered at renewal is set by bond yields at that time.
This post is general information, not financial advice. Rates, lender policies and forecasts change often, and all financing is subject to lender approval.
Renewing or buying in the next few months? Send me your application and I will compare your options and set up a pre-approval.
I look forward to hearing from you in regard to your mortgage needs.
902-465-5533. I answer.
Patrick
Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone. Service aussi disponible en français.
Should you switch mortgage lenders at renewal, or just take the rate your bank offers you? Twice this week, I told a client to stay exactly where they are.
Both were renewals. Both were with the same lender I’d placed them with myself, years ago. And both times, when I went shopping for a better deal, I ran into the same wall: the rate their own bank was offering them directly, just for renewing, beat anything I could get them through the broker channel. No fees either way. Just a better number, sitting right there in their inbox.
So I told them to take it.
Here’s the part that might surprise you: that’s not me being generous. That’s the whole point of having a broker in the first place.
Why this happens
Lenders price differently depending on the door you walk through. Sometimes the “retention” rate — the one they send you directly to keep you from shopping around — is genuinely sharper than what they’ll offer through a broker, because they’re not paying broker compensation on that deal. It doesn’t happen every time. But it happens often enough that anyone telling you “always switch, always negotiate, never just renew” hasn’t actually run the numbers on your file.
Why I still don’t mind
A rate quote without context is just a number. My job was never “get you the lowest number I can find” — it’s “get you the right outcome for your actual situation,” even when the right outcome is a phone call that ends with “stay put.” I’d rather earn the trust that gets referred to a friend than the commission that comes from steering someone somewhere they didn’t need to go.
What I’d tell you to actually check before you renew
Get the direct offer from your current lender in writing, not just verbally
Confirm it’s locked for the full term you want, not a teaser that reprices later
Ask what happens if you don’t take action by the renewal date — some lenders auto-renew you into a worse rate if you do nothing
Still worth a second opinion, even if you end up staying — the two minutes it takes to check costs you nothing, and sometimes the direct offer isn’t actually the best one
To be clear — both of these were straightforward renewals. No new funds, no debt consolidation, nothing that needed a full switch or new appraisal in the first place. If you’re pulling equity out, restructuring debt, or your current lender isn’t offering anything competitive, that’s a different conversation — and usually a very good reason to shop around.
If your renewal’s coming up, send it my way. Worst case, I tell you to do nothing and shake your hand on the way out.
I look forward to hearing from you in regard to your mortgage needs.
902-465-5533. I answer.
Patrick
p.s. Ready to see what you qualify for? Apply now
p.s. Prefer to talk it through first? Book a call
p.s. Licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI.
p.s. Grab the Craigburn mortgage app: Download here
Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone.
Questions about your renewal? Call 902-465-5533 or apply now.
Someone told me last week they’d found a renewal rate that seemed too good to pass up. A few days later, it was gone — not because they were too slow, but because something in their life quietly changed underneath it.
This happens more than people realize, and it’s worth understanding before you get attached to a number.
The Rate Isn’t Really About the Rate
A renewal offer from your current lender is usually priced for one very specific scenario: nothing changes. Same amount owing, same person (or people) on the mortgage, same amortization, same everything. The bank already knows you, already has your file, and isn’t re-underwriting anything — so they can afford to offer you a sharp number.
The second any one of those things shifts — you want to add a spouse to the mortgage, pull out some equity, extend your amortization, anything — you’re no longer getting a renewal. You’re applying for a brand new mortgage. And a brand new mortgage gets priced off a completely different sheet, with real underwriting behind it.
That’s not a penalty for changing your mind. It’s just a different product wearing the same name.
What Actually Triggers the Switch
The most common ones I see:
Adding someone to the mortgage — even if they’re already on title, adding them to the loan itself means they now have to qualify too
Taking equity out — for renovations, debt consolidation, anything — turns a straight renewal into a full refinance
Changing your amortization — stretching it out or shortening it up both take you out of “nothing changed” territory
Any one of these on its own is enough. If more than one applies, it doesn’t compound the damage — you’re already in full-application territory, so there’s no extra penalty for doing them together.
None of This Means Don’t Do It
I want to be clear about something: none of this means the life change isn’t worth it. Adding a spouse to a mortgage, or pulling equity for something that matters to you, can be exactly the right call. The point isn’t to talk you out of it — it’s to make sure you’re deciding with the real numbers in front of you, not the number that caught your eye before anything changed.
And sometimes there’s a cheaper way to get the outcome you actually want. If what you’re really after is peace of mind rather than a specific loan structure, there can be options — like mortgage protection insurance — that solve for the underlying worry without triggering a full new application at all.
The best move is always to ask before you assume. A five-minute conversation before you lock anything in can tell you exactly which bucket you land in, and what your real options look like from there.
I look forward to hearing from you in regard to your mortgage needs.
902-465-5533. I answer.
Patrick
p.s. Ready to start your application? Click here.
p.s. Prefer to talk first? Book a time with me here.
p.s. FSRA Principal Broker License #M23006699, Craigburn Capital, NS Brokerage 2025-3000179, NS Broker 2025-3000180.
p.s. Download the mortgage app here.
Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone.
Every private file I take on starts with some version of the same question: “Realistically, how fast can this actually close?”
Fair question. “Fast” gets thrown around a lot in this business, and it means different things depending on who’s saying it. So instead of a vague promise, here’s the actual math — real ranges, side by side.
The Bank Timeline
A conventional mortgage through a bank or A-lender, once your full application and documents are in, typically runs:
Underwriting and conditional approval: 5–10 business days
Appraisal (if required): adds 3–7 business days, sometimes more if the appraiser’s backlog is long
Final approval and document prep: another 5–7 business days
Total, start to close: usually 3–5 weeks, assuming nothing gets kicked back for more conditions
And that’s the good scenario — the one where your income is straightforward, the property is standard, and nothing needs a second look. Add a self-employed borrower, a rural property, or a file that needs to go back for clarification even once, and that timeline stretches fast.
The Private Timeline
Private financing isn’t fast because the underwriting is sloppy — it’s fast because the process is built around a different question. A bank asks “does this fit our program?” A private lender asks “does the security make sense?” That’s a shorter conversation.
Initial review and term sheet: often within 24–48 hours of a complete package
Appraisal: still required, but private appraisers tend to have shorter queues — 2–5 business days is common
Legal and funding: 5–10 business days once the lawyer has instructions
Total, start to close: 7–14 business days is realistic for a clean file. I’ve seen it move faster when everyone — borrower, lawyer, appraiser — is genuinely ready to move.
Why the Gap Is So Big
It’s not that private lenders cut corners. It’s that they’re solving a narrower problem. A bank is underwriting you — your income, your job history, your debt ratios, against a rigid program built for thousands of borrowers at once. A private lender is underwriting the property — is there enough equity here that the math works even in a worst-case scenario. Fewer variables, fewer conditions, fewer rounds of back-and-forth.
That’s also why private financing usually costs more. You’re not paying for less scrutiny — you’re paying for a process that isn’t waiting in line behind a thousand other files.
When the Speed Actually Matters
This isn’t really an either-or decision most of the time. It matters when:
You’re competing on an offer and a fast, certain close is a negotiating advantage
A renewal or default situation has a real deadline attached to it
If none of those apply, the bank route is usually still the better economics. Private financing earns its cost when time itself has a dollar value attached to it — and in those situations, the gap between 3–5 weeks and 7–14 days isn’t just a convenience, it’s the difference between the deal happening or not.
If you’re staring down a timeline that a bank can’t hit, let’s talk about what’s actually realistic for your situation — not a guess, a real number based on your file.
I look forward to hearing from you in regard to your mortgage needs.
902-465-5533. I answer.
Patrick
p.s. You can start an application anytime through our secure portal: https://craigburn-capital.mtg-app.com
p.s. Prefer to talk first? Book a time here: [scheduling link]
p.s. Licensed in Nova Scotia and Ontario — NS Brokerage 2025-3000179, NS Broker 2025-3000180, ON M23006699
p.s. Download the mortgage app: [app download link]
Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone.
Questions about your timeline? Call 902-465-5533 or start your application at craigburn-capital.mtg-app.com
A cap rate is a property’s annual net operating income divided by its purchase price or market value, shown as a percentage. It shows the return a property earns from its income alone, before any mortgage, so you can compare buildings on equal terms.
Cap rate is one of the most common tools investors use to judge an apartment building’s profitability, and not every property is created equal. Here is what a cap rate is, how to calculate it with a worked example, what a good cap rate looks like in Canada, and how to use it to evaluate a building.
What is a cap rate?
The capitalization rate, or cap rate, is a fundamental metric in real estate investing that measures the potential return on an investment property. It is expressed as a percentage and represents the relationship between a property’s net operating income (NOI) and its market value or purchase price. Essentially, the cap rate helps investors assess the profitability and risk of a property without factoring in financing methods like mortgages.
Cap rate is particularly useful for comparing multiple investment opportunities. A higher cap rate typically indicates a higher potential return but may also come with higher risk. Conversely, a lower cap rate suggests a lower return but often corresponds to a more stable and less risky investment.
How do you calculate cap rate?
The formula for calculating cap rate is straightforward:
Cap Rate = (Net Operating Income / Property Value) × 100
Let’s break down the components of this formula:
Net Operating Income (NOI): NOI is the annual income generated by the property after subtracting all operating expenses but before accounting for mortgage payments, income tax and depreciation. Operating expenses include property management fees, maintenance costs, insurance, utilities, and property taxes. NOI = Total Rental Income – Operating Expenses
Property Value: This is the current market value or purchase price of the property. If you’re evaluating a property listed for sale, the purchase price is typically used. If you’re analyzing an existing investment, the current market value can be used instead.
Example: a $4,000,000 apartment building
Let’s say you’re considering purchasing an apartment building with the following details:
Total Rental Income: $500,000 per year
Operating Expenses: $200,000 per year
Purchase Price: $4,000,000
First, calculate the NOI: NOI = $500,000 – $200,000 = $300,000
Next, plug the numbers into the cap rate formula: Cap Rate = ($300,000 / $4,000,000) × 100 = 7.5%
In this example, the cap rate is 7.5%, which means the property is expected to generate a 7.5% return on investment based on its current income and price.
What is a good cap rate for commercial real estate in Canada?
Property Type
Typical Cap Rate Range
Notes
Multi-Family (major metros)
4.5% – 4.8%
Most compressed asset class — strong rental demand keeps rates tight
Industrial
5.7% – 6.3%
Cooled from the 2020–2022 e-commerce boom, still tight in major logistics corridors
Retail
5.9% – 6.6%
Stabilizing after years of “death of retail” headlines
Office
6.8% – 8.9%
Downtown Class AA–B — compressing gradually as leasing fundamentals improve
A quick honest note here: these figures reflect national and major-metro benchmarks — Toronto, Vancouver, and similar markets. Halifax and Atlantic Canada see far fewer commercial transactions, so local cap rates often sit outside these ranges entirely, usually wider. If you’re evaluating a property here, a national average is a starting reference point, not a verdict — talk to a local broker or appraiser (or me) for something grounded in real comparables.
How do you use cap rate to evaluate an apartment building?
Now that you know how to calculate cap rate, let’s discuss how to use it to determine if an apartment building is a wise investment.
1. Compare Cap Rates Across Properties
This is easiest to see side by side:
Property A
Property B
Rental Income
$500,000
$650,000
Operating Expenses
$200,000
$310,000
NOI
$300,000
$340,000
Purchase Price
$4,000,000
$4,000,000
Cap Rate
7.5%
8.5%
Property B looks like the better deal on paper — but a higher cap rate isn’t automatically the win. If Property B’s higher NOI comes from a riskier tenant mix, shorter leases, or deferred maintenance that’s about to catch up with you, that extra percentage point is compensation for real risk, not free money.
2. Assess Market Trends
Cap rates vary by location and market conditions. In high-demand areas with lower risk, such as prime urban locations, cap rates tend to be lower because investors are willing to accept lower returns for the stability and appreciation potential. In contrast, properties in less desirable areas may have higher cap rates to compensate for the increased risk. Understanding the average cap rate for your target market will help you determine whether a specific property is priced competitively.
3. Evaluate Risk and Return
A higher cap rate may seem attractive, but it often comes with higher risk. For example, a property with a 10% cap rate might be located in an area with declining demand or require significant repairs. On the other hand, a property with a 5% cap rate might be in a stable, high-growth area with lower risk. As an investor, you need to balance your desired return with your risk tolerance.
4. Determine if the Property Meets Your Investment Goals
Your ideal cap rate will depend on your investment strategy. If you’re looking for steady cash flow and long-term appreciation, a lower cap rate in a stable market might be suitable. If you’re focused on maximizing short-term returns and are willing to take on more risk, a higher cap rate property might be a better fit.
5. Use Cap Rate to Estimate Property Value
Cap rate can also be used to estimate the value of a property based on its income potential. If you know the NOI of a property and the average cap rate for similar properties in the area, you can calculate the property’s estimated value using the following formula: Property Value = NOI / Cap Rate
For example, if a property has an NOI of $200,000 and the average cap rate for similar properties is 6%, the estimated value would be: Property Value = $200,000 / 0.06 = $3,333,333
This calculation can help you determine if a property is overpriced or a good deal.
What are the limitations of cap rate?
While cap rate is a valuable tool, it’s important to recognize its limitations:
It Doesn’t Account for Financing: Cap rate calculations don’t include mortgage payments or other financing costs, so they don’t reflect your actual cash flow. To see how much you can borrow against a property, read how commercial LTV works.
It’s a Snapshot in Time: Cap rate is based on current income and expenses, which may change over time due to market conditions, rent increases, or unexpected expenses.
It Doesn’t Consider Appreciation: Cap rate focuses on income, not the potential for property value appreciation, which can be a significant source of return in high-growth markets.
Is an apartment building a wise investment?
Cap rate is a powerful tool for evaluating the potential return and risk of an apartment building investment. By calculating the cap rate and comparing it to similar properties in the market, you can gain valuable insights into whether a property is a wise investment. However, cap rate should not be the only factor you consider. Be sure to also evaluate the property’s location, condition, growth potential, and alignment with your investment goals.
If you’re new to real estate investing or unsure how to apply cap rate to your specific situation, working with an experienced real estate professional can make all the difference. As a seasoned broker with a deep understanding of market trends and investment strategies, I can help you analyze properties, calculate cap rates, and make informed decisions that align with your financial goals. Whether you’re looking for a high-cash-flow property or a long-term appreciation play, I’m here to guide you every step of the way. You can see how I approach larger files on my commercial financing page.
A cap rate is a property’s annual net operating income divided by its purchase price or market value, expressed as a percentage. It measures the return a property earns from its income alone, before any mortgage payments.
What is a good cap rate for commercial real estate?
It depends on the property type and market. Multi-family properties in major metros often see 4.5%–4.8%, industrial 5.7%–6.3%, retail 5.9%–6.6%, and downtown office 6.8%–8.9%. The 2026 national average across all property types sits around 6.58%, per CBRE’s Q2 2026 report — though Atlantic Canada properties often trade outside these ranges given fewer local transactions.
How do you calculate cap rate?
Divide a property’s net operating income (NOI) by its purchase price or current market value, then multiply by 100. For example, a property with $300,000 NOI and a $4,000,000 purchase price has a 7.5% cap rate.
What’s the difference between cap rate and ROI?
Cap rate measures a property’s return based purely on its income relative to its value, without factoring in financing. ROI (return on investment) typically accounts for how the property was financed, including mortgage payments, making it a more complete picture of your actual return once leverage is considered.
Do cap rates in Halifax differ from major markets like Toronto?
Often, yes. National cap rate benchmarks reflect major-metro transaction volume in markets like Toronto and Vancouver. Halifax and Atlantic Canada see far fewer commercial transactions, so local cap rates frequently sit outside these national ranges, usually wider.
Can you use cap rate to estimate a property’s value?
Yes — by rearranging the formula: Property Value = NOI ÷ Cap Rate. For example, a property generating $200,000 in NOI at a 6% area cap rate would be valued at roughly $3,333,333.
This post is general information, not legal or financial advice. Cap rates, lending requirements and market conditions vary by property, lender and location, and all financing is subject to lender approval.
Looking at a multi-unit or commercial purchase and want the numbers checked? Send me your application and I will walk you through the cap rate and the financing together.
I look forward to hearing from you in regard to your mortgage needs. 902-465-5533. I answer. Patrick
Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone. Service aussi disponible en français.
What Waiting 10 Years to Buy Actually Costs You — The Real Numbers From Toronto to Halifax
July 22, 2026
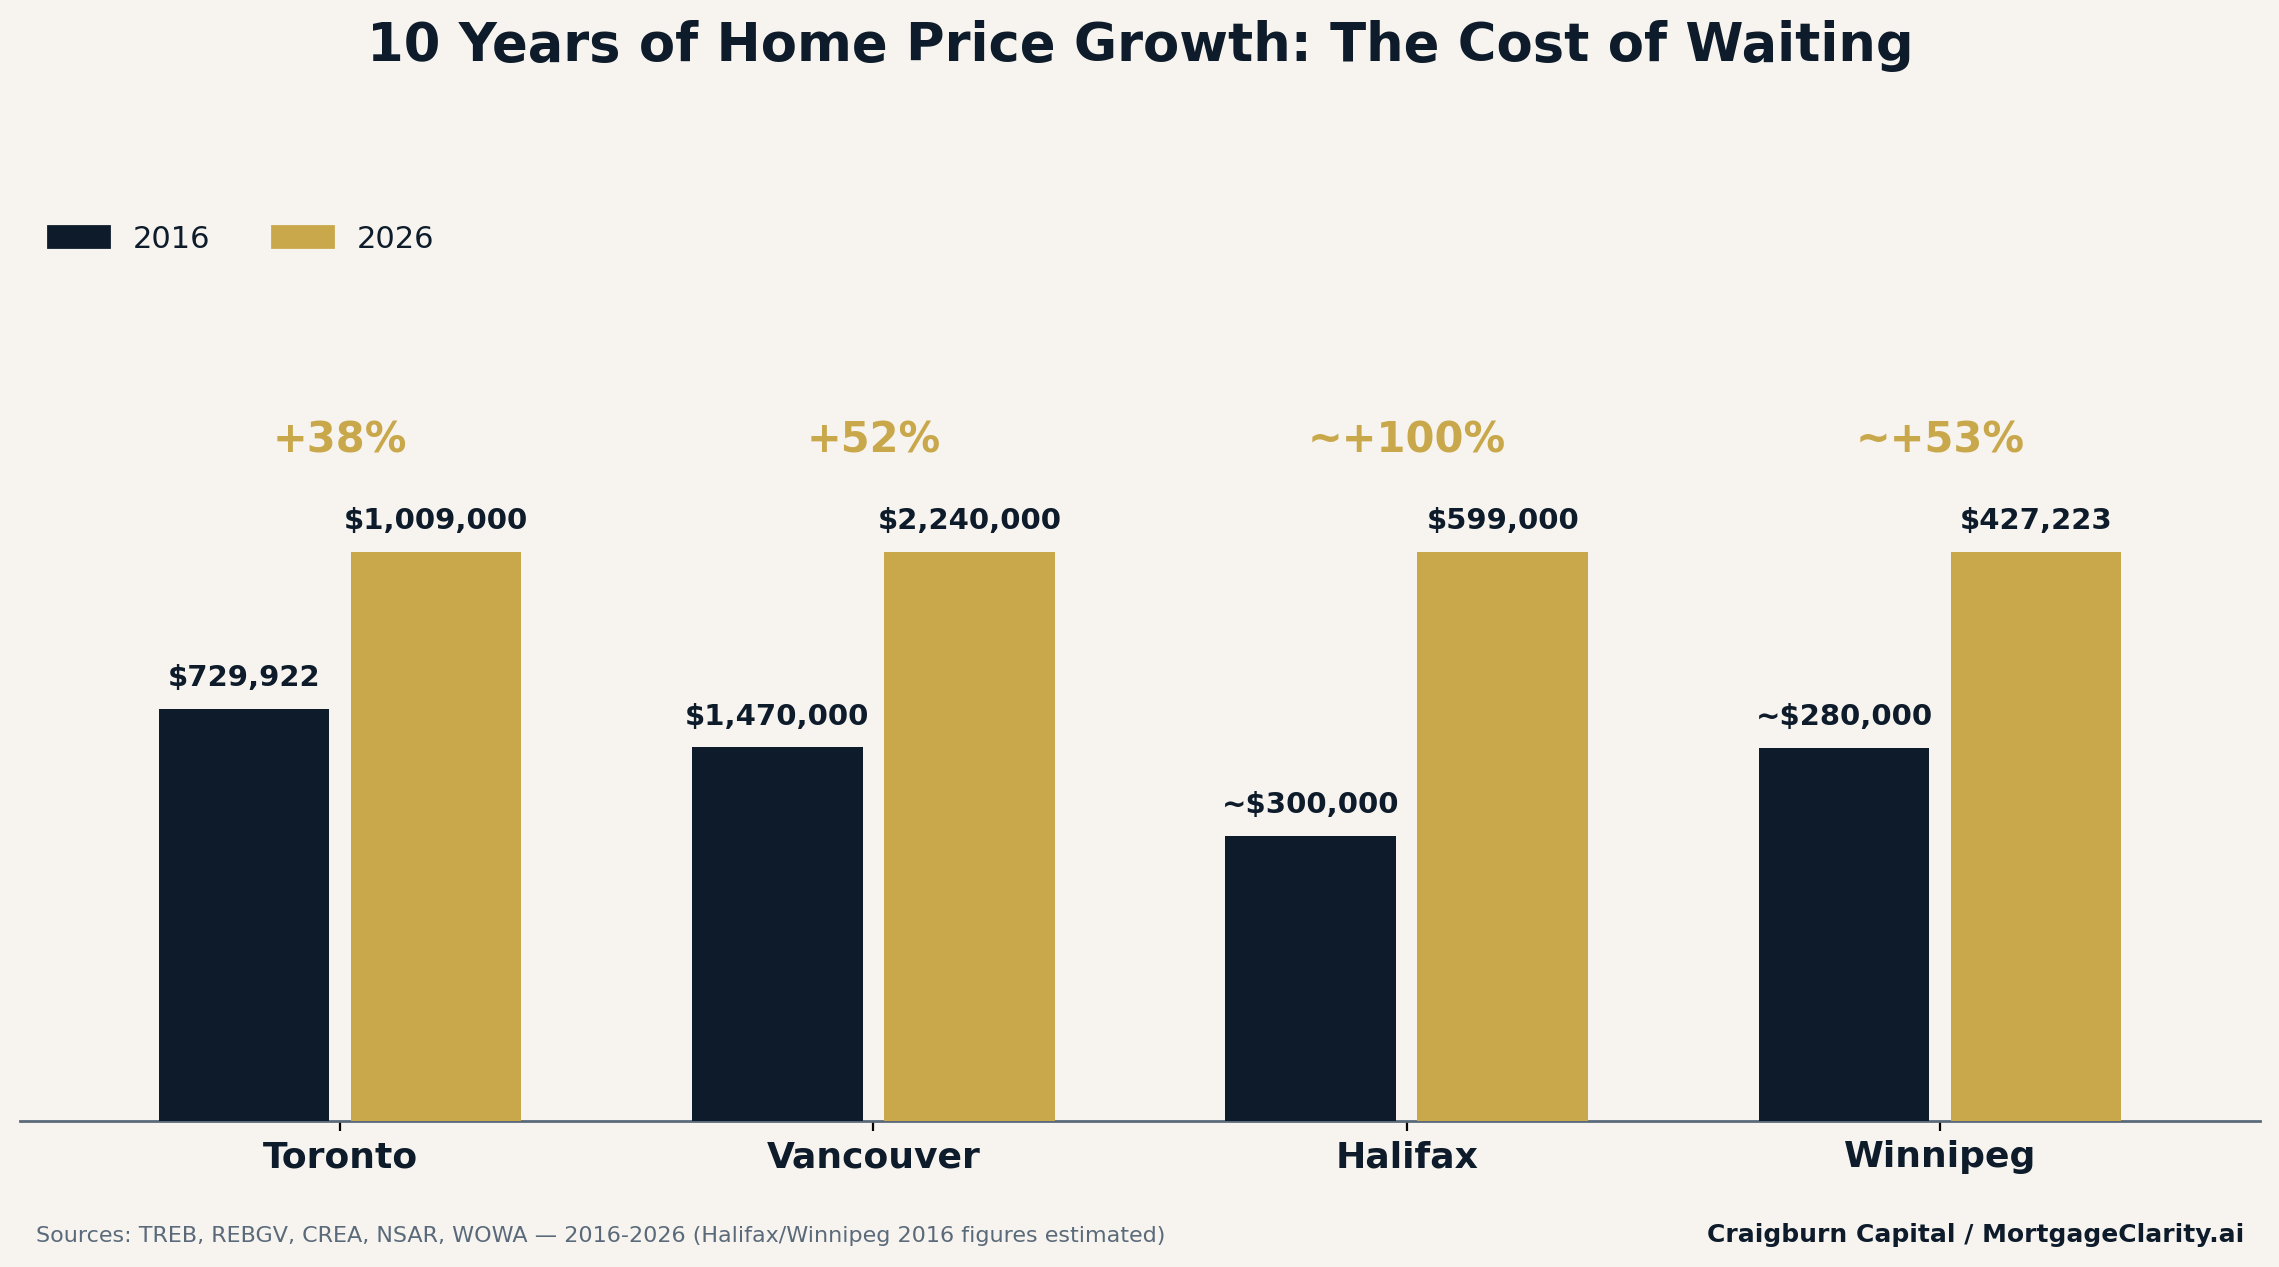
Quick answer: “I’ll buy once I’ve saved more” sounds responsible — but over the past decade, home prices in every major Canadian market grew faster than most people can realistically save. Halifax prices have roughly doubled since 2016. The person who bought a decade ago with a smaller down payment is often further ahead today than the person who spent that decade saving for a bigger one.
Quick note on where I’m coming from: I’m a mortgage broker, not a rental investment advisor. This isn’t about renting vs. owning — it’s about what actually happens when you wait to buy.
Here’s what home prices actually did over the last 10 years:
City
2016
2026
10-Yr Growth
Toronto
$729,922
$1,009,000
+38%
Vancouver (detached)
$1,470,000
$2,240,000
+52%
Halifax (est.)
~$300,000
$599,000
~+100%
Winnipeg (est.)
~$280,000
$427,223
~+53%
Sources: TREB/TRREB, REBGV, CREA/NSAR, WOWA, CREA/WRREB. Halifax/Winnipeg 2016 figures are estimated. Past appreciation doesn’t guarantee future performance.
Halifax roughly doubling in 10 years should get your attention if you’re local — that’s not a Toronto/Vancouver story, that’s ours.
The math that matters: Someone who bought in Halifax in 2016 with $40,000 down (about 13%) is sitting on a home now worth roughly double. Someone who spent that decade saving instead — even an extra $25,000 on top of their original $40,000 — now has $65,000 against a home that costs roughly double what it used to. That’s a smaller effective down payment than they started with, despite years of real saving.
This isn’t a “buy no matter what” post — there are good reasons to wait if you’re genuinely not ready. But “I’m waiting to save more” and “I’m chasing a number the market keeps moving on me” are two different things, and it’s worth knowing which one you’re actually doing.