Blanket mortgage for rental properties
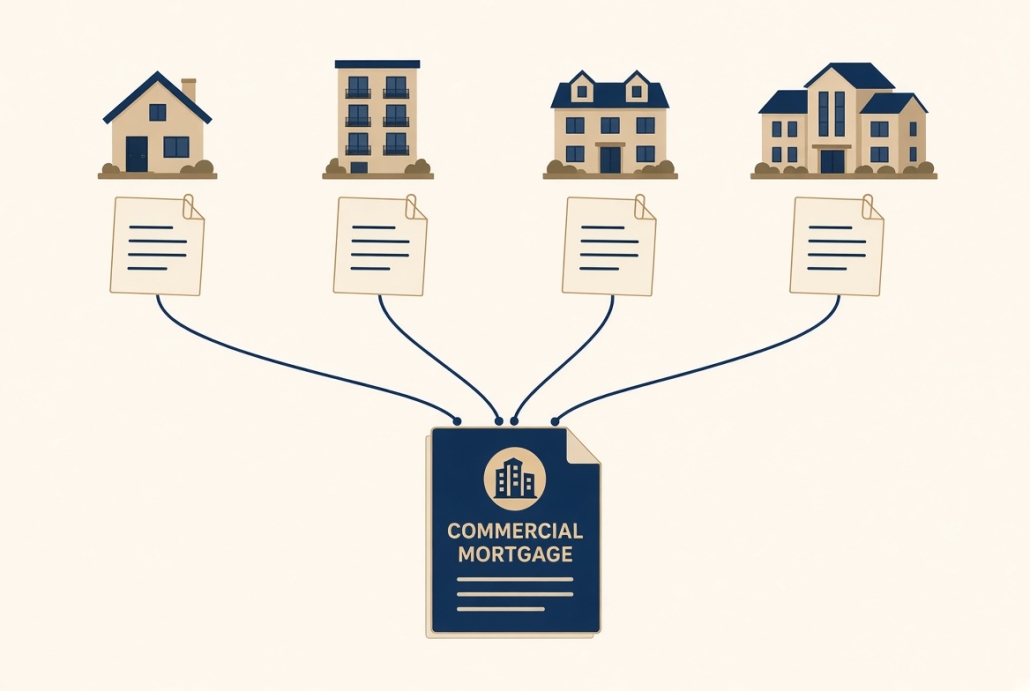
A blanket mortgage rolls several rental properties into a single commercial loan — one rate, one renewal date, one lender relationship — instead of juggling three, five, or ten separate residential mortgages that all renew on different timelines.
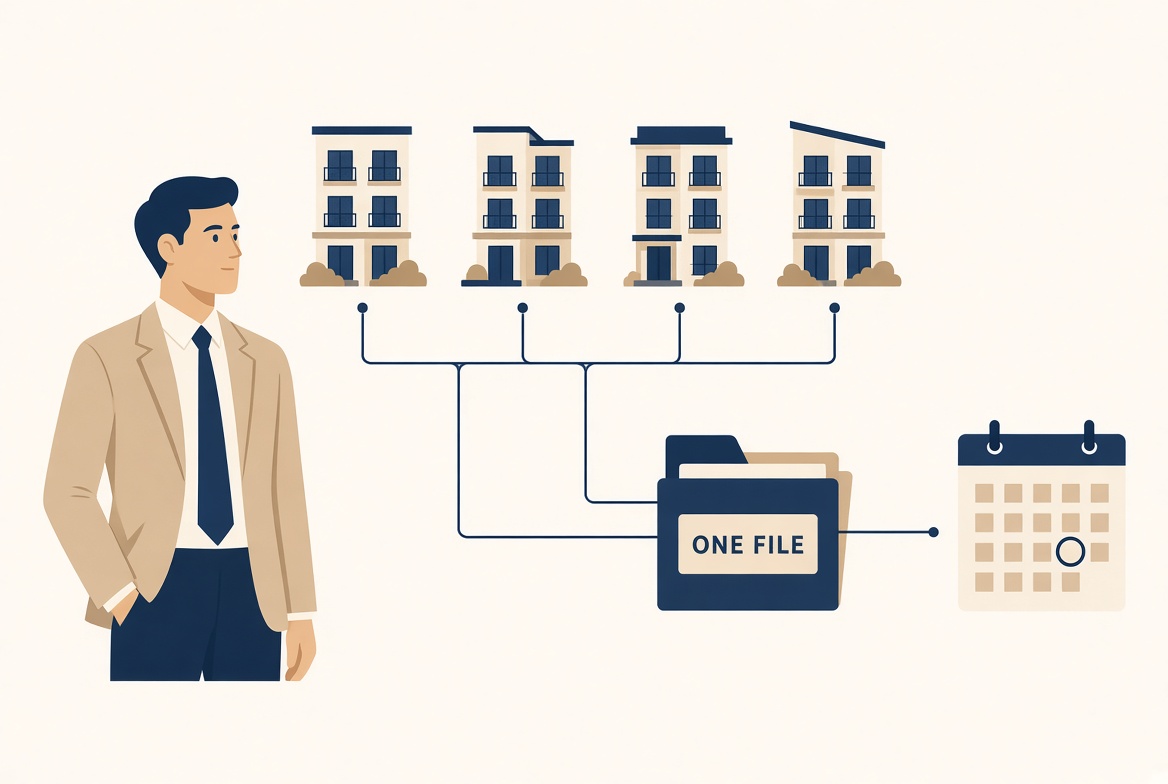
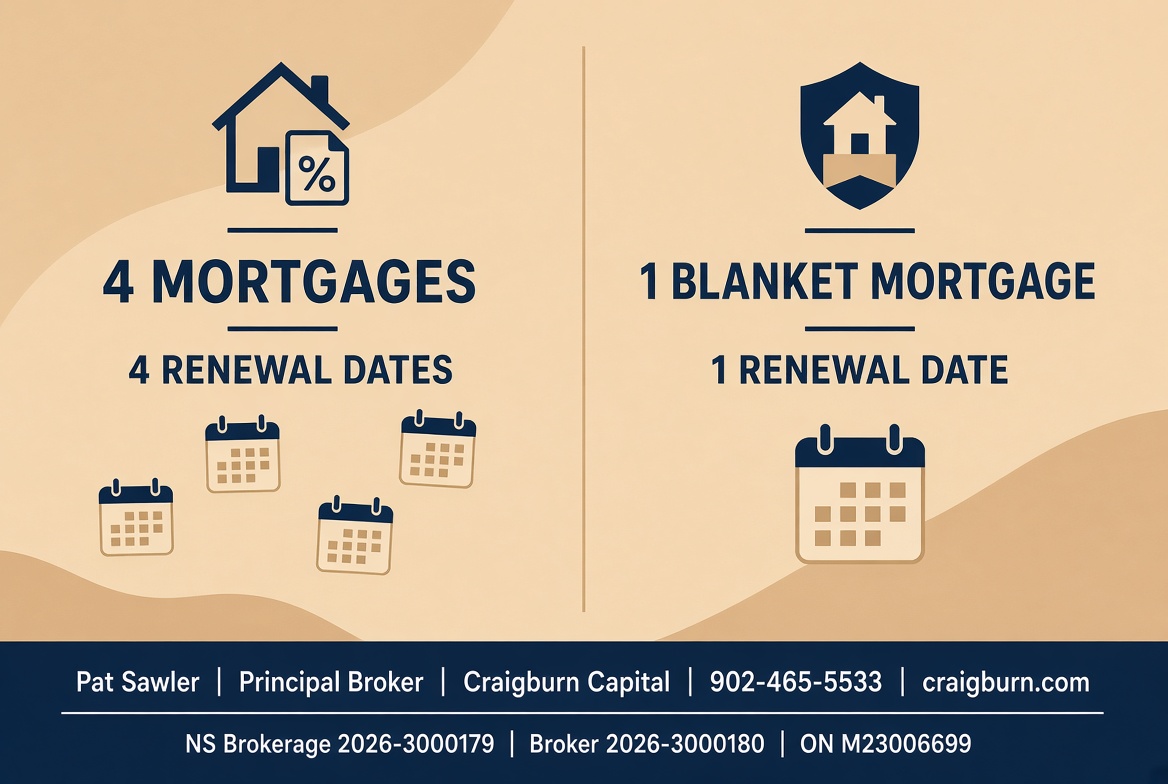
I had a landlord call me in a bit of a panic a few months back. He owned four rental properties, each with its own mortgage, each with a different bank, each renewing on a different month of the year. Every renewal was its own fire drill — new paperwork, new rate negotiation, new stress, four times a year instead of once. He’d never heard there was a different way to do it.
How does a blanket mortgage actually work?
Instead of underwriting each property as its own deal, a lender looks at the portfolio as a whole — the combined rental income, the combined expenses, the combined equity — and finances it as one commercial file. You qualify as a package, not as four separate fights for four separate approvals.
Why would a landlord want one mortgage instead of several?
A few reasons come up most often:
- One renewal date a year instead of four scattered through it
- Often better overall terms when a lender sees the full portfolio and its blended risk, rather than underwriting each property in isolation
- Less paperwork and less time re-proving income every time one property comes up for renewal
- Easier to pull equity across the portfolio to fund the next purchase, instead of refinancing one property at a time
Is a blanket mortgage the same as a regular commercial mortgage?
Not exactly. A blanket mortgage is a structure — multiple properties under one loan — that can sit inside either a residential or commercial lending framework depending on the number of doors, the property types, and the lender. Every lender treats that threshold a little differently, which is exactly the kind of detail worth walking through before assuming you know which category you fall into.
What do lenders look at to qualify a blanket mortgage?
Mostly the properties themselves — the combined rental income against the combined expenses and debt, often called the debt service coverage ratio. Your personal financial picture still matters, but the properties largely qualify themselves rather than leaning entirely on your personal income the way a single residential mortgage would. CMHC has useful background on how rental and multi-unit financing is evaluated, if you want the longer technical version: cmhc-schl.gc.ca.
Frequently asked questions
What is a blanket mortgage?
A single mortgage that covers two or more properties under one loan, rather than a separate mortgage for each one.
How many rental properties do I need before a blanket mortgage makes sense?
There’s no fixed number. It depends on your properties, your lender options, and whether consolidating actually improves your rate or terms — two very different properties might not benefit the way four similar ones would.
Does a blanket mortgage cost more than separate mortgages?
Not necessarily. Closing and legal costs can come in lower since there’s one closing instead of several, though pricing varies by lender and situation.
Who this is actually for
If you own more than one rental property and you’re tired of renewing on four different clocks, that’s exactly the kind of file I like working on. I pull it together with my commercial lending partner, structure it as one request instead of several separate ones, and walk you through whether a blanket structure actually saves you money — or whether keeping your properties separate is the smarter move for your situation. Every portfolio is different, and that’s the first thing worth figuring out.
If you’re sitting on a handful of renewal dates scattered through the year and wondering if there’s a cleaner way, that’s exactly the conversation worth having. Start here: https://craigburn-capital.mtg-app.com. For the full rundown of how we handle single-file comparisons across lenders, see our earlier piece: Five Lenders, One Hit.
I look forward to hearing from you in regard to your mortgage needs.
902-465-5533. I answer.
Patrick
p.s. Start your application anytime: https://craigburn-capital.mtg-app.com
p.s. Prefer to talk first? Book a time here: https://patricksawler-craigburn.zohobookings.com/3983211000000025015
p.s. NS Brokerage 2026-3000179 | Broker 2026-3000180 | ON M23006699
p.s. Get the Craigburn mortgage app for updates on your file
Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone.
Own more than one rental property and tired of juggling renewal dates? Reach out — 902-465-5533, or start here: https://craigburn-capital.mtg-app.com