When Should I Start Shopping for My Mortgage Renewal?
When should I start shopping for my mortgage renewal? About four months before your renewal date. That gives you time to get a rate hold, compare lenders and negotiate, without waiting for the renewal letter your lender sends. If your lender is a bank or another federally regulated lender, that letter only has to arrive 21 days before your term ends.
Here is what I see most often. A renewal letter shows up with one rate on it, the date is close, and signing feels easier than asking questions. But your current lender is rarely the only good option, and the rate on that letter is the start of a conversation, not the end of one. The good news is that you do not have to do the shopping yourself. That is my job: one application, one credit pull, and I compare 45 lenders and hundreds of products on your behalf.
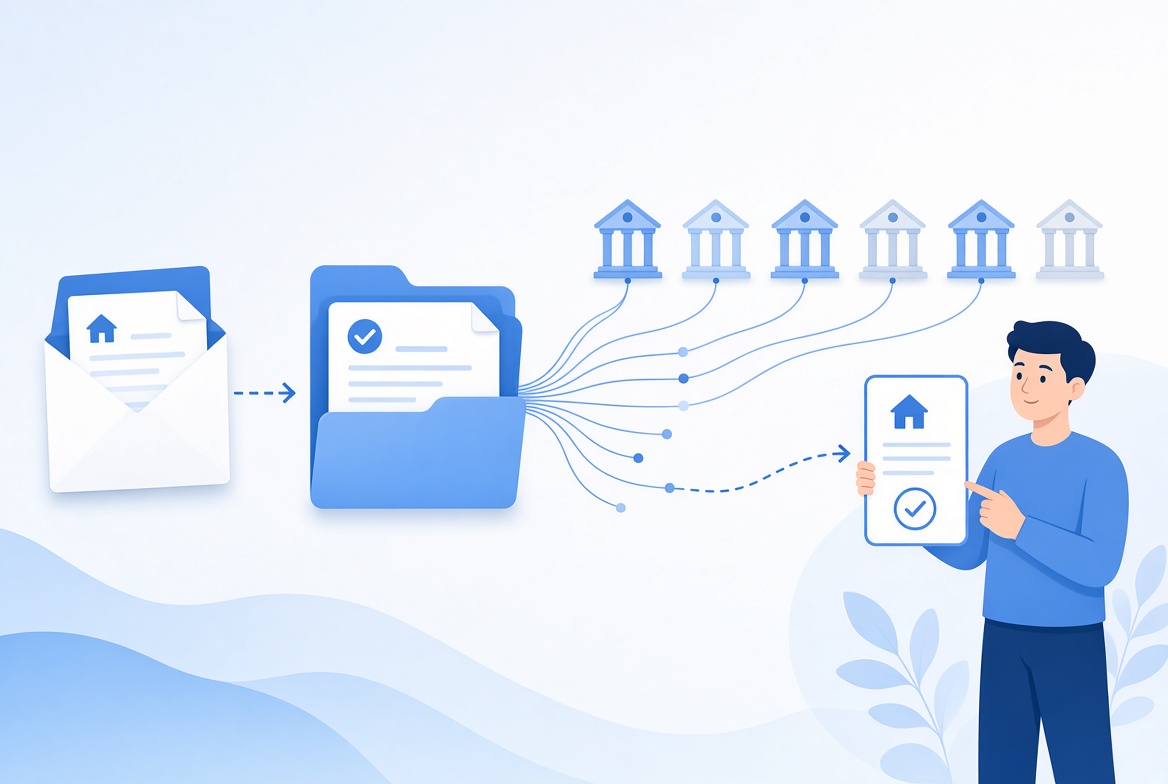
When should I start shopping for my mortgage renewal?
About four months before your term ends, or roughly 120 days. The Financial Consumer Agency of Canada gives the same advice: start looking a few months ahead rather than waiting for your lender’s letter. Four months is enough time to get a rate hold, collect real quotes and negotiate, with room to spare if paperwork takes longer than expected.
Why not just wait for my lender’s renewal letter?
Because that letter is a legal minimum, not a starting gun. A federally regulated lender must send your renewal statement at least 21 days before your term ends. Three weeks is tight if you want to compare lenders, and the rate on the letter is not always the best one available to you, from your lender or anyone else. When you arrive with competing offers, you are negotiating from a much stronger place.
What is a rate hold, and does it cost anything?
A rate hold means a lender or broker agrees to keep a quoted rate for you for a set time, usually 90 to 120 days, at no cost. If rates rise while you compare, you have a rate to fall back on. If they fall, you are not stuck with the old quote. With the Bank of Canada raising its rate to 2.50% on October 28, a hold is a sensible habit any time you are within four months of renewal. I arrange the hold as part of the shopping, so it is already in place while we compare.
Can I switch lenders when my mortgage renews?
Yes. You do not have to stay with your current lender, and at the end of your term you are free to move. The new lender still has to approve you, and there can be costs such as legal, discharge and appraisal fees. If your mortgage is registered as a collateral charge, switching can cost more, so I check that first. Since late 2024, federally regulated lenders no longer have to put an uninsured mortgage through the stress test when you switch at renewal, in most cases where the amount and amortization stay the same. That makes moving easier than it used to be. If you are curious how a new lender will look at you, I wrote a short guide on how to qualify for a mortgage.
What should I do, and when, before my renewal?
About 120 days out: I get your rate hold and look at the details of your current mortgage.
About 90 days out: I take your one application to my lenders and bring back real quotes.
About 60 days out: We compare the offers. If you would rather stay where you are, we use the best one to negotiate with your current lender.
By 21 days out: A federally regulated lender’s renewal statement is due. If yours has not arrived, ask for it.
Already inside 60 days? It is still worth comparing. Start now and we will work with the time we have. I also keep an eye on where rates are heading, and wrote about it in Are mortgage rates going up in Canada? What to do now.
Who this is actually for
Anyone whose mortgage renews in the next year, anyone who has a renewal letter on the kitchen table and is not sure what to do with it, and anyone on a variable rate who is watching the Bank of Canada. You do not need to have a plan yet. You just need to start early enough that you have choices. I do the comparing with one application and one credit pull, so you get the whole market without doing the legwork.
If your renewal is coming up and you want the full market compared, start here: https://craigburn-capital.mtg-app.com
Frequently asked questions
When should I start shopping for my mortgage renewal?
About four months, or roughly 120 days, before your term ends. That is enough time to get a rate hold, compare lenders and negotiate without being rushed by your lender’s renewal letter.
How early can I get a rate hold on my renewal?
Most lenders and brokers will hold a quoted rate for about 90 to 120 days at no cost, so you can get one about four months before your renewal date.
Can I switch lenders when my mortgage renews?
Yes. You can renew with a different lender at the end of your term. The new lender has to approve you, and fees such as legal, discharge or appraisal costs may apply, so compare the full cost and not just the rate.
When does my lender have to send my renewal letter?
A federally regulated lender, such as a bank, must send your renewal statement at least 21 days before your term ends. That is the legal minimum, so waiting for it leaves very little time to compare.
Buying or renewing? Start your application here: https://craigburn-capital.mtg-app.com
I look forward to hearing from you in regard to your mortgage needs.
902-465-5533. I answer.
Patrick
p.s. Ready to start? Apply here: https://craigburn-capital.mtg-app.com
p.s. Prefer to talk it through first? Book a time with me here: Schedule a call
p.s. FSRA Principal Broker License #M23006699, Craigburn Capital. NS Brokerage 2026-3000179, NS Broker 2026-3000180.
p.s. Get the Craigburn mortgage app: https://craigburn-capital.mtg-app.com
Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone. Service aussi disponible en français.
Call 902-465-5533 or start your application today.