Waiting Is the Hardest Part. But It Doesn’t Have to Be.
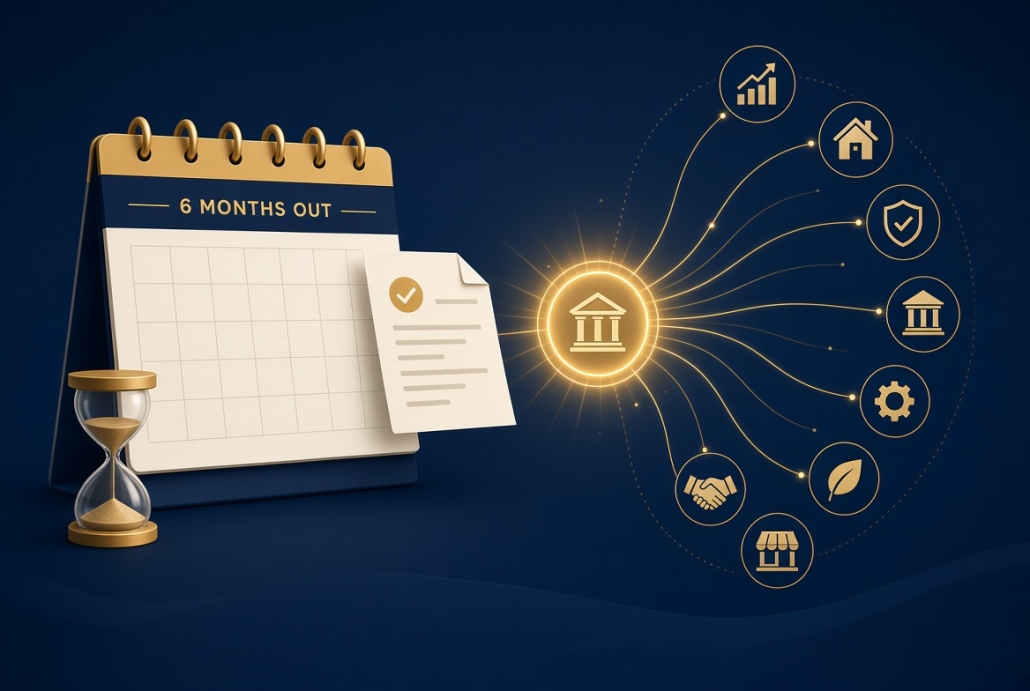
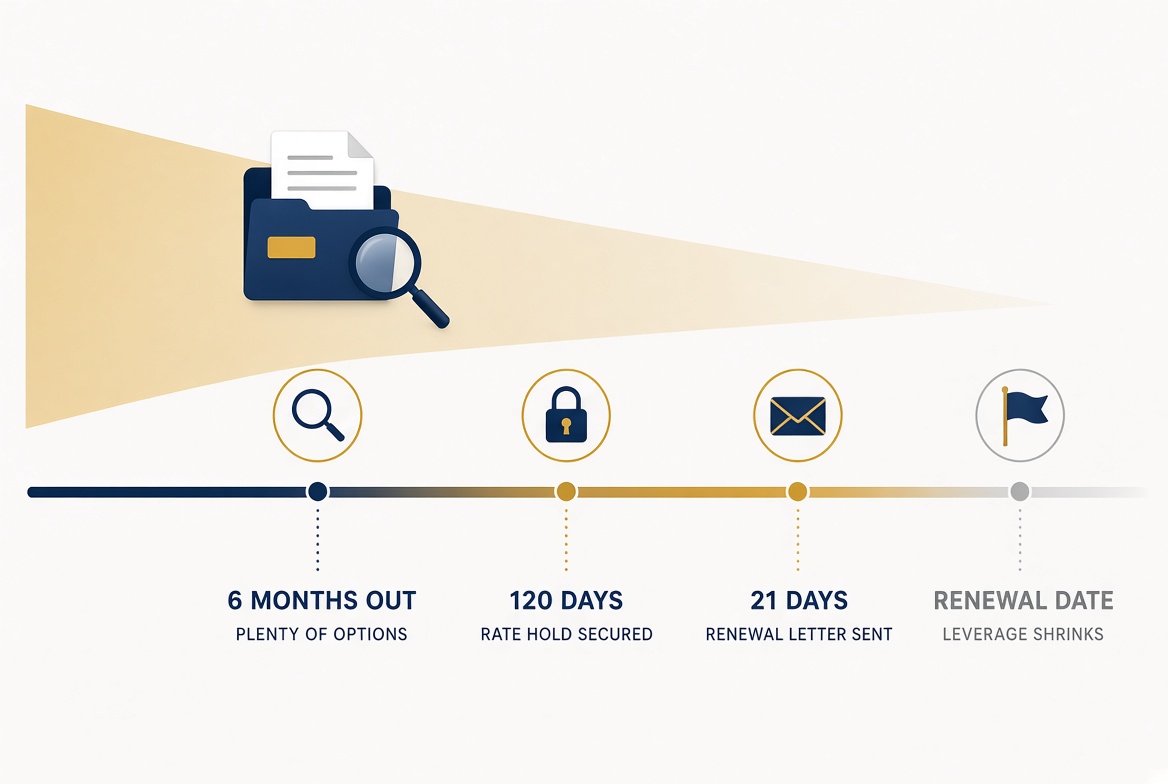
Start looking at your mortgage renewal about six months before your term ends, not when the lender’s letter arrives. Federally regulated lenders only have to send the renewal statement 21 days before maturity, and by then most of your negotiating room is gone.
When should I start shopping for my mortgage renewal?
About six months out. That is when you still have time, and time is what creates leverage. Early on you can ask for a rate hold, compare what the market is actually offering, and decide whether staying or switching makes sense without a deadline pushing you around.
Wait for the letter and the clock works against you. You get an offer, a signature line, and a few weeks to decide. Most people sign, because it is easier than starting from scratch.
Why is the renewal letter a bad starting point?
Because it is the lender’s offer, written by the lender, to the borrower the lender expects to stay. The Financial Consumer Agency of Canada tells borrowers to begin a few months before the term ends and not wait for the renewal letter. The letter is where you end up if you do nothing.
Who does the shopping when I renew with Craigburn?
I do. You send me your renewal date and your current mortgage details, we complete one application, and I do one credit pull. From there I take your file to the lenders I work with, around 45 of them and hundreds of products, and bring back the options that fit, with the real cost of each one laid out side by side.
You are not filling out application after application, and you are not comparing rate sheets at the kitchen table. That is the work I do, and starting six months out gives me room to do it properly.
Can I switch lenders at renewal without a penalty?
Usually yes, because your mortgage is open for prepayment at the end of the term. Many lenders will also cover the legal and transfer costs on a straight switch. What can complicate it is a collateral charge, a loan amount that goes up, or a longer amortization, any of which can add fees or trigger a new insurance premium. This is why the file should be reviewed before you sign anything, not after.
What should I be comparing besides the rate?
Look at the prepayment privileges, the penalty formula, whether the mortgage is registered as a collateral charge, the amortization, and the portability. A renewal offer that looks fine on the rate can quietly take privileges away, and over five years that adds up. I check all of it for you, and I will tell you plainly when staying put is the best move.
What if my renewal is less than six months away?
You still have options, they are just narrower. Send me the letter you received and your renewal date, and we will see what can be done in the time left. Every week closer to the date takes something off the table, so sooner is always better than later.
Mortgage renewal FAQ
When should I start shopping for my mortgage renewal?
Start about six months before your term ends. That gives you time to compare options, line up a rate hold, and plan around any penalty if you want to move early.
Does my lender have to send a renewal letter?
Federally regulated lenders such as banks must send your renewal statement at least 21 days before your term ends, according to the Financial Consumer Agency of Canada. That is a minimum, not a recommendation to wait for it.
Will it cost me anything to switch lenders at renewal?
Often very little. At the end of your term you can generally move without a prepayment penalty, and many lenders cover the legal and transfer costs on a straight switch. The exceptions are collateral charges, added fees, and any change that increases your loan or amortization, so the file needs a proper review.
What if I forget about my renewal date?
If you do nothing, most lenders will renew you automatically into whatever they offer. It is not always their best rate, and your leverage is gone once the date passes.
Have a renewal coming up in the next six to twelve months? I would be glad to take a look.
I look forward to hearing from you in regard to your mortgage needs.
902-465-5533. I answer.
Patrick
p.s. Ready to start? Apply here: https://craigburn-capital.mtg-app.com
p.s. Prefer to talk it through first? Book a time with me here: Schedule a call
p.s. FSRA Principal Broker License #M23006699, Craigburn Capital. NS Brokerage 2026-3000179, NS Broker 2026-3000180.
p.s. Get the Craigburn mortgage app: https://craigburn-capital.mtg-app.com
Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone. Service aussi disponible en français.
Call 902-465-5533 or start your application today.