Should I renew early after a rate hike?
Should I renew my mortgage early after a rate hike? Sometimes, but not automatically. If your rate is fixed, Wednesday’s Bank of Canada hike didn’t change your rate or the fixed rates on the lender sheets I looked at this week. If your rate is variable, it already went up. Either way, the smart move depends on how many months you have left and what it would cost you to break early.
On Wednesday, October 28, the Bank of Canada raised its overnight rate a quarter point to 2.50%. By Thursday morning the banks and lenders I work with had moved prime from 4.45% to 4.70%. The question on everyone’s mind now is whether to lock in before rates move again. (If you missed my take on the hike itself, The Tightrope Walker has the full story.)
What Did the Bank of Canada Rate Hike Actually Change?
It changed anything tied to prime, and not much else yet. Variable-rate mortgages and home equity lines follow prime, so those rates went up within a day. Fixed rates are a different animal: they track bond yields, not the overnight rate, and the fixed rates on the lender sheets I checked this week did not rise with the hike.
That’s why a hike can feel dramatic on the news and be a non-event for your fixed-rate mortgage. Your rate is locked until your term ends. What the hike can do is nudge the rate you’re offered when it ends.
Should I Renew My Mortgage Early After a Rate Hike If I Have a Fixed Rate?
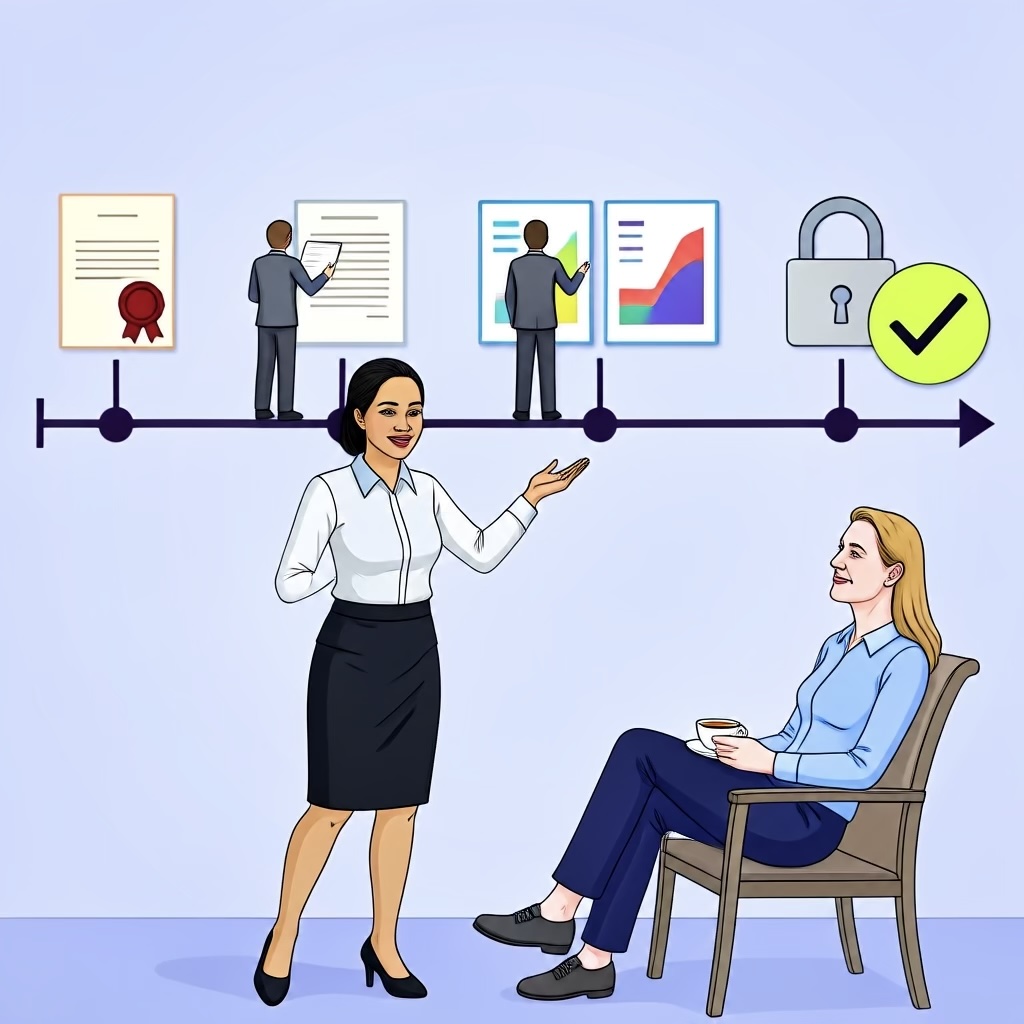
Only if the math clearly works. Many lenders will let you lock in a renewal rate about 120 days before your maturity date, and that window is where early renewal is cheap or free. Go earlier than your lender’s window and you may owe a prepayment penalty, which on a fixed rate is the greater of three months’ interest or the interest rate differential. That second number can be much bigger than people expect, and every lender calculates it differently.
My honest rule of thumb: if you’re inside four months, it’s worth looking at your options now. If you’re a year out, paying a penalty to chase a rate that may or may not move is rarely a good trade. The rate you save has to beat the penalty you pay, and nobody can promise where rates go next.
What If My Mortgage Is Variable?
Your rate went up with prime, and what happens next depends on your type of variable. If your payment floats with prime, your payment just rose. If your payment is fixed, your payment stayed the same but more of it now goes to interest and less to principal. Neither is an emergency, but both are worth a look.
Many lenders will let you convert a variable mortgage to a fixed rate without a penalty, though the fixed rate you’re offered may not be their best. That’s one of the reasons I check what the wider market is offering before anyone converts. Your credit also plays a part in the rate you land, and I’ve written about how your credit score affects your mortgage rate before.
Why Not Just Sign the Renewal Letter My Bank Sends?
Because the letter is your lender’s offer, not the market. It’s built to be easy to sign, and easy is not the same as best. At maturity you are free to move to another lender, and some lenders will even cover the costs of a straight switch.
This is where I come in. I do the shopping for you: one application, one credit pull, 45 lenders and hundreds of products. You don’t have to ring around, play lenders off each other or decode the fine print. I take your renewal to the whole lender network and bring you back what I find, including the times when your current lender really does have the best offer. If that’s the case, I’ll tell you so.
How Far Ahead Should I Start Planning My Renewal?
About four to five months out. That’s early enough to compare lenders and hold a rate, and recent enough that the numbers you’re looking at are still real. In a week like this one, it also gives you time to watch what the market does before you commit.
Frequently Asked Questions
Does a Bank of Canada rate hike change my fixed-rate mortgage?
No. A fixed rate stays the same for your whole term. A hike mostly affects variable and prime-linked mortgages right away, and it can influence what rate you are offered at your next renewal.
Can I renew my mortgage early?
Often yes. Many lenders let you lock in a renewal rate about 120 days before your maturity date. Renewing earlier than your lender’s window can trigger a prepayment penalty, so check the terms before you commit.
How far ahead should I start looking at my mortgage renewal?
About four to five months before your maturity date. That is early enough to compare lenders and hold a rate, and recent enough that the numbers are still current.
What happens if I just sign the renewal letter my lender sends?
You lock in that lender’s offer for the new term, and it may not be their best rate or the best rate available elsewhere. At maturity you are free to compare other lenders before you sign.
One more thing before I sign off. This week we lost Sir Patrick Stewart at 86. I’ve been a Star Trek fan for as long as I can remember, and I’m lucky to share a first name with the man who gave Captain Picard his voice. Captain Picard had a line that fits:
“What we leave behind is not as important as how we’ve lived.”
— Captain Jean-Luc Picard
A mortgage renewal is a small version of that. The rate matters, but the real question is what you want the next five years to look like.
I look forward to hearing from you in regard to your mortgage needs.
902-465-5533. I answer.
Patrick
p.s. Ready to start? Apply here: https://craigburn-capital.mtg-app.com
p.s. Prefer to talk it through first? Book a time with me here: Schedule a call
p.s. FSRA Principal Broker License #M23006699, Craigburn Capital. NS Brokerage 2025-3000179, NS Broker 2025-3000180.
p.s. Get the Craigburn mortgage app: https://craigburn-capital.mtg-app.com
Patrick Sawler is a mortgage broker and owner of Craigburn Capital, licensed in Nova Scotia and Ontario, with private financing available in New Brunswick and PEI. He answers his phone.
Call 902-465-5533 or start your application today.


